Tag Archives: function

Spark Energy’s Income Statement Is In For Some Pain
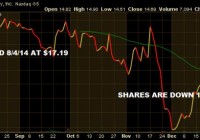
I’m taking my losses and selling SPKE before Q4 earnings. SPKE has abandoned its plan to increase spending to acquire customers and has now doomed its income statement. SPKE’s model isn’t built for constant shifting between high and low spending and this will create many problems. In hindsight I always knew what Spark Energy (NASDAQ: SPKE ) was, and I detailed that in my initiation article, so maybe I shouldn’t be as disappointed in how this trade turned out as I am, because I’m actually really disappointed. I’m selling SPKE on Monday at the open down 14.5% or so (depending on where this stock opens) for a couple reasons but primarily because the company has no idea what it’s doing. It’s literally operating in an industry where all you have to do is spend endlessly to acquire customers (welcome to the S&M black hole!), pray that you can do a decent job at hedging exposure to natural gas (creating the spread that creates the margin), do a good enough job to hang on to the majority of customers (but trust that there will in fact be churn), hope the share price goes higher, raise debt or finance via equity offering, and repeat the process. The most important must-do by far of those listed is spend, by the way. That’s all you have to do. Heck, I’ll make it even simpler for you SPKE – use your new revolver, yeah the one with the $37.9 million in current borrowing availability and go acquire customers. It’s that easy. Just spend, spend, spend! What do you not get about that? (click to enlarge) But of course, SPKE management couldn’t do that. No, SPKE management just announced on the Q3 CC that it’s executing its third strategic shift in as many years. What is this shift I speak of? Well, I’m speaking of the shift to (again) lower customer acquisition spending (this is after ramping customer acquisition spending in mid-2013 after lowering it in early-2012) to focus on “the longer-term sustainable growth consistent with our focus on distributable cash flow (SOURCE: SPKE Q3 CC )”, whatever that means. I say whatever-that-means because there’s nothing “longer-term” about SPKE’s business. It’s a commodity of the worst variety, meaning it has zero differentiation from competitors and zero value-prop to customers other than at any given point it can offer electricity services at a cheaper price than its competitors, which is by definition the definition of a commoditized business. This is pretty well evidenced in the attrition SPKE experiences regularly. I mean consider this, SPKE spent to acquire 91,000 customers between Q2 and Q3 while at the same time 44,000 customers walked through the door on the way to the next commoditized provider: (click to enlarge) Talk about an inefficient model. Now getting back to the stated reduction in spending and focus shift, this becomes a big problem because every time SPKE drops customer acquisition spending, as they did in FY2012, SPKE sees its revenues fall off a cliff. I’ve detailed this in SPKE’s financials in previous articles and even promoted this as a reason that “value” existed in buying the shares when I did. Of course this was under the assumption that management would actually do what it said it was going to do at the time I bought shares, which was spend, spend, spend. I only bought these shares because I wanted to piggy back on the ramped spending and the fact that the spending costs (customer acquisition costs) get recorded as an asset on the balance sheet and accounted for through D&A over 8 quarters. I wanted to front-run the what should have been explosive top-line growth with what would have been for a while minimal D&A additions to the income statement. This would have artificially enhanced the income statement and I was hoping propped the stock to a point that I could have sold at a healthy gain all while collecting a fat dividend for waiting. Yeah, it didn’t exactly turn out as planned. So, here we are with today’s “new model” that SPKE is promoting as the way of the future. Forget that the company has a horrible looking S-1 filing with three years of volatile financials and that the company has zero history of being able to execute on any single strategic initiative for more than a quarter or two. Don’t mind that. Let’s just get long some shares because, well, this is the way of the future. This is the “longer-term” more “sustainable” way to run this commoditized business. I think SPKE thinks it’s something it’s not and that can be a very dangerous thing. It has been for bagholders in the past and has been for this bagholder through 5 five months of ownership. The Ramp UP and The Ramp DOWN SPKE’s creating huge financial volatility for itself by constantly ramping up and ramping down spending. It’s also creating volatility for itself in not having a focused approach to its S&M efforts. SPKE also noted on its Q3 CC that it’s shifting its focus again back to commercial accounts, something it had completely abandoned after focusing on several years ago. You see a pattern here? SPKE seems to always be chasing the “hot dot” of the moment and seems to be the real case of the tail wagging the dog. Take a look at what it’s done for the income statement: (click to enlarge) So, first things first SPKE’s 9M results are absolutely blown up because 1H/14 was blown up by spending not being ramped until Q3/13. Let me explain how that works. SPKE can easily track revenues growth with S&M spending growth. What it can show is that once it increases spending, roughly three months into elevated spend levels revenue growth begins to turn upward. After about six months revenue growth reaches a terminal velocity where more spend is needed to created more velocity. That’s a pretty easy equation to follow. Now, I don’t know if that is uniform in this space or not but that’s what SPKE’s history has shown us. When SPKE decided to increase S&M spend in Q3/13 that means Q1/14 was only seeing terminal velocity of the initial increases in spend levels (which were increased from there further) and in fact the spend was being spread across larger geographic areas. This means that velocity was lower across a wider casted net which means sales were lower than they could have been had SPKE simply been concentrated (further saturating an area with spend). Yet another misstep. Regardless, that explains the 9M results showing such a variance from the Q3 results. Oh, by the way, we’re heading back to the days of reduced spending but don’t worry things are going to be different this time around because management has a plan. The 9M/14 results show flat top-line results, better NAO revenues (which are basically hedging gains or losses and largely SPKE has shown it has zero control and/or predictability in this line item), much higher operating expenses, and growing operating and net losses. This is inclusive of the benefit of a lower D&A expense, which will slowly be getting bigger quarter after quarter for the next six quarters before shrinking assuming SPKE actually maintains its plan to lower spending. There’s a huge amount of customer acquisition costs that have to be D&A’d to the income statement from the previous quarters spending ramps, regardless of if SPKE abandons the strategy half way through. What drove the 9M and quarterly results? S&M spending and hedging. That’s the entire business here folks. There’s a guy knocking on your door or a flyer in your mail offering you electric service. Is it at a lower cost or not? That’s what drives SPKE’s income statement. It’s really not that complicated but somehow SPKE has found a way to complicate it. What’s really sad is that had SPKE just stayed the course it might have been able to finally hit a vein regionally that it had some traction with or find a market that actually responded to its spending. I mean the cash is already gone, why not actually use what’s left on the balance sheet and dip into the revolver? Everything outlined in red is bad. The entire income statement is bad. I mean just look at that net income destruction Y/Y from ~$12 million to ~$7 million. Now, I’ll give SPKE that it hadn’t had a full 9M to show its increased spending and larger customer base within the 9M/14 figure, and subsequently SPKE went out and acquired some customers from outside sources so at least it’s trying the M&A route, but the comps it was up against in 2014 weren’t tough considering it didn’t ramp 2013 spending until Q3 as well. I just don’t have any sympathy for SPKE’s financials at this point because it’s doing this to itself. SPKE’s Adjusted EBITDA really shows the customer acquisition cost spend differential and why I say that once you start spending in this model you have to continue to spend forever, that the model basically becomes a constant black hole of S&M dollars: (click to enlarge) You can see how I’ve outlined the massive difference in customer acquisition costs in the comparable periods. In Q3/14 it was roughly 400% Q3/13, you don’t think that should have been driving revenues? You don’t think the ramp from previous quarters should have been driving revenues? The fact that the Q3 income statement showed flat revenues Y/Y in Q3/14 is a clear sign that the ship is already starting to take on water. That ramped spending is about to start to really add up on the income statement over the next few quarters in the form of a D&A uptick and SPKE isn’t going to have the revenues to offset it. It’s going to be taking huge losses on that when it happens. The spending difference becomes pretty egregious on the 9M side of the Adjusted EBITDA. 9M/14 customer acquisition costs were roughly 700% 9M/13 spending. Even with that, even with the compounding spending that should have reached maximum velocity from quarter prior SPKE still posted flat revenues. What an absolute disaster. This is going to bury SPKE’s stock over the next few quarters and was something I outlined in my prior articles. If SPKE didn’t have consecutive and sequential blowout top-line growth quarters you want nothing to do with this company. It won’t have the top-line to make up for the D&A uptick. That in a nutshell explains the bear thesis around this name going forward. This stock is dead, it just doesn’t know it yet. Do I need to even note those Adjusted EBITDA figures? Didn’t think so. Now, you can imagine what these types of operations have done for cash flows, which actually account for the cash outflows of the customer acquisition costs as they are incurred: (click to enlarge) Yeah, the cash from operations has been blown up and maybe that’s the reason for the strategy shift towards lower spending. Maybe SPKE management saw that what they were doing (again) wasn’t working and decided that conserving the last of the cash and the last of the liquidity via the revolver was the primary concern. I mean to hell with the income statement, that’s just for accounting nerds, the cash flow statement is dealing in real dollars, actual cash and when you run out of that and still don’t have a plan on the board for how you turn the corner and make it to spring you don’t get to play anymore. Even at minimal levels of revenues if SPKE can get spending down low enough it can generate good levels of FCF. Just look at both of these periods listed here. Solid FCF could allow the company to rebuild its cash balances and make one more run at another strategy shift or whatever else the company might have in mind. The point is, just don’t run out of cash. I think that’s probably the best explanation I have for what’s been announced and what’s about to be allowed to happen to the incomes statement. Where’s the trade? The trade is to sell SPKE and don’t ever consider it on the long side again. This business model and this niche isn’t one that you want to invest in for all the reasons mentioned in the beginning of this article. It’s a commodity with no way to differentiate itself and no way to protect itself from the wide swings that come with trying to hedge energy exposure on a constantly fluctuating demand. SPKE always was a bad business but I thought I could catch a few cheap points riding an accounting loophole that would have allowed revenue to grow while expenses remained artificially low on the income statement. I was wrong and lesson learned. I recommend a sell of SPKE. I look forward to providing continuing coverage in the future. Good luck to all.
Using ESG Screens For Utilities Stock Selection: American Electric Power Comes Out Ahead

Summary AEP comes out as the top pick after fundamental analysis and ESG screening. AEP’s fundamental and ESG scores were impressive in comparison to the rest of the sector. Since August 2014, its stock has performed admirably. Environmental, social, and governance (ESG) screening strategies can find alpha in innovative companies. Utilities fit well into this analysis and screening methodology. Last July, while looking for an investment opportunity, I recalled New York City’s legendary summer blackouts. During those fateful evenings in August 1959, July 1977, and August 2003, the city’s electric utility, Con Edison, played a feature role in the events that were retold by patrons for decades. While Con Edison worked feverishly to restore power to the city, New Yorkers took off their shirts and wrung out their sweat-soaked handkerchiefs while sitting on their stoops, balconies, and porches waiting for a cool breeze from the East River. With this picture, I decided to explore the utilities sector for an investment opportunity. Utilities have been favored by investors for dividend yields and capital preservation. Many utilities are under-covered by securities analysts and as such, price discovery and liquidity are potentially hampered, creating potential long-term investment opportunities according to Target Rock Advisors, a socially responsible investing (SRI) consulting company focused on the utilities sector. I am an SRI champion so I began my sector analysis by applying an Environmental, Social, and Governance (ESG) screen. Afterwards, I look at fundamentals. Since I am investing for the long term and income, ESG screening is a sensible starting place. I used the Thomson Reuters Corporate Responsibility Ratings (TRCR) ESG Port for my first screen. The TRCR dataset allowed me to extract the U.S. utilities sector comprised of electric utilities, multiline utilities, natural gas utilities, and water & other utilities. My objective was to find the top performing utilities while applying an ESG tilt. The database is built to allow investment managers to select companies using a “best in class” measure, forgoing the alternative of ethical exclusions also called “negative screening”. This process presented me with the top ESG performers in the utilities sector. I retrieved 47 companies in all. Each company has four scores: an Environmental Score, a Social Score, a Corporate Governance score, and a composite ESG score which is the average of the three. The scores range from 1 to 100. Rather than simply ranking the companies by their composite ESG scores, I applied a weighted screen having greater leverage on the Social and Governance Pillars. Utilities are indubitably joined-up with environmental matters and actively comply with compulsory environmental regulations. To a large extent, utilities have recognized their environmental risks–so I reasoned that these risks have been priced into their stocks (with the exception of a “black swan” event). This relegated Environmental Scores to a lower weighting by my design. High Corporate Governance Scores are typically accepted as an indicator of strong corporate performance and lower risk since they are indicative of the company’s good management, strong board structure, as well as corporate charters and bylaws that are favorable to shareholders. Additionally, as a regulated industry, compulsory reporting assures transparency, another component of strong corporate governance scores. Clearly, “a strong governance rating would be a better long term indicator of stock market performance versus a strong environmental rating” according to Richard Rudden of Target Rock. Well managed companies have long term horizons that bode well for economic sustainability. A utility’s Social Score is perhaps the most revealing ESG indicator and the best place to look for an investment advantage, assuming that there is an accompanying strong corporate governance score. Social scores have key performance indicators for Employment Quality, Health & Safety, Training & Development, Diversity, Human Rights, Product Responsibility and Community Involvement. In Target Rock Advisor’s words, “Utilities have an abiding interest in supporting local and regional health and economic development, since those areas represent their core markets.” In effect, utilities are joined by the hip to the markets that they serve. Economic Analysis The final decision comes after a proper economic analysis. To do this I used MarketGrade.com’s StockGrader tool. StockGrader applies a fundamental analysis to companies and grades them in a range of 1 to 100. It uses technology to analyze a public company’s financial statement and presents the results in a user-friendly format. According to StockGrader, AEP distributed dividends uninterrupted for at least five years and based on the latest payout the stock was yielding 3.80%. The company was showing accelerating margin growth over the last three quarters and profits grew very strongly from the previous quarter compared to a year prior plus full year net income showed healthy gains from three years ago. Their latest report also showed a remarkable 20.68% increase from its total sales recorded during the same quarter last year. From a valuation perspective, the company’s current market value is only 1.56 times its tangible book value, which excludes intangible assets such as goodwill. This, according to StockGrader means investors are currently assigning very little value to the company’s ongoing business and that its future earnings growth when combined with AEP’s market cap of $25.53 billion (which is only 7.31 times larger than its latest quarterly net income plus depreciation), seems like an attractive valuation. My Analysis Steps Here is an outline of my analysis. 1. Create a portfolio of companies in the utilities sector with Thomson Reuters Corporate Responsibility Ratings (TRCR). 2. Screen for the top performers in the Social pillar with TRCR. Tag the top ten performers. 3. Screen for the top performers in the Governance pillar with TRCR. Tag the top ten performers. 4. Identify the companies that are in both top ten performer groups. This revealed the following companies: American Water Works (NYSE: AWK ) Xcel Energy (NYSE: XEL ) Exelon Corp. (NYSE: EXC ) American Electric Power (NYSE: AEP ) 5. Access StockGrader for economic ratings as a method of performing my fundamental analysis. 6. Select the company that presents the best combination of these metrics. Top Companies Scoring Table Company EN Rating SO Rating CG Rating ESG Rating ESG Rank Market Grader Rating Market Grader Action American Water Works Company Inc 63.4 66.2 73.7 67.8 86.3 49.7 Sell Xcel Energy Inc 70.0 70.7 72.9 71.2 91.4 43.8 Sell Exelon Corporation 70.6 78.0 71.8 73.4 94.4 37.0 Sell American Electric Power Company 77.3 73.5 71.7 74.2 95.0 55.5 Hold American Electric Power Company Inc. My analysis resulted in the choice of American Electric Power Company Inc. AEP has been recognized within corporate social responsibility circles as an example of a good corporate citizen. Its fundamentals were impressive in comparison to the rest of the sector and made for a good economic selection. Since August 2014, its stock has performed admirably. A chart of AEP follows. (click to enlarge)

The Main Reason Why Indexers Will Likely Beat Active Stock Pickers

As we know most investors do not get the market returns that are available. Too many investors practice ‘loss aversion’ and sell stocks or funds when they see the stock markets collapse – this can contribute to losses and lower returns. Indexing is called ‘passive investing’ on the investment selection front; but its greatest gift is allowing investors to be passive on the emotional front. Vanguard research shows that indexers and those in low fee funds were able to stay the course and not react emotionally. Most of us likely know that most investors have historically underperformed the broad market indices and benchmarks to a very large degree. It is a very unfortunate trend and it is the reason why I write today, and the reason why I made the switch to a career in the land of finance and investing. Here’s a study that found that investors have turned very generous market returns into very modest returns. In 2001 Dalbar, a financial-services research firm, released a study entitled “Quantitative Analysis of Investor Behavior”, which concluded that average investors fail to achieve market-index returns. It found that in the 17-year period to December 2000, the S&P 500 returned an average of 16.29% per year, while the typical equity investor achieved only 5.32% for the same period – a startling 9% difference! It also found that during the same period, the average fixed-income investor earned only a 6.08% return per year, while the long-term Government Bond Index reaped 11.83%. Investors are attracted by the lure of the stock markets, company ownership, the juicy returns in robust bull markets, and they’re attracted by that gambling mentality – the chance that they might beat the markets, beat their neighbour and beat their brother-in-law. The studies on poor investor behaviour suggest that most investors are simply taking on too much risk. The problem is that gambling has not paid off; emotion gets the better of most investors whether they are individual stock pickers, holders of professionally managed mutual funds or index investors. There’s lots of bad behaviour to go around amongst all types of investors. That’s certainly why for most investors it’s prudent to evaluate that personal emotional risk tolerance level and match the risk or volatility level of the portfolio to said risk tolerance level. Investing should start with a few areas of questions or self-reflection, one being can I watch my paper net worth (the investment portion) get chopped in half or more and not panic? Find your risk tolerance level, create the matching portfolio. The bad behaviour and bad decision-making is across the board. We might conclude that humans do not make very good investors, for the most part. The task at hand might be to convince investors to stop looking, stop reading; even STOP THINKING! There is that wonderful expression that goes something like this … a portfolio is like a bar of soap, the more you handle it the smaller it gets. The most important part of investing is not stock selection or even style of investing. It’s about being able to stay the course. If you are an investor that has an incredibly high risk tolerance level (a very rare breed indeed), then it makes sense to seek out the assets that might deliver the greatest potential returns, risk can take a seat. For the risk averse investors (arguably that list would include the majority of investors), the greatest total return is achieved through the act of matching your portfolio to your risk tolerance level and simply taking the returns offered by that asset mix. The most important factor that might determine an investor’s success is patience, and being able to stick to the plan through thick and thin. Having a plan is key, sticking to that plan is crucial. It will come down to boring consistency and patience. Doing nothing is doing it right. OK, what we can do is invest on a regular schedule and that can often be set up so that the dollar cost averaging happens with a set-it-and-forget-it automatic investment plan. Vanguard has found that those who adopt a long term strategy in their 401k accounts and invest in the indexes or low fee managed funds have recently been able to ignore the market noise and simply stay the course. In 2011 during the European debt crisis the S&P 500 lost nearly 20% Vanguard investors didn’t panic (the correct move in hindsight). This comes from a previous study: In the first eight trading days of August [2011], including two of the most volatile days since 2008, just under 2% of 401(k) participants at Vanguard made a change to their portfolios. In other words, over 98% stayed the course. Ninety-eight percent took no action. Ninety-eight percent took the long-term view. Now it’s true, if choppy markets continue, we’ll see this number inch down. Ninety-eight percent of participants staying the course might become 97%. In October 2008, during the depths of the financial crisis, it became 96%-in other words, 4% of participants made a move. But the fact remains: those trading are a very small subset of investors. When we consider the findings of that Dalbar study and see only 4% of Vanguard 401k investors making any kind of move (reaction) during the most severe market correction since the Great Depression, I think that is very telling. There is value in being a passive investor in the emotional sense. There is value in investing without emotion. Don’t invest like the emotional James T. Kirk, invest like Spock. Letting the index or low fee fund manage your holdings for you simply means that you don’t have to watch, you don’t have to be emotionally involved. That detachment can pay dividends. Not to be morbid but studies have shown that the portfolios of the deceased have done quite well. Portfolios of investors who have forgotten that they have stock and bonds investments can also do quite well. It’s ironic that non-thinking (or less thinking) typically beats thinking when it comes to investing. This from a business insider article and a discussion between Barry Ritzhold and James O’Shaughnessy … O’Shaughnessy relays one anecdote from an employee who recently joined his firm that really makes one’s head spin. O’Shaughnessy: “Fidelity had done a study as to which accounts had done the best at Fidelity. And what they found was…” Ritholtz: “They were dead.” O’Shaughnessy: “…No, that’s close though! They were the accounts of people who forgot they had an account at Fidelity.” Apparently the forgetful make for wonderful investors. I get to deliver that wonderful surprise once a week or more to Tangerine clients. Some investors will forget that they moved some monies to an investment account 3, 4 or 5 years ago and I can deliver the good news on the returns. It’s certainly an opportunity to then remind investors that leaving their investments alone is often wonderful behaviour. Getting emotionally involved with your investments and your ability to fund your retirement years can be dangerous. It’s not surprising that for many, the further they can stay away from their investment decisions, the better. The passive nature of indexing allows for this detachment. We know that most professional managers will not get the market returns that are available, over time. And the Dalbar study shows that individual investors can hamper returns by an even larger degree. Also from that Business Insider Article, here’s an interesting (and very famous chart) that makes the rounds in discussions about investor returns. Please note, the editorial comment (IN RED) is from the link, and perhaps was added by Mr. Ritzhold. 🙂 (click to enlarge) Now that’s not to say that an individual stock picker cannot be a successful investor. If a stock picker is well diversified, is investing within his or her risk tolerance level, and that investor is then very patient and able to stay the course, that investor might do quite well. But again, it might come down to that investor being able to invest without emotion. Investing without emotion appears to be a tough task for the professionals and retail investors alike. I love reading the comments of Seeking Alpha reader and commentor buyandhold 2012 . The comments are generally the same theme … buy and hold, don’t sell. buyandhold states that he has never sold a stock, the holdings can only come and go if a company is acquired or goes out of business. He makes investing more about marriage than dating. He claims to have beat the markets over the decades, and even though this is the world wide web and mr buyandhold is anonymous I believe him. He follows the suggestions of Mr. Benjamin Graham and largely buys companies that have paid dividends (and dividend aristocrats) for an extended period. And then he holds. Buy. And then hold. That seems like a simple strategy that all of us can understand, but very few of us would be able to execute. Here’s one of his recent comments on an Exxon Mobil (NYSE: XOM ) article. DGI, what trips up many investors is that they focus on the short term rather than the long term. It is true that Exxon Mobil is not going to be a rock star growth stock on the price appreciation side in the next 12 months. But Exxon Mobil has a good chance of being a rock star growth stock on the price appreciation side over the next 25 to 50 years. I have been an Exxon Mobil shareholder for 44 years so I know that this stock really delivers the goods over the long term. That comment post says so much in the context of all of the noise surrounding the energy space and energy aristocrats and long term dividend payers. Buy, and hold. On the other side of the ledger and on Seeking Alpha, even within the dividend space, we hear so much on buy and selling and we see chart tools with buy and sell signals, there’s plenty of debate on what to do on a dividend cut or dividend freeze. Buyandhold has a suggestion, buy more when they’re on sale. Investing should be easy. For many it will come down to the advice of Mr. Warren Buffett – buy the broader market indices in the most cost effective manner possible and stay the course, and reinvest on a regular schedule. For stock pickers it may come down to the advise of buyandhold 2012 – buy great companies when they are at reasonable valuations and stick with your companies through thick and thin. Leave that SELL button alone. Thanks for reading. Happy investing, always know your risk tolerance level, and give a thought to the notion of international diversification. Dale Additional disclosure: Dale Roberts is an investment funds associate at Tangerine Investment Funds Limited. The Tangerine Investment Portfolios offer complete, low-fee index-based portfolios to Canadians. Dale’s commentary does not constitute investment advice. The opinions and information should only be factored into an investor’s overall opinion forming process. The views expressed are personal and do not necessarily represent those of Scotiabank