Tag Archives: management

Oil And Gas ETFs As Seen By Market-Makers
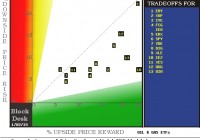
Summary Mostly there’s not very attractive candidates for new capital commitment in any current competition, in comparison with top alternatives. But they may be about even with the equity investment population overall. Better single-stock choices are to be outlined in our third survey, of the broad oilpatch, coming next. The oil commodity price decline scares nearly all investors ETF risk protection from a basket of similar eggs may not be all it’s cracked up to be. When we run our Intelligent Behavior Analysis of ETF price range forecasts derived from the hedging actions of market-makers [MMs], the resulting outlook is not very attractive. Here is a picture of how the current upside price prospects compare with what price drawdowns actually transpired following similar prior forecasts. (used with permission) The cast of characters: [1] Direxion Daily Energy Bear 3x ETF (NYSEARCA: ERY ) [2] SPDR S&P Oil & Gas Exploration & Production ETF (NYSEARCA: XOP ) [3] iShares US Energy ETF (NYSEARCA: IYE ) [4] First Trust ISE-Revere Natural Gas ETF (NYSEARCA: FCG ) [4] iShares US Oil & Gas Exploration & Production ETF (NYSEARCA: IEO ) [5] Direxion Daily Energy Bull 3x ETF (NYSEARCA: ERX ) [6] SPDR S&P 500 ETF (NYSEARCA: SPY ) [7] Vanguard Energy ETF (NYSEARCA: VDE ) [8] ProShares Ultra Oil & Gas 2x ETF (NYSEARCA: DIG ) [9] Energy Select Sector SPDR ETF (NYSEARCA: XLE ) [10] iShares US Oil Equipment & Services ETF (NYSEARCA: IEZ ) [11] SPDR S&P Oil & Gas Equipment & Services ETF (NYSEARCA: XES ) [12] ProShares Ultra Short Oil & Gas 2x ETF (NYSEARCA: DUG ) [13] Market Vectors Oil Services ETF (NYSEARCA: OIH ) The non-standard ETFs are ERX and DIG – leveraged long; ERY and DUG – leveraged short; SPY – a broad market tracker for background comparison. All the others are ETFs focused on the oilpatch in general or various parts thereof. The map places each ETF at the intersection of its forecast upside (the green horizontal scale) and its average actual worst-case price drawdowns following prior forecasts like today’s (on the red vertical scale). Attractive investments typically are found down in the green area. Each ETF is the product of its current market price and the MMs’ impression of what their clients (who have the money muscle to move markets) are likely to do in coming weeks and months. Multiple daily phone conversations with them about desired portfolio changes, plus their own world-wide instantaneous information gathering systems and support staffs attempt to keep the MMs from being victimized by their clients. For further protection, the MMs turn to their skills in using the derivative markets and the arbitrage opportunities they provide in the form of price change insurances. The block trade desks of the MM firms are the usual buyers of the insurance, MM proprietary trade desks are the usual sellers. That makes this typically a well-informed, knowledgeable, experienced activity, bounded by the willingness of the clients to transact trade orders at prices that contain the costs of the price insurances. Those negotiations make possible the MM commitments of firm capital to balance that part of volume orders the market otherwise would not accommodate. Implicit in the hedging are expectations of likely possible price change limits, both up and down. Here are details on these ETFs and a comparison with population averages in the format of our daily Top Ten ranking: (click to enlarge) The blue-line average of these 13 ETFs does not compare very favorably with the most favorable 20 stock and ETF current competitors. In particular, please note columns (5) and (6). The prior price drawdowns of nearly -10% are nearly double those of the best-ranked 20. While the ETF upside promise of about +16% beats the 20’s +12%, it appears to be a hollow enticement, since prior forecasts like today’s – in (9) – averaged only +2.5%. The 20 actually bested their current promise. Further, the prior performances of the 20 best were profitable 12 out of each 13 times (92% win odds) compared to only 2 out of 3 (12 of 18 or 67%) for these ETFs. Even the market, in its tracker ETF of SPY did much better at being profitable 85 out of each 100 prior like forecasts. Specific ETF Potentials The two inverse (short-structured) ETFs, ERY [1] and DUG [12] are the least attractive, indicating that their prices already contain ample recognition of likely continued weakness in oil and gas commodity prices. Their prior forecasts at today’s level of balance between upside and downside prospects have produced negative net returns when subjected to our TERMD (Time-Efficient Risk Management Discipline) of portfolio management. All others were at least slightly net profitable. The most attractive energy ETF performers in this set, ERX [5] and DIG [8], fall far short of the 20 best equity competitor averages in terms of payoff performance (9) and win odds (8). When compared to the market average SPY, they have had better price payoffs, and approach its win odds. Conclusion This continues to be a poor time (and prices) for investment in energy ETFs. That does not need to be the case for specific stocks that can separate themselves from their surroundings because of special company, geography, or competitive advantages. Or merely more advantageous stock pricing at the present. All that will be examined in our next review of the market-makers price range outlooks for specific energy stocks in groups as outlined by energy expert Richard Zeits.
WDIV Could Be Fun If Prices Deviate From NAV With Poor Liquidity

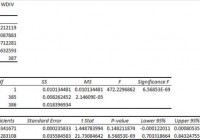
Summary I’m taking a look at WDIV as a candidate for inclusion in my ETF portfolio. Poor liquidity ruins the reliability of statistics and creates significant spreads during trading hours. The correlation to SPY looks low, but I can’t trust it because of the liquidity issues. If an investor is using a tax advantaged account that doesn’t pay commissions on trading the ETF, it could be interesting to play the spreads and deviations from NAV. I’m not assessing any tax impacts. Investors should check their own situation for tax exposure. Investors should be seeking to improve their risk adjusted returns. I’m a big fan of using ETFs to achieve risk adjusted returns relative to the portfolios that normal investors can generate for themselves after trading costs. I’m working on building a new portfolio and will be analyzing several of the ETFs that I am considering for my personal portfolio. One of the funds that I’m considering is the SPDR S&P Global Dividend ETF (NYSEARCA: WDIV ). I’ll be performing a substantial portion of my analysis along the lines of modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. What does WDIV do? WDIV attempts to track the total return (before fees and expenses) of an unnamed index that tracks the stocks of global companies with strong dividends. At least 80% of the assets are invested in those companies, or ADRs that represent those companies. WDIV falls under the category of “World Stock”. Does WDIV provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use the SPDR S&P 500 Trust ETF (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. Therefore, I start my diversification analysis by seeing how it works with SPY. I start with an ANOVA table: (click to enlarge) The correlation is excellent at 74%. I want to see low correlations on my international investments. Extremely low levels of correlation are wonderful for establishing a more stable portfolio. I consider anything under 50% to be extremely low. However, for equity securities an extremely low correlation is frequently only found when there are substantial issues with trading volumes that may distort the statistics. Standard deviation of daily returns (dividend adjusted, measured since Jun e 2013) The standard deviation is very attractive. For WDIV, it is 0.6626%. For SPY, it is 0.6904% for the same period. SPY usually beats other ETFs in this regard, so a lower volatility level is very impressive. Because the ETF has fairly low correlation for equity investments and a low standard deviation of returns, it should do fairly well under modern portfolio theory. Liquidity looks fine Average trading volume is an issue. The average volume is running between 6,500 and 7,000 shares per day. Very low average trading volumes can result in statistics that are substantially less reliable. I will continue with my process for analyzing the ETF, but this is a red flag investors should know about. Within the time period I was looking at, there were only a few days where the change in dividend adjusted close was equal to 0.00%. When we see that the closing price did not change, it is possible that no shares were trading hands that day. If the bid and ask were moving but no shares traded hands, then a change of 0.00% understates the actual volatility and may weaken or strengthen the correlation. Therefore, investors should take the statistics with a grain of salt because they may be slightly more favorable to WDIV than they should be. Mixing it with SPY I also ran comparisons on the standard deviation of daily returns for the portfolio, assuming that the portfolio is combined with the S&P 500. For research, I assumed daily rebalancing because it dramatically simplifies the math. With a 50/50 weighting in a portfolio holding only SPY and WDIV, the standard deviation of daily returns across the entire portfolio is 0.6314%. With 80% in SPY and 20% in WDIV, the standard deviation of the portfolio would have been 0.6567%. If an investor wanted to use WDIV as a supplement to their portfolio, the standard deviation across the portfolio with 95% in SPY and 5% in WDIV would have been 0.6808%. Why I use standard deviation of daily returns I don’t believe historical returns have predictive power for future returns, but I do believe historical values for standard deviations of returns relative to other ETFs have some predictive power on future risks and correlations. Yield & Taxes The distribution yield is 4.19% and the SEC yield is 3.74%. Those are very strong yield figures for an ETF. This ETF could be worth considering for retiring investors. I like to see strong yields for retiring portfolios because I don’t want to touch the principal. By investing in ETFs I’m removing some of the human emotions, such as panic. Higher yields imply lower growth rates (without reinvestment) over the long term, but that is an acceptable trade off in my opinion. I’m not a CPA or CFP, so I’m not assessing any tax impacts. Expense Ratio The ETF is posting an expense ratio of 0.40%. I want diversification, I want stability, and I don’t want to pay for them. I view expense ratios as a very important part of the long-term return picture because I want to hold the ETF for a time period measured in decades. An expense ratio of this level is enough to concern me, but world ETFs are prone to higher expense ratios. Market to NAV The ETF is at a 0.31% premium to NAV (Net Asset Value) currently. Premiums or discounts to NAV can change very quickly so investors should check prior to putting in an order. Generally, I don’t trust deviations from NAV, and I will have a strong resistance to paying a premium to NAV to enter into a position. This ETF has relatively poor liquidity, so investors should also watch out for a large bid/ask spread. At the time of my writing, the spread was 0.25%. I’m not big on crossing that spread, so I’d be one of the people that would use a limit order and wait for the seller to come to me. Due to the fairly low trading volumes and the possibility that the order would be partially filled, I’d either have to set the order to only accept complete fills or only do the trade in accounts that trade the ETF without commissions. For comparison, the spread on SPY right now is less than 0.01%. Largest Holdings The diversification is pretty good, but not incredible. For the expense ratio, I would want more. However, the fund is supposed to be investing in high dividend yielding securities, so the investment universe for the fund may be more limited. (click to enlarge) Conclusion I’m currently screening a large volume of ETFs for my own portfolio. The portfolio I’m building is through Schwab, so I’m able to trade WDIV with no commissions. I have a strong preference for researching ETFs that are free to trade in my account, so most of my research will be on ETFs that fall under the “ETF OneSource” program. The correlation and standard deviation were great, but the potential for statistics to be misleading because of poor trading volumes leaves me concerned that the numbers may not be reliable enough. When I combine risk that the data is flawed, the moderately high expense ratios, and the bid-ask spread, I’m not really blown away by this ETF. It could be an interesting ETF to put on a watch list for the trading price to deviate from NAV and then step into a short-term position through a tax advantaged account that was not paying commissions, but I don’t think I will want to use it as my primary “international exposure” ETF. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis. The analyst holds a diversified portfolio including mutual funds or index funds which may include a small long exposure to the stock.

SPDR S&P 500 ETF: SPY’s 2014 And Fourth-Quarter Performance And Seasonality

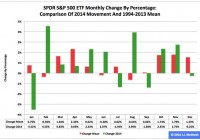
Summary The SPDR S&P 500 ETF ranked No. 1 in 2014 among the three most popular exchange-traded funds based on the S&P 1500’s constituent indexes. Most recently, the ETF’s adjusted closing daily share price last month declined to $205.54 from $206.06, a loss of -$0.52, or -0.25 percent. The last time the ETF had a negative return in the seasonally strong month of December was 2007. The SPDR S&P 500 ETF (NYSEARCA: SPY ) ranked first by return during 2014 among the three most popular ETFs based on the S&P 1500’s constituent indexes, which also encompass the SPDR S&P MidCap 400 ETF (NYSEARCA: MDY ) and the iShares Core S&P Small-Cap ETF (NYSEARCA: IJR ). SPY advanced to $205.54 from $181.15, a gain of $24.39, or 13.46 percent, in terms of adjusted closing daily share prices. Neither seasonality nor U.S Federal Reserve policy appears likely to be supportive of SPY at its current elevated level over the coming quarter. The Federal Open Market Committee announced the end of asset purchases under its third formal quantitative-easing program Oct. 29 and may announce the beginning of its next round of federal-funds-rate increases April 29. Figure 1: SPY Monthly Change, 2014 Vs. 1994-2013 Mean (click to enlarge) Source: This J.J.’s Risky Business chart is based on analyses of adjusted closing monthly share prices at Yahoo Finance . SPY behaved better in 2014 than it did over its initial 20 full years of existence based on the monthly means calculated by employing data associated with that historical time frame (Figure 1). The same data set shows the average year’s strongest quarter was the fourth, with an absolutely large positive return, and its weakest quarter was the third, with an absolutely small positive return. The last time the ETF had a negative return in the seasonally strong month of December was 2007. Figure 2: SPY Monthly Change, 2014 Vs. 1994-2013 Median (click to enlarge) Source: This J.J.’s Risky Business chart is based on analyses of adjusted closing monthly share prices at Yahoo Finance. SPY behaved worse in 2014 than it did over its initial 20 full years of existence based on the monthly medians calculated by using data associated with that historical time frame (Figure 2). The same data set shows the average year’s strongest quarter was the fourth, with an absolutely large positive return, and its weakest quarter was the third, with a relatively small positive return. Last year, the ETF performed best in the second quarter and worst in the third quarter. Disclaimer: The opinions expressed herein by the author do not constitute an investment recommendation, and they are unsuitable for employment in the making of investment decisions. The opinions expressed herein address only certain aspects of potential investment in any securities and cannot substitute for comprehensive investment analysis. The opinions expressed herein are based on an incomplete set of information, illustrative in nature, and limited in scope. In addition, the opinions expressed herein reflect the author’s best judgment as of the date of publication, and they are subject to change without notice. Now that you’ve read this, are you Bullish or Bearish on ? Bullish Bearish Sentiment on ( ) Thanks for sharing your thoughts. Why are you ? Submit & View Results Skip to results » Share this article with a colleague