Tag Archives: function

The ‘Efficiency’ Of The Market Doesn’t Matter To Smart Investors
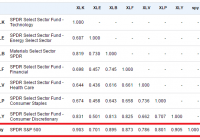
The huge growth in index funds has caused some investors to debate the merits of the market’s “efficiency” and whether index funds would make the markets less efficient. The basic thinking is that if everyone starts buying index funds then that could create more opportunities for stock pickers who are able to go against the grain and pick the stocks that have been unjustifiably correlated to the actions of the overall index. This whole debate confuses why correlations are rising in the first place. Correlations aren’t rising because index funds are becoming more prevalent. Index funds are becoming more prevalent because the performance of the economy is becoming increasingly correlated. If you look at any sector of the S&P 500, you’ll find rising correlations over the course of the last 50 years. The average 10-year correlation of all the sectors of the S&P 500 is about 83.5%: (10-Year Correlation of various sectors) This isn’t happening because index funds are becoming more popular. It’s happening because US corporations are becoming increasingly interconnected. Public companies are becoming multi-national and multi-industry companies whose performance depends increasingly on the way the macroeconomy works. If we look at the underlying Earnings Per Share of these same industries, we find equally strong correlations in their profit growth over time. Of course, high correlations doesn’t mean there won’t be uncorrelated entities whose prices get irrationally whipsawed by the aggregate market performance. But it does mean that it is becoming increasingly difficult to find entities who aren’t dependent on the performance of the broader economy. Finding truly uncorrelated companies is not as easy today as it might have been back in the early 1900s when the broader economy was much more fragmented. Paul Samuelson always argued that the markets were micro efficient, but not macro efficient. Indeed, the whole concept of market “efficiency” is becoming increasingly irrelevant in a world where entire economies are becoming so highly correlated. But this doesn’t change the importance of understanding the discussion and its impact. At the aggregate level, we have all become “asset pickers.” The distinction between “active” and “passive” investors is largely irrelevant in a world where we all now pick baskets of assets inside the global aggregate. And when one deviates from global cap weighting (roughly the Global Financial Asset Portfolio) you are engaging in a form of asset picking that makes you no different than a stock picker. You are declaring that you can generate a better risk adjusted return than the global aggregate. Indexing has become the new stock picking. Instead of picking 25 stocks in an index, we now pick baskets of index funds inside a global aggregate. The idea of “market efficiency” was never very useful to begin with however because it is constructed around a gigantic political strawman. The EMH is essentially a political construct that argues that discretionary intervention is useless because “the market” is smarter than everyone else. It is a political argument against discretionary intervention that was constructed to create a theory of finance that was consistent with an anti government economic theory (Monetarism primarily). In essence, you can’t “beat the market” because the market is so smart. This is silly though. The market will generate the aggregate market return and your real, real return will be the market return minus the rate of inflation, taxes and fees. Taxes and fees alone will reduce the aggregate return by over 35% (if we assume a 10% aggregate return, 1% fees and 25% tax rate). No one will consistently beat “the market” aside from a few lucky outliers. The math just doesn’t work. And the index we are comparing ourselves to is a completely fictitious benchmark because the average real, real return is lower than the pre-tax and pre-fee benchmark to begin with. But the EMH defenders have misconstrued this entire debate to promote a political position constructed by anti government economists at the Chicago School of Economics. Imagine, for instance, that, for the purpose of record keeping, at the end of each NBA basketball game, the NBA reduced the average score of 100 points by 25%, and then imagine that the coaches reduced the score by another 10%. What the EMH defenders have done is argued that the score of 100 means that the teams are all terrible because they cannot, on average beat this “benchmark.” There will be outlier teams who sometimes score more than 100 points, but on average these “professional” teams will underperform. EMH defenders have used this strawman to argue that “active” investors are all terrible. It’s a completely useless construct that does nothing more than misconstrue the entire premise of the discussion. Of course, none of this means that high fees and overly active trading are good. After all, when one engages in such activities they only increase the size of the friction, which reduces returns in the first place. But the debate about EMH and “active” vs. “passive” has been blurred by a useless discussion about how “efficient” the market is. The reality is that we are all active investors to some degree. All indexers have to pick their asset allocations and the funds they will use. All indexers time their entry/exit points, their rebalancing points, their “tilts,” etc. The smarter indexer tries to capture much of the broad market gain while reducing their tax and fee burden. But that has nothing to do with whether the market has become “efficient” or whether some degree of “active” management is “smart” or “stupid.” Samuelson was right – the market is micro efficient and macro inefficient. And as the market has become increasingly macro oriented the discussion about the “efficiency” of the market has become increasingly useless.
Safe Withdrawal Rates For Retirement Income Portfolios Using Fidelity Select Mutual Funds

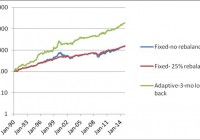
Summary Robust investment portfolios with large withdrawal rates can be constructed with Fidelity select mutual funds. From January 1990 to December 2014, a Fidelity portfolio with fixed allocation allowed a safe 6% annual withdrawal rate and achieved 6.19% annual increase of the capital. Same portfolio with rebalancing at 25% deviation from the target allowed a safe 6% annual withdrawal rate and achieved 7.78% compound annual increase of the capital. Radically better performance is achieved using adaptive asset allocation. Same portfolio allowed a safe 6% annual withdrawal rate and 22.05% annual increase of the capital. The Chicago South Suburban Investment Club has been experimenting with a monthly asset rotation strategy applied to a hypothetic IRA account using five Fidelity mutual funds. On the last trading day of each month, the funds are ranked by the previous 3-month return. All equity is invested in the fund with the highest return, as long as that return is positive. If all the assets had negative returns over the previous 3 months, then all equity is moved into CASH. The five mutual funds considered for investment are the following: Fidelity GNMA (MUTF: FGMNX ) Fidelity Select Multimedia (MUTF: FBMPX ) Fidelity Select Chemicals (MUTF: FSCHX ) Fidelity Select Electronics (MUTF: FSELX ) Fidelity Select Health Care (MUTF: FSHCX ) This experiment has been ongoing since July 2014. It extends over a period of 5 months. Within this time interval, the system had been invested 4 months in FSPHX, 1 month in FSELX, and current month in FLBIX. The results are showed in the table below. Table 1. Momentum allocation portfolio August 2014 to January 2015 Month AUG SEP OCT NOV DEC JAN ETF FSPHX FSPHX FSPHX FSPHX FSELX FLBIX BUY 206.52 218.7 218.92 228.7 81.43 13.32 SELL 218.7 218.92 228.7 236.08 84.78 RETURN 5.90 0.10 4.47 3.23 4.11 EQUITY 100.00 105.90 106.00 110.74 114.31 119.02 In this article, three different strategies will be considered: (1) Portfolio is initially invested 50% in the bond fund , and 12.5% each in the four equity funds without rebalancing. (2) Portfolio is initially invested 50% in the bond fund , and 12.5% each in the four equity funds but is rebalanced when the allocation to any fund deviates by 25% from its target. (3) Portfolio is at all times invested 100% in only one fund. The switching, if necessary, is done monthly at closing of the last trading day of the month. All money is invested in the fund with the highest return over the previous 3 months. The data for the study were downloaded from Yahoo Finance on the Historical Prices menu for the five tickers, FGMNX, FBMPX, FSCHX, FSELX, FSPHX. We use the monthly price data from January 1990 to December 2014, adjusted for dividend payments. The purpose of this exercise is to develop a robust strategy for income generation in retirement. The paper is made up of two parts. In part I, we examine the performance of portfolios without any income withdrawal. In part II, we examine the performance of portfolios when income is extracted periodically from the account. Part I : Portfolios without withdrawals In table 2 we show the results of the portfolios managed for 25 years, from January 1990 to December 2014. Table 2. Portfolios without withdrawals 1990 – 2014. Strategy Total return% CAGR% Number trades MaxDD% Fixed-no rebalance 1,463 11.62 0 -49.21 Fixed-25% rebalance 1,395 11.43 28 -22.55 Adaptive 18,015 23.35 126 -33.11 The time evolution of the equity in the portfolios is shown in Figure 1. (click to enlarge) Figure 1. Equities of portfolios without withdrawals. Source: This chart is based on EXCEL calculations using the adjusted monthly closing share prices of securities. Notice that the prices are shown in a logarithmic scale. That allows a better differentiation between the curves. It is apparent that the rate of increase of the adaptive portfolio is very stable and is substantially greater than the rate of the fixed allocation portfolios. One can also see that rebalancing of the fixed allocation portfolio makes its rate of increase much more stable than that of the portfolio without rebalancing. Part II: : Portfolios with withdrawals Assume that we have $1,000,000 to invest for income in retirement. In table 2 we show the results of the portfolios managed for 10 years, from January 2005 to December 2014. Money was withdrawn monthly at a 6% annual rate of the initial investment plus a 2% inflation adjustment. Over the 10 years from January 2005 to December 2014, a total of $664,704 was withdrawn. Table 3. Portfolios with 6% annual withdrawal rate 2005 – 2014. Strategy Total return% CAGR% Number trades MaxDD% Fixed-no rebalance 122.63 2.06 0 -28.82 Fixed-25% rebalance 125.76 2.32 5 -30.11 Adaptive 278.92 10.8 56 -15.92 The time evolution of the equity in the portfolios is shown in Figure 2. (click to enlarge) Figure 2. Equities of portfolios with 6% annual withdrawal rates. Source: This chart is based on EXCEL calculations using the adjusted monthly closing share prices of securities. Conclusion The adaptive allocation algorithm performed substantially better than the fixed allocation algorithms. The fixed allocation strategies allow a safe withdrawal rate of 6% at any time horizon between 1990 and 2014, without a substantial decrease of capital. The adaptive allocation algorithm allows a 6% annual withdrawal rate while assuring a substantial increase of capital. In fact, the momentum-based adaptive allocation strategy allows a safe 10% annual rate of withdrawal without any decrease of capital.

The Best Gold Fund To Own

Summary Gold miners have unique situations due to differing geographic, regulatory and currency risk, as well as different ore quality. Gold mining index ETFs are good for trading and short-term exposure. Long-term investors who plan on holding longer than three months should consider TGLDX instead. Investors have flocked to index funds and ETFs due to their low cost, tax efficiency and transparency. The general rise of indexing has helped ETFs grow rapidly, taking market share from mutual funds, particularly actively managed funds. However, there are clear-cut cases of active managers outperforming their indexed competition. One example is the gold mining sector. Gold Funds Since the inception of the Market Vectors Gold Miners ETF (NYSEARCA: GDX ) in 2006, the fund has seen an incredible inflow of funds, to $7.1 billion as of January 23. The small cap edition, Market Vectors Junior Gold Miners ETF (NYSEARCA: GDXJ ) has amassed $2 billion in assets since its inception in late 2009. The actively managed the Tocqueville Gold Fund No Load (MUTF: TGLDX ), which was created back in 1998, has attracted only $1.3 billion in assets. For short-term investors, the ETFs make sense due to TGLDX’s short-term trading fee of 2 percent. The high volume in GDX and GDXJ indicates traders are using the ETFs to speculate on the volatile sector, even after a long bear market in mining shares. However, long-term investors may also be holding shares. Those investors are placing their confidence in the market cap-weighted indexing strategy, but the gold mining industry is one where active management can pay off. The saying “A mine is a hole in the ground with a liar at the top” is attributed to Mark Twain, and it gets to the heart of the difficulty in evaluating mining companies. The track record of TGLDX shows that this assumption is correct. The chart below is a price ratio of TGLDX to GDX – a rising line shows outperformance by TGLDX. (click to enlarge) Since its inception in 2006, TGLDX has generally outperformed GDX. Aside from an 18-month period from summer 2007 to 2009, TGLDX hasn’t spent much time trailing GDX. The total return since May 16, 2006, the inception of GDX, shows that TGLDX has built up a considerable lead: a loss of 4.46 percent versus a decline of 38.13 percent in GDX. (click to enlarge) TGLDX does have an advantage over GDX in that manager John Hathaway can choose to hold more small cap miners than the market cap-weighted index. However, TGLDX also beat GDXJ since the inception of that ETF, a loss of 33.12 percent versus a drop of 68.07 percent for GDXJ. This indicates stock selection is playing a role in TGLDX’s outperformance. (click to enlarge) The strong performance in TGLDX has more than made up for its higher expense ratio of 1.36 percent, versus 0.53 percent for GDX and 0.58 percent for GDXJ. TGLDX Recognized by Lipper as the Best Fund in the Precious Metals category during the last five years, the Tocqueville Gold Fund is co-managed by John Hathaway and Doug Groh. Originally created in 1998 by Mr. Hathaway, the fund was initially designed to take advantage of the negative psychology that surrounded the gold market at that time. The no-load fund is based on a contrarian value investment philosophy, and seeks long-term capital appreciation. The minimum investment is $1000 ($250 IRA). In addition to the 1.36 percent expense ratio, there is a 2 percent fee on shares held less than 90 days. This is not a fund for traders, but for long-term investors who want exposure to gold mining shares. Mr. Hathaway, senior managing director at Tocqueville Asset Management, is the portfolio manager for the Tocqueville Gold Fund. In 1986, he founded Hudson Capital Advisors and managed the firm until 1997, when he joined Tocqueville. Mr. Hathaway earned his B.A. From Harvard University, M.B.A. from the University of Virginia and began his career in 1970 employed as an equity analyst with Spencer Trask & Co. As portfolio manager for the Tocqueville Gold Fund, he searches for companies in the gold sector that have excellent management teams and assets that provide the most value independent of the price of gold. Researchers for the fund follow the entire gold resource and mining industry. Investing in the gold sector from 1998 to 2011 produced record returns. Since then, the sector has been out of favor and has taken quite a hit. Spot gold traded at a high above $1,900 an ounce in 2011, and finally found a bottom below $1,200 an ounce in 2014. Mr. Hathaway believes that the slump may be close to reversing for gold investors, and holds that a bottom in gold is being formed. Mr. Hathaway believes that the price of spot gold has been discounted to a point where most of the negative headlines are priced in. At some point, rates will need to be taken higher, and this could prove to be very disruptive to the markets. Back in November, he saw gold rallying along with the U.S. dollar as a sign of alternative reserve currency risk . The recent performance of gold in euros shows he was on target with this view. (click to enlarge) Finding Winners Aside from a 12 percent position in physical gold, the $1.3 billion fund is mostly invested in equities related to precious metal mining. While this sector can be challenging, Mr. Hathaway has a knack for discovering hidden gems involved with exploration and building up production. Gold mining is a capital-intensive business that takes many years to develop and will see many different issues over those years. An obvious change is in the price of gold, but companies in the gold sector must also deal with change in governments, currency devaluations, central bank policy and both local and global economic conditions. The fund takes a diversified approach and invests in all types of business models, ranging from royalty companies to businesses involved only in exploration. Speaking about the fund’s strategy, Hathaway said: “Our strategy for the Fund has been to find companies that are adding value even in a low gold price environment. As a result, we tend to focus on smaller companies and steer clear of larger companies that have either experienced operational challenges or have lower levels of reserves in their portfolio. We believe having smaller companies in the portfolio has been an important contributor to the Fund’s outperformance relative to its benchmark and the Morningstar Equity Precious Metals Funds Category over time.” The top five holdings behind the 12 percent holding in physical gold are Royal Gold (NASDAQ: RGLD ), Franco-Nevada (NYSE: FNV ), Eldorado Gold (NYSE: EGO ), Goldcorp (NYSE: GG ) and Agnico Eagle Mines (NYSE: AEM ). Allocations in the top ten range from 6.62 percent in Royal Gold to 3.19 percent in Yamana Gold (NYSE: AUY ). Recent underperformance by Eldorado and Yamana have dinged the fund in 2015. The fund is up 11.06 percent through January 23, versus a 15.42 percent return for GDX. Royalty companies play a major role in the fund, with about 12 percent of its assets invested in two of the major players: Royal Gold and Franco-Nevada. The business model that royalty companies are based on has become attractive to gold investors. Gold royalty companies help finance mining construction and receive royalty payments in return. By investing this way, they avoid some of the hazards and costs of exploration or operations. The stream of payments that gold royalty companies receive are based on future sales, and are not as sensitive to spot gold price fluctuations. Mr. Hathaway recognized the inherent value of these type of investments early on and included them in TGLDX. Gold’s price decline in the last 3 years has been devastating for many gold mining companies. While some are specialized in exploration, others have expertise in development. Many in the niche are having to rethink their business models and capital spending plans in order to become profitable. This has led to an increase of mergers and acquisitions in the industry, and presents the fund with the ability to invest in companies that may be targeted acquisitions. In fact, the fund performed well in 2014, beating the category by more than 6 percent, by holding a large position in Osisko Mining Corp. ( OTC:OKSKF ). It became a top-weighted position in the fund until going through its merger . Another possible acquisition target that has been placed in the fund’s portfolio is based in Ontario, Canada. Detour Gold Corp. ( OTCPK:DRGDF ) is expected to become the largest operating gold mine in Canada, with a possible lifespan of 21 years. With Osisko Mining being acquired, investors began looking for the next target for a merger. Mr. Hathaway believes there will be more opportunities such as these, and continues to scour the landscape for possibilities. With around 17 years at the helm of the Tocqueville Gold Fund, Mr. Hathaway has his pulse on the gold sector and possesses a management style that’s been beneficial to its investors. TGLDX has beaten the returns of popular gold ETFs, and investors looking to establish a long-term position in the sector should look to the fund. Outlook for Gold Mining Shares In many foreign currencies, gold is experiencing a strong rally, trading at a 12-18 month high, depending on the currency. Gold is near its all-time high in yen, and at all-time highs in currencies that crumbled last year, such as the Russian ruble. If gold remains an alternative to the U.S. dollar as a reserve asset/safe haven currency, the price could remain elevated even amid a U.S. dollar bull market , since such a bull market will likely be accompanied by a series of financial or currency crises in emerging markets due to the run-up in dollar-denominated debt over the past several years. Falling energy prices, along with other costs for mines located abroad could help miners increase non-dollar profits. For example, in January alone, gold went from $1400 to $1600 in Canadian dollars. A 20 percent combination move in gold and Canadian dollar depreciation would lift the metal to a new all-time high in Canadian dollars. A pullback in gold and rebound in foreign currencies is long overdue, though, at least in the short run. Miners used the recent jump in prices to raise cash as well. The industry diluted shareholders to the tune of more than $800 million in January 2015 alone. The share issuance sent shares of the affected miners lower, and until business conditions for the sector improve markedly, further share issuance is possible. The best-case scenario for mining shares amid a U.S. dollar bull market (leaving aside a new bull market in the U.S. dollar price of gold) is if foreign demand for hard money keeps the price of gold level or even increases it slightly in U.S. dollars. The price in foreign currency could rise substantially as foreign currencies devalue versus the dollar and gold, and since mining shares are leveraged to the price of gold, their earnings could rise significantly. If, instead, the gold price falls, high-cost miners will struggle to remain profitable and the bear market for mining shares will continue.