Tag Archives: management

EQT Corporation: Understanding Marcellus Economics
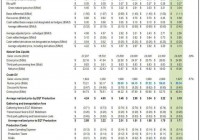
Summary The Marcellus macro environment remains challenging, even for low-cost producers with strong marketing portfolios. Using the EQT example, the article lays out various components of the “buildup” between the wellhead price in the Marcellus and the Henry Hub price. The analysis lends support to the thesis that the current depressed natural gas price environment is not sustainable. IMPORTANT NOTE: This article is not an investment recommendation or research report. It is not to be relied upon when making investment decisions – investors should conduct their own comprehensive research. Please read the Disclaimer at the end of this article. EQT Corporation (NYSE: EQT ) is not immune to the challenges the current deeply depressed natural gas price environment presents for North American natural gas producers. In the Marcellus and Utica, the problem is exacerbated by the wide local differentials that have persisted at many pricing points, often diminishing the area’s geologic and economic advantage over other supply sources. Thanks to its extensive marketing portfolio, which includes firm transportation agreements and basis and Henry Hub hedges, EQT has remained relatively well protected against the extreme weakness of natural gas prices within the Marcellus/Utica area. By settling its basis hedges, selling excess transportation capacity and moving some of its gas to more attractive pricing points, EQT has been able to “recover” a significant portion of the local basis differential. Still, in 2014, the company effectively sold its natural gas at a discount to Henry Hub. In 2015, EQT’s price realizations will continue to benefit from such basis recoveries, as well as Nymex hedges and price uplift from NGLs. Still, the combination of depressed Nymex prices, deep local differentials and weak oil and NGL pricing may take a heavy toll on the company’s drilling economics this year. Having said that, the extreme weakness of natural gas prices cannot be sustained for long. Understanding Marcellus Price Realizations Understanding price realization build-ups for Marcellus natural gas producers can be a tedious and confusing task. Reporting formats differ from company to company, and there is no uniform convention that operators would use when presenting data. The following table may be helpful in understanding production economics in the Marcellus using EQT as example. The table shows historical price realization reconciliation for Q4 2014 and full-year 2014, as reported by the company, as well as my illustrative scenario for 2015. (click to enlarge) (Source: Zeits Energy Analytics, February 2014) One could think of the net price realization as a “build-up” that takes the Henry Hub price as a starting point, with several add-ons and deducts: The “Btu uplift” line in the Natural Gas section of the table reflects the fact that, on average, EQT’s natural gas sold has a higher Btu content than the NYMEX specification, primarily as a result of ethane rejection. Because of that higher Btu value, the company realizes a higher price per Mcf. For example, in Q4 2014, EQT realized a Btu content premium for its natural gas of $0.39 per Mcf. The “average differential” line includes: the impact of local basis (the differential between Henry Hub price and the average price that EQT would realize by selling its natural gas at local trading hubs); recoveries received from selling some of the company’s natural gas into higher-priced markets and recoveries from the resale of unused takeaway capacity; and the impact of cash-settled basis swaps. In Q4 2014, EQT was able to “recover” a portion of the basis differential equal to $0.88 per Mcf. In addition, it gained another $0.30 per Mcf via basis swaps, for a total of $1.18 per Mcf. As a result, the company’s Q4 2014 price received per processed Mcf, before hedges, was effectively higher than the Nymex price ($4.08 per Mcf versus $4.01 per MMBtu). The company’s natural gas hedges and other price derivative contracts also contribute to (or deduct from) the net price realization. In Q4 2014, EQT realized a combined gain of $0.14 per Mcf from this category of contracts. Crude oil and NGL components of the production stream provide a further uplift to the average price realization. On an equivalent basis, including hedges, EQT realized $4.24 per Mcf of equivalent production in Q4 2014. In order to deliver its natural gas from the wellhead to various sales points, EQT must pay gathering and transmission fees (in some cases, under take-or-pay contracts). In Q4 2014, the company’s combined gathering and transmission fees per Mcf averaged $1.36 per Mcf. Much of this amount ($0.91 per Mcf) was paid to the sister company EQT Midstream. Adding all these components together, EQT Production’s Q4 2014 net price realization was $2.88 per Mcfe. EQT is a low-cost operator. Its total cash operating cost (including LOE, production taxes and SG&A) in Q4 2014 was $0.47/MMcfe. This cascade leads to a cash netback to EQT Production in Q4 2014 of $2.41 per Mcfe. The above layout helps to single out key factors that drive economic margins (for EQT Production, in this case) and may help to address some common misconceptions. Henry Hub is not the most indicative benchmark for Marcellus operators. Many pricing points in the Consuming East region are characterized by strong seasonality, and may yield high premiums during peak seasons and trade at discounts during shoulder seasons. Access to premium pricing points requires transportation contracts. As a result, many Marcellus producers have diversified and highly complex portfolios of marketing arrangements. Transportation contracts and basis swaps are integral components of such portfolios. Calculating the net price realization on a quarter-to-quarter basis may be a difficult task for outsiders. “Macro hedges” (typically using Nymex) are perhaps the only component of the net price realization that can be completely disintegrated from the marketing portfolio. Its impact can be calculated separately. Gathering fees and transportation fees are the largest (and in many cases fixed for decades) cost components for the majority of natural gas producers in the Marcellus and Utica area. The very wide local basis differential for volumes not covered by transportation agreements is, in essence, a spot transportation cost . Field operating costs (LOE, production taxes and field G&A) are the smallest cost components. This cost category often reflects the operator’s position in the field’s exploitation life cycle and the liquids content in the production stream: operators that are still delineating their acreage and operate in the rich and super-rich windows will tend to have higher field operating costs. The price uplift from NGLs may be not as significant as sometimes portrayed due to the very high third-party processing fees that often apply. EQT’s 2015 Cash Flow May See Strong Contraction Using the current Nymex futures strip for 2015 and making certain assumptions, I estimate that even after giving credit to EQT’s hedges, the company’s cash netback per Mcfe will decline by approximately one-half year-on-year in 2015 to ~$1.24 per Mcfe. The company will be able to capture additional economic benefits via its ownership of EQT Midstream. However, this illustrative calculation shows that in the absence of a strong improvement in the overall natural gas price environment, new drilling would be marginally economic even for a low-cost operator like EQT. Using the price realization model outlined above, I derive 2015 EBITDA for EQT Production of ~$750 million, an almost two-fold reduction from 2014, despite the expected meaningful growth in production volumes. (click to enlarge) (Source: Zeits Energy Analytics, February 2014) On a consolidated level, the decline in the company’s cash flow will be partially mitigated by the resilience of its midstream business: EQT is experiencing strong volumetric growth, and its operating margins are largely protected by the long-term contracts. Still, the company may have to utilize most of the $950 million cash balance it had at the end of 2014 to fund its current spending plan. Despite the significant announced reduction in the number of new wells drilled, EQT Production is still expected to spend substantially in excess of its cash flow. The company’s 2015 drilling and completion budget is currently set at $1.85 billion, a slight uptick from $1.7 billion in 2014. The plan envisions an average of 12 operated rigs run throughout the year (8 deep drilling rigs running and 4 spudder rigs), down from 15 rigs currently. A significant portion of the 2015 capex is designated for completing wells that have already been spud. As of year-end 2014, EQT had 191 wells spud but not yet on production, including 23 wells that had been already completed but were not on-line yet. The company’s guidance of 575-600 Bcfe total production in 2015 implies continued strong growth of ~24% year-on-year (slide below). (click to enlarge) (Source: EQT Corporation, February 2015) However, as a result of the extremely weak commodity prices, this growth will come at the price of a significant outspend relative to the internally generated cash flow. Over half of EQT’s natural gas volumes are protected with Nymex hedges with attractive prices (the graph below). In the absence of such hedges, the outspend in 2015 would be even more pronounced. (click to enlarge) (Source: EQT Corporation, February 2015) Drilling Economics The review of EQT’s drilling economics in the Marcellus indicates that the current natural gas price environment is hardly sustainable for long. The following two slides from the company’s latest presentation suggest that even in its most prolific and most economic areas, a realized price of $2.80-2.90 per Mcf is required to generate a competitive drilling return at the well level (which I define as at least 20%). Assuming that the “realized price” measure on the slides corresponds to the “Average realized price by EQT Production” (which was $4.24 in Q4 2014), the company’s upstream operation was highly economic in 2014. In 2015, the company will continue to generate compelling returns on its new drilling program. However, these returns will be driven by short-term financial macro hedges (Nymex Henry Hub hedges). In the absence of such financial hedges, the company’s drilling would be marginally economic or uneconomic, assuming no improvement in natural gas prices from their current levels. Given that the degree of hedge coverage throughout the industry will decline in 2016 relative to 2015, natural gas prices would have to recover or supply will decline due to significant new drilling curtailments. (click to enlarge) (click to enlarge) (Source: EQT Corporation, February 2015) Disclaimer: Opinions expressed herein by the author are not an investment recommendation and are not meant to be relied upon in investment decisions. The author is not acting in an investment, tax, legal or any other advisory capacity. This is not an investment research report. The author’s opinions expressed herein address only select aspects of potential investment in securities of the companies mentioned and cannot be a substitute for comprehensive investment analysis. Any analysis presented herein is illustrative in nature, limited in scope, based on an incomplete set of information, and has limitations to its accuracy. The author recommends that potential and existing investors conduct thorough investment research of their own, including detailed review of the companies’ SEC filings, and consult a qualified investment advisor. The information upon which this material is based was obtained from sources believed to be reliable, but has not been independently verified. Therefore, the author cannot guarantee its accuracy. Any opinions or estimates constitute the author’s best judgment as of the date of publication, and are subject to change without notice. The author explicitly disclaims any liability that may arise from the use of this material. Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article.
CVY Brings Equities And Bonds To Create A Balanced Portfolio

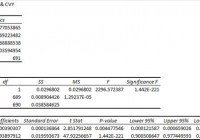
Summary I’m taking a look at CVY as a candidate for inclusion in my ETF portfolio. I like the idea behind the ETF, but I’m not sold on using it over the portfolios I can create myself. The yields on the ETF are extremely high which may make it more appealing for retiring investors seeking income without touching their portfolios. The overall risk level isn’t bad at all, though the returns have been fairly moderate through my testing period. Investors should be seeking to improve their risk adjusted returns. I’m a big fan of using ETFs to achieve the risk adjusted returns relative to the portfolios that a normal investor can generate for themselves after trading costs. I’m working on building a new portfolio and I’m going to be analyzing several of the ETFs that I am considering for my personal portfolio. A substantial portion of my analysis will use modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. In this article I’m reviewing the Guggenheim Multi-Asset Income ETF (NYSEARCA: CVY ). What does CVY do? CVY attempts to track the investment results of an index Zack’s Multi-Asset Income Index. The ETF falls under the category of “Large Value.” Does CVY provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use the SPDR S&P 500 Trust ETF (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. Therefore, I start my diversification analysis by seeing how it works with SPY. I start with an ANOVA table: (click to enlarge) The correlation is about 88%, which is low enough that I’m expecting to see some diversification benefits, but higher than I would like to see for having a unique tracking index. Standard deviation of daily returns (dividend adjusted, measured since January 2012) The standard deviation is going to make a stronger case for investing in CVY. For the period I’ve chosen, the standard deviation of daily returns was .698 %. For SPY, it was 0.748% over the same period. This may be a benefit of the mixed assets that the ETF is holding. Mixing it with SPY I also run comparison on the standard deviation of daily returns for the portfolio assuming that the portfolio is combined with the S&P 500. For research, I assume daily rebalancing because it dramatically simplifies the math. With a 50/50 weighting in a portfolio holding only SPY and CVY, the standard deviation of daily returns across the entire portfolio is 0.701%. The risk level on the portfolio drops relative to only holding SPY because of both the lower deviation from CVY and the correlation. Based solely on this information, it would appear an investor thinking about going all in on CVY could put about half in SPY and retain a similar risk level as long as the risk is measured in the daily volatility. If the position in SPY is raised to 80% while CVY is used at 20% the standard deviation of daily returns increases to .724%. At 5%, the standard deviation of the portfolio would have been 0.741%. If an investor was basing their decision solely on risk level, there could be significant incentives to using a large position in a relatively stable ETF like CVY. However, CVY has substantially underperformed SPY in the period, and I would expect that to be a long term trend because of the less aggressive portfolio that CVY is holding. Why I use standard deviation of daily returns I don’t believe historical returns have predictive power for future returns, but I do believe historical values for standard deviations of returns relative to other ETFs have some predictive power on future risks and correlations. While poor liquidity could impact the reliability of statistics, the ETF had 0 days with no trading volume, so price movements should be recorded as they happened. The average volume is currently around 330,000 shares per day. Yield & Taxes The distribution yield is 6.40%. It is a fairly massive yield, which may be an attractive factor for retirees hoping to live off the distributions. The high distributions will limit the growth rate of the investment in the fund, but for retirees that are concerned about overreacting to movements in the market, a high distribution ETF with lower volatility makes sense. Expense Ratio The ETF is posting .84% for a net expense ratio and .89% for the gross ratio, which is higher than I’d like to see. Unfortunately, most ETFs have expense ratios higher than I’d like to see. There may be some legitimate reasons for a high expense ratio, but I find ETFs with lower expense ratios to be substantially more attractive. One of the reasons I’m overhauling my portfolio is to get away from funds that have higher expense ratios. Market to NAV The ETF is trading at a .18% discount to NAV currently. I think any ETF is significantly less attractive when it trades above NAV. The discount looks very nice, but the discount is also less than one fourth of the annual expense ratio. In that context, the discount becomes less attractive as a feature of total return for a long term investor. Largest Holdings The diversification within the holdings is substantial. Due to the combination of equities and other funds included in the profile, I’ve prepared two charts for the holdings. The first shows the equity holdings and the second shows the other funds. (click to enlarge) (click to enlarge) Investing in the ETF is largely relying on modern portfolio theory. Making an investment requires a belief that markets are at least somewhat efficient so that the companies within the portfolio will be reasonably priced. Conclusion I love the idea of a diversified ETF that can deliver everything investors are seeking within a single ETF. However, I’d rather go with SPY (or an equivalent) and just eliminate the bond position entirely if I had to pick only one ETF. The lower standard deviation is great, but I think I can reach that point by composing a portfolio with individual selections of ETFs. The portfolio’s expense ratio can be justified, at least to some extent, by the excellent internal diversification and the very high turnover ratio. That turnover ratio is currently listed at 180%. Even though I don’t like high turnover ratios, I recognize that they do create more costs in running the ETF. I’m looking for a simple and stable ETF. While this one offers an appealing combination of lower standard deviation and moderate correlation, I don’t feel that the selection represents a superior position to what I can create. That’s the problem in a nutshell. The ETF did a solid job of diversifying, but it doesn’t seem to be a suitable replacement for an entire portfolio compared with just holding something like SPY. If an investor intends to hold several ETFs rather than one, then they can build the portfolio to their exact risk specifications. This ETF may be a great fit for any investors that want the exact risk factors the ETF has selected. The large yields and strong volumes may make the ETF much more appealing for retiring investors seeking strong yields for current income. For me, those benefits simply aren’t enough. Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis. The analyst holds a diversified portfolio including mutual funds or index funds which may include a small long exposure to the stock.

The Weakness In The Natural Gas Market Persists

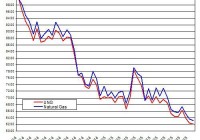
Summary The price of UNG kept coming down last week. The low extraction from storage is related to the warmer-than-normal weather. The recent rally in oil didn’t bring UNG back up. The recent recovery in the oil market didn’t provide any back-wind for The United States Natural Gas ETF, LP (NYSEARCA: UNG ) that kept coming down in the past week. The Energy Information Administration reported another lower-than-anticipated withdrawal from storage. (Data Source: EIA, Google Finance) The chart above presents the normalized prices of natural gas and UNG since the end of November 2014 till date – over this time frame, UNG fell by 38% and natural gas by almost 37%. This modest gap is due to roll decay attributed to the contango in futures markets. For now, the markets are still in contango, which means this gap between UNG and natural gas prices is likely to further widen in the coming months. But this also suggests that the market expects natural gas prices to start picking up again in the coming months. The EIA reported another lower-than-expected extraction from storage of 115 Bcf. In comparison, the extraction last year was 270 Bcf and the 5-year average was 165 Bcf (as a side note: these comparisons are only intended to provide crude base lines – after all, they also entail a lot of noise (as is the case in any weekly comparison), and as such, we should put an asterisk next to these base lines). The ongoing lower-than-expected extraction from storage may have rendered another blow to UNG this week. Most of the shifts in storage this time of the year are related to changes in weather. The relation between the changes in storage compared to the 5-year average and the shifts in temperatures from normal has remained strong this winter – the linear correlation is still at 0.74, which means the R-square is around 54% (this result in based on certain assumptions, including linearity and normality – two assumptions that might not hold up under scrutiny). This result only tends to show that the ongoing warmer-than-normal winter, on a national level, has kept the extraction from storage lower than normal for this extraction season. On top of this, the current storage level is around 24% higher than only 1.2% below the 5-year average. So the lower extraction, along with relatively normal storage levels has been enough to bring down the price of UNG to its current low levels. (Data Source: EIA , National Climate Data Center ) Last week’s deviation from normal temperatures was 6.38. So for next week’s storage report, the extraction from storage is likely to be, yet again, lower than the 5-year average, which was 165 Bcf. The ongoing low withdrawal is likely to bring storage to even slightly higher-than-normal levels in the coming weeks. Over the next couple of weeks, the weather is still projected to be colder than normal in the east and hotter than normal in the west. For February, the recent monthly report of the National Oceanic and Atmospheric Administration predicts above-normal temperatures in many parts of the U.S., except for certain regions such as the Northeast. But the weather forecast still entails uncertainty mainly related to a potential El Nino. But for now, it seems hard to see how UNG will start to pick up again to its high levels unless the weather starts to get much colder than it is now. After all, even the recent recovery in oil prices didn’t bring natural gas up. The recent news from Baker Hughes of the sharp drop in oil rigs has influenced oil inventors to adjust (or speculate on) their expectations about changes to the U.S. oil supply. This news brought oil prices back up in the past week. Oil rigs have declined by 83 rigs last week, and by a total of 276 rigs in the past year. But this rally didn’t seem to have much of an impact on natural gas prices, which only kept coming down. After all, gas rigs slipped by only 5 in the past week to reach 314. The uncertainty in the weather forecast for February could imply high volatility in the natural gas market. If the withdrawal from storage continues to be lower than normal, this could keep the price of UNG down. For more see: ” Has the Weakness in Oil Fueled the Decline of UNG? ” Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article.