Tag Archives: management

El Paso Electric – A Regional Utility Worth Considering
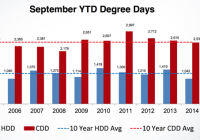
Summary The utilities sector declined nearly 4% on Friday amid strong hiring news. El Paso Electric is now trading at under 18X earnings, cheaper than S&P 500 and Dow Utility Index. After a hiatus beginning in the late-1980s, El Paso Electric is again making dividend payments, including its most recently announced .28/share payment, its 16th straight quarter. Largest market is El Paso in Texas, which is viewed as a pro-business positive net-migration state. Decision not to participate in the renewal of aged coal power-generating plant reflects the modernization and commitment of the Company to provide sustainable long-term energy production. El Paso Electric (NYSE: EE ) is a regional electric utility company that provides generation, transmission, and distribution service to the southwestern United States and Northern Mexico. Its 10,000 square mile service area includes parts of Texas, New Mexico, and two connections to Juarez and the Mexican national utility, Comision Federal de Electricidad. The Company’s principal industrial and large customers operate in the steel production, copper, oil refining and defense industries (including Fort Bliss Army Base and White Sands Missile Range). El Paso Electric’s net dependable generating capability of 1,852 megawatts. Key events and catalysts – A substantial portion of the Company’s fossil fuel generation facilities are over 50 years old. Over the last five years, El Paso Electric has spent nearly $1 billion dollars for the replacement of plant and equipment and for additional generation, transmission and distribution. – El Paso Electric constructed its first new plan in nearly 30 years, a 288 MW Newman 5 natural gas-fired combined cycle plant – Additional cap-ex expected to top $1.5 billion in the next five years – Due to favorable location in high desert and reduction in cost of solar panels, El Paso Electric has introduced significant utility scale solar generation at costs competitive with fossil fuel alternatives – The Company’s Montana Power Station (a $372 million local generation facility) is expected to go on-line by summer of 2015 – El Paso Electric will not participate in extending the operation of the nearly five decade old coal-fired Four Corners Power Generating Station after its scheduled retirement in July 2016. – New Mexico rate case finalization in April 2015 and Texas rate case finalization in August 2015 will seek to recapture costs related to construction, load growth and facility retirement Service Area (Source Annual Report) (click to enlarge) While the population of the state of New Mexico grew a paltry 1.3% from April 2010 – July 2013 (compared the US as a whole – 2.4% – most recent data available from Census Bureau), the state of Texas grew 5.2%, more than double the national rate. Power Generation Station Primary Fuel Type Owned Net Dependable Generating Capacity (NYSE: MW ) Ownership Interest Location Palo Verde Station Nuclear 633 15.8% Wintersburg, Arizona Newman Power Station Natural Gas 732 100% El Paso, Texas Rio Grande Power Station Natural Gas 316 100% Sunland Park, New Mexico Four Corners Station (Units 4&5) Coal 108 7% Fruitland, New Mexico Copper Power Station Natural Gas 62 100% El Paso, Texas Renewables Wind/Solar 1 100% Hudspeth/El Paso Counties, Texas Total   1,852     (Source: Most recent annual report) Notes on power generation: – The Nuclear Regulatory Commission renewed the license of all operating units at Palo Verde which now expire between 2045 – 2047. – The estimated decommissioning costs related to the Palo Verde plant is $381 million. El Paso Electric’s trust fund had a $214 million at 12/31/13. – The 50-year participation agreement among the owners of the Four Corners Station expires in July 2016. El Paso Electric has informed the other owners that it has decided to cease it participation in the plant by July 2016 opting for more economical and cost effect energy alternatives. Customer growth Growth Rate Since 2009 Total growth: 29,335, 1.5% per year Residential growth : 25,482, 1.5% per year (click to enlarge) Customer growth has been positive since 2009, but at a very modest rate in total. Earnings per share EE Net Income (NYSE: TTM ) data by YCharts While earnings per share and net income are generally positive trending over the past decade, El Paso Electric has seen drop-offs in the last several years as decommissioning and other costs have outweighed rate and customer increases. El Paso Electric’s continued profitability hinges on its ability to successfully manage delivery and production costs in a rate-regulated environment. Last Friday, positive hiring news led to declines in “safe-haven” assets including gold, bonds and utilities stocks. El Paso Electric shares fell 4.34%, consistent with sector declines. The Company now trades at 17.72x TTM earnings , which is a lower multiple than the S&P 500 (20.03x) and the Dow Jones Utility Index (19.63x). Reliance on nuclear sourced power   2013 2012 2011 2010 2009 Nuclear 46% 46% 45% 45% 45% Natural Gas 34% 32% 30% 27% 22% Coal 6% 6% 6% 6% 7% Purchased Power 14% 16% 19% 22% 26% Nuclear power makes up a substantial portion of the Company’s sourced electricity. Despite the recoverability of fuel costs for nuclear power generation, it is still expensive and can result in additional regulatory costs associated with production, waste storage and disposal. The Company current sources less than 1% of its power from solar, wind and other renewable sources, but continued investment in these alternative energy sources can help El Paso Electric to remain profitable and competitive. Weather and energy (click to enlarge) (Source: Investor Presentation) Demand for energy is in part driven by climate and weather patterns. As show above, cooling degree days (CDD) dipped below their ten year average for the first time since 2008, while heating degree days (HDD) days are down to levels not seen since 2006. Assuming global warming is real , it is not unreasonable to expect larger and more frequent temperature swings which could drive demand for electricity. Selected Ratio and financial analysis (all information from morningstar.com unless otherwise noted) Ratios and metrics   TTM 2013 2012 2011 2010 2009 Gross margin % 65.6% 67.5% 70.5% 67.5% 66.7% 64.4% Operating margin % 16.3% 18.6% 19.8% 20.8% 19.3% 16.1% Debt/equity 1.12 1.06 1.21 1.07 1.05 1.11 Book value per share 24.13 23.51 20.57 19.10 19.10 16.51 The Company’s gross and operating margins have been fairly consistent, while maintaining a health debt/equity ratio and increasing tangible book value per share. One risk facing the El Paso Electric is the continued availability of debt and equity financing for construction and other projects. Cash flow and dividends   TTM 2013 2012 2011 2010 2009 Operating cash flow 237M 247M 273M 252M 239M 269M Capital expenditures 326M 289M 269M 236M 224M 252M Free cash flow -89M -42M 4M 16M 15M 17M Dividends 1.09 1.05 .97 .66 – – Operating cash flow has been on the decline since 2012, which is not what I look to see from a utility. The Company is investing in business, growing capital expenditures each year since 2010, which hopefully will result in more attractive power generation, distribution, and delivery mechanisms. As previously mentioned, prior to 2011, El Paso Electric had not paid dividends since 1989. Since the reinstitution its dividend policy, the company has grown the total payout each year since 2011. Understanding the Mexico opportunity While El Paso Electric serves a limited geographic (southwestern United States and northern Mexico), it has a fairly diversified customer base within this region. According to El Paso Electric’s most recent annual report, no customer makes up more than 4% of non-fuel base revenues. Most of the energy distributed to the Comision Federal de Electricidad is consumed in Juarez, a city of 1.5 million. While Juarez has a reputation for crime and violence, the city represnts a solid investment opportunity for El Paso Electric as it has nearly doubled in population since 1990. Continued growth and modernization of Juarez will be a long term benefit to El Paso Electric’s bottom line. Leadership El Paso Electric announced Thursday that Chairman of the Board Michael Parks resigned to accept a job with a global investment management firm. Parks served on the board since 1996. He was replaced by long-time board member Charles Yamarone as the new chairman. Bottom line If I was looking for a moderate risk/reward small cap utility play, I would be satisfied owning El Paso Electric at current prices. It has a reasonable 2.8% forward yield , conservative 50% payout ratio, and is taking steps to move away from dirty energy and to cleaner renewable sources. There are a substantial number of utilities that offer higher yield, a longer and more consistent dividend history, and more years of profitability. El Paso Electric may be the right stock for your portfolio, but not the right stock, right now, but if you are on the fence and need a sign, put it on your watch list, and consider scaling into a position when any of the following occur: – Alternative energy as a percentage of net dependable generating capacity exceeds 10% of total. This would mean El Paso Electric has entered a new era of largely clean (natural gas and alternative) energy generation that could be a competitive advantage when the freeze-period expires and competition is introduced into EEs Texas service area. – Yield rises to 5% (but payout stays same or increases). For this to occur, El Paso Electric would need to be trading at $22.40 per share, or a dirt cheap 10.2X earnings. – All Coal and Nuclear operations are ceased and all decommissioning costs settled and final. This would remove substantial uncertainty and potential earnings volatility for intermediate horizon investors (3 – 5 years). Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article.
Buy Russia: Now A Bargain At Just About 6 Times Earnings

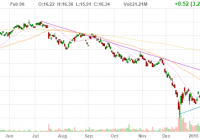
Russian stocks are very cheap at just over 6 times earnings and should be appealing for bargain hunters and contrarians. Weak oil prices have hurt Russia’s economy, but oil may have bottomed out and could rise in the future. The issue with Ukraine remains a wild card, but it appears that all parties have too much to lose and that means a resolution could be likely. The plunge in oil prices and the increasingly stiff sanctions over Russia’s foray into Ukraine have taken a big toll on the economy and the stock market. The negative headlines are likely to continue for awhile when it comes to Ukraine, but as far as the price of oil goes, things seem to be looking up thanks to a recent rebound. I am wary about investing in Russia because the geopolitical risks are significant and there are also currency and other risks. However, when valuations get to very cheap levels, it is hard to resist buying a bargain. Because of the numerous ongoing risks, I can’t allow myself to invest heavily in Russian stocks, but the cheap valuation makes me want to buy small position in the Market Vectors Russia ETF (NYSEARCA: RSX ). Let’s take a closer look: (click to enlarge) As the chart above shows, this ETF was trading for about $26 per share in July 2014, but has since plunged into the low teens. However, it is worth noting that since December, there has been a solid rally as indicated by the light blue uptrend line. Over the last few weeks, oil also appears to have bottomed out and if so, this is a major positive for Russia’s economy. Even so, that leaves the risk of war and sanctions. The sanctions have certainly started to impact the Russian economy, and it could not really come at a worse time because of the plunge in oil prices. If oil prices were still around $80 to $100 per barrel, I believe that Russia could afford to take a more protracted and antagonistic stance when it comes to Ukraine. The fact that oil is about 50% below the 2014 highs, makes me think that Putin will want to be a little more negotiable when it comes to finding solutions with the West that could lift sanctions. Over the last few days, Putin has been meeting with Germany’s Merkel, President Hollande of France, Ukraine’s leader, Petro Poroshenko and other leaders in order to find solutions. If these talks fail, the chance of war might increase which could cause Russian stocks to re-test recent lows. There is a lot at stake for all parties, especially for Russia and many European nations because of significant trade and because they rely on Russian natural gas. In a worst case scenario, Putin could shut off natural gas pipelines to Ukraine and Europe which would be a real blow to those economies. While those are significant risks, it seems like too much is at stake and I don’t see what any of the parties have to gain by escalating matters. On the positive side, if oil has bottomed out and if a cease fire is agreed to and sanctions are eventually lifted, Russian stocks could have significant upside. Russia is here to stay and this nearly perfect storm of weak oil prices and sanctions might be a fantastic buying opportunity. The Market Vectors Russia ETF has a price to earnings ratio of just about 6.5 times earnings. Right now, the S&P 500 Index (NYSEARCA: SPY ) trades for nearly 18 times earnings. The Market Vectors Russia ETF has significant exposure to the oil industry as well as other commodities. Below, you can see the top ten holdings : (data sourced from Yahoo Finance) Top 10 Holdings (57.78% of Total Assets) Chris DeMuth Jr. is a Seeking Alpha contributor, and I believe he is also an extremely savvy investor. He recently wrote about the opportunities in Russia and pointed out metrics which show just how cheap the Russian market is now, he states : “Concerns about Russia have driven down the price of its equity market. Russia’s total market cap is only 17% of its GDP, one of the lowest in the world. This is its historical minimum and far below its maximum of 142% during the past fifteen years. Over the past eight years, its GDP has grown by over 13% per year.” Marc Faber is a well-known investor, and he is also seeing a potential buying opportunity when it comes to Russian equities. He believes Central Banks have inflated asset prices through money printing but that “low valuations” in Russia are worth considering. His views were discussed in a Bloomberg article which stated: “Russian assets may move into some kind of a buying range,” Faber told an investor briefing in London. “They can go lower but they’re moving into a buying range.” Shares in the MSCI Russia index trade at an 80 percent discount to their U.S. counterparts based on their price-to-earnings ratio, compared with an average discount of 50 percent since 2003, Datastream data showed. Russian assets are clearly cheap, and could get cheaper. You should expect volatility to continue. Because of this it makes sense to buy only a small amount and average in over time. It also makes sense to have a long-term time frame. Ten years from now, I doubt the “Ukraine Crisis” will still be top headline news and I also doubt oil will be trading for $50 per barrel. If that is the case, a little investment in Russia could pay off big in the future. Data is sourced from Yahoo Finance. No guarantees or representations are made. Hawkinvest is not a registered investment advisor and does not provide specific investment advice. The information is for informational purposes only. You should always consult a financial advisor. Disclosure: The author is long RSX. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article.

How Rebalancing Can Help Improve Earnings Quality And Lower Multiples

By Jeremy Schwartz A key process driving the WisdomTree earnings-weighted Index approach is a rebalancing process that refreshes constituent weights based on changes in Earnings Stream® and relative value. In earnings-weighted indexes, changes at the rebalance are made based on each stock’s relative price appreciation compared to its relative earnings growth: Companies whose stock prices increased compared to their peers’ while their earnings decreased compared to their peers’ would typically see reduced weight in the WisdomTree Earnings Indexes. In a market cap-weighted index, the only driver of weight is the relative change in market capitalization, which is usually driven by the stock price. Companies whose stock prices fell while their earnings were flat or grew would typically see increased weight in the WisdomTree Earnings Indexes. Companies that have not been profitable on a cumulative basis over the previous four quarters are removed to ensure the continued focus on earnings-generating stocks-one element that improves the quality of the basket by removing more speculative, unprofitable ventures. Weight is also shifted to the relatively more profitable companies and those that have seen highest earnings growth. One way to gauge the impact of the rebalance process is to look at the price-to-earnings (P/E) ratio, essentially the price of the Index divided by its earnings per share before and after the rebalance. Below we show the P/E multiples across market segments. As will be shown, the rebalance can have a large impact on a portfolio’s P/E ratio. U.S. Equity Index Estimated 12-Month P/E Ratios* (as of 11/30/14) (click to enlarge) For definitions of terms and indexes in the chart, visit our glossary . A Lower P/E Ratio Approach: Even prior to the 2014 rebalance, each earnings-weighted Index exhibited a lower P/E ratio than its market capitalization-weighted counterpart. After the rebalance, the P/E ratios dropped even more significantly compared to these benchmarks. This is a key benefit of the annual rebalance process that forces the discipline of reweighting to the fundamental value of the underlying constituents in the Index. Multiples Contracted Anywhere between 7% and 40% across All Indexes: The WisdomTree SmallCap Earnings Index saw multiples contract the greatest at approximately 40%. WisdomTree requires each constituent of its earnings family to demonstrate profitability. This addresses the problem seen in the Russell 2000 Index -namely, a high index-level P/E ratio that is due to index-level earnings being depressed by constituents with negative earnings-by eliminating firms that have had negative earnings over the prior 12 months. Since there are more constituents in small-cap indexes that have delivered negative earnings over the prior 12 months than there are in large-cap indexes, this effect is more pronounced within this size segment. Rebalance Track Record-Consistency in Raising Return on Equity (ROE) Now that we have studied the impact of the rebalance on lowering P/E multiples, we will show the impact of the rebalance in helping to raise the “quality” of the earnings Indexes, measured by the ROE. Post-Rebalance Raising ROE and Improving Quality (click to enlarge) For definitions of terms and indexes in the chart, visit our glossary. This chart illustrates how the rebalance has raised the ROE across four WisdomTree Earnings Indexes. In the 2014 rebalance, for example, the ROE of the WisdomTree SmallCap Earnings Index before and after the rebalance was 7.43% and 11.97%, respectively. As the bull market in equities carries on, it becomes ever more important to pay attention to the underlying valuations and market fundamentals. Above we show how the rebalance both lowered the P/E ratios of each WisdomTree Earnings Index and raised the ROE, a key metric of quality. We believe these are attractive attributes of market exposures, made even more important by the continued gains in the market we have seen in recent years. Important Risks Related to this Article Investments focusing on certain sectors and/or smaller companies increase their vulnerability to any single economic or regulatory development. Jeremy Schwartz, Director of Research As WisdomTree’s Director of Research, Jeremy Schwartz offers timely ideas and timeless wisdom on a bi-monthly basis. Prior to joining WisdomTree, Jeremy was Professor Jeremy Siegel’s head research assistant and helped with the research and writing of Stocks for the Long Run and The Future for Investors. He is also the co-author of the Financial Analysts Journal paper “What Happened to the Original Stocks in the S&P 500?” and the Wall Street Journal article “The Great American Bond Bubble.”