Tag Archives: management

Mean Reversion Monkeys

Editor’s note: Originally published on February 5, 1015 The buzz has been building on this trade for weeks. Clients, friends, people on Twitter, everyone I know has been waiting for a chance to pick the bottom in oil. I’ve heard all this chatter on which triple-leveraged oil ETFs to use (I make a point of not knowing such things). They’ve been waiting for this opportunity since oil was at 80 bucks. Interestingly, they could have shorted it when it was at 80. Actually, they could have shorted it at 110. Or 100. Or 90. Or 80. Or 70. Or 60. Or 50. They could have shorted it at 50 and still made money. But they waited this entire time, watching passively as oil plummeted over 60%, to play a 10-point bounce over the course of a couple of days. Well, the mean reversion monkeys , as I call them, will tell you that they just made 20% in three days. Annualize that! Problem is, it doesn’t work that way, because you can’t flawlessly pick every bottom. I was a mean reversion monkey once, and for every time I made 20% in three days, there were three other times I almost got carried out—like that time in 2008 when I tried top-ticking the Canadian dollar. That one was painful. Have you ever heard of a CTA? CTA stands for Commodities Trading Advisor. It’s basically like a hedge fund that trades futures, but these guys are notorious trend followers. This is how John Henry, owner of the Boston Red Sox, made his money. They trade futures, they trade with leverage, and when stuff starts moving, they follow the trend. They don’t care what it is, or which way it’s going. The trend is your friend. There weren’t that many people who made money on falling oil, but the CTAs absolutely killed it. Ever notice there’s no such thing as a CMRA? A Commodities Mean Reversion Advisor? That’s because they wouldn’t make any money. The vast majority of traders and investors are mean reversion monkeys. I would place the number at well over 90%. Maybe 95%. You can make money as a mean reversion monkey, but not much. Basically, you are relying on your ability to scalp in and out of things continuously to make money. And you wonder why average hedge funds only make 5-6% a year if they’re lucky. They cut short their losers, but they cut short their winners, too. At the end of 2007, when I was still trading proprietarily at Lehman, I did an interesting exercise. I went back and looked at the P&L of every trade I did over the course of the year. I had one or two big winners, with small ups and downs everywhere else that all canceled each other out. If it weren’t for the one or two big winners, where I happened to bet big and let the profits run, I would have basically been flat for the year. In fact, I think if you analyzed anyone’s portfolio, it would look pretty much the same. In a portfolio that’s up 10%, you’re going to have one or two huge winners, and everything else will be chopped salad. The reality is that most people are only good for one or two good ideas a year. Maybe less. So wouldn’t it make sense to put as much money in those ideas as possible? Market Wizards If you go back and read your Jack Schwager Market Wizards books, and read about all the stud traders, you won’t find one of them who would be buying triple-leveraged oil ETFs for a 10% bounce in oil. No. Those guys would have had the dominant trend right. They don’t care about the countertrend, because that’s not where the money is. Trading with the trend is the only way to make meaningful amounts of money. All of Wall Street right now is doing a smug victory lap for their scalp in oil, but the funny thing about scalps is that people get greedy and, as trends often do, oil will make lower lows and people will find themselves sitting on losses instead of profits. Catching the falling knife requires so many things to go right simultaneously to work. Have you ever met someone who has money all out of proportion to his intelligence? Someone who just goes around with a horseshoe up his ass? The guy that bought Apple (NASDAQ: AAPL ) at $50 and sold it at $700. “So,” you ask this dude, “why did you buy Apple?” “It was going up.” It was going up. This is not someone who you think is particularly smart. But maybe he made $500,000 on this trade. And now he is long the iShares biotech ETF (NASDAQ: IBB ). How does he do it? How can someone so intellectually lazy be so rich? I mean, you spend hours staring at charts and watching oil tick for tick, and you timed the bottom perfectly, and you make… 10%. The Magic of Compounding Research has shown that owning equities with the dividends reinvested is about the closest you’re going to get to a sure thing in the markets. And your holding period needs to be long (like Buffett’s) so earnings/cash flows have a chance to compound. I’m sure you’ve done that exercise where you were earning 3% interest in the bank and you want to see how it compounds over time, so you stick it in an Excel spreadsheet and do the math. Same thing. If you don’t give something a chance to compound, the odds of making a meaningful amount of money are very small. Have you ever noticed that anyone who gained notoriety for being a day trader did so 15 years ago? There was no other time in history where you could literally make a living by cutting your winners short. As for being intellectually lazy, well, there’s a difference between being smart and having a psychological need to prove you’re smart, or different. What’s wrong with holding IBB if you are making money? Seems easier than buying something that hasn’t had an uptick in months. Like most sell-side guys, I was a mean reversion monkey back in the day. I’ve spent the last several years unlearning everything I had learned. Yes, investing is one of the hardest things in the world. But shockingly, it doesn’t have to be. Disclosure : At the time of writing, Jared Dillian was short CAD
NYSE Margin Debt Dips A Mite In December: Risk Rank At No. 43

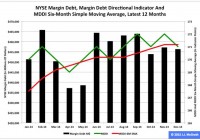
Summary New York Stock Exchange margin debt slipped slightly to $456.28 billion in December from $457.11 billion in November. On the same basis, the SPDR S&P 500 Trust ETF’s adjusted closing monthly share price also slipped slightly to $205.54 from $206.06. The risk of speculation appeared lower in December than it did in November, but higher than it did in 69.93 percent of all months ranked by my methodology. New York Stock Exchange margin debt and the SPDR S&P 500 Trust ETF (NYSEARCA: SPY ) moved in the same direction in December for the second straight month, as each was down a wee bit. The level of NYSE margin debt relinquished -$823 million, or -0.18 percent, and the share price of SPY surrendered -$0.52, or -0.25 percent. Many equity market participants consider margin debt a long-term indicator of speculation in the stock market because of their tendency to move either higher or lower together. The NYSE has reported monthly data on securities market credit in three discrete series since 2003 and on margin debt itself since 1959. My primary analyses of these three data series focus on two proprietary metrics, the Margin Debt Directional Indicator, or MDDI, and the Securities Market Credit Risk Rank , or SMC Risk Rank, as described in “NYSE Margin Debt As An Indicator Of Long-Term Movements In S&P 500.” Figure 1: MDDI, January 2014-December 2014 (click to enlarge) Source: This chart is based on a proprietary analysis of monthly margin-debt data at NYSE’s online site. NYSE margin debt in December was -$9.44 billion, or -2.03 percent, lower than it was at its all-time high level in February (Figure 1). The anomalous behavior of margin debt in neither falling a great deal nor rising a great deal during the rest of 2014 appears unsustainable, factoring in the U.S. Federal Reserve’s actual announcement of the end of its latest quantitative easing program Oct. 29 and projected announcement of the beginning of its newest interest rate cycle April 29. This anomalous behavior is reflected by the MDDI, which basically is a comparative assessment of NYSE margin debt in the two most recent months of the data series. If the latest value of the MDDI ( MDDI in the above figure) is higher than its six-month simple moving average ( MDDI 6M SMA in the same figure), then I consider the market to be in bullish mode. If the most recent value of the MDDI is lower than its six-month SMA, then I consider the market to be in bearish mode. The MDDI’s December level is 171, which is lower than its November value of 172 and its six-month SMA of 171.17. As a result, I consider the equity market to have switched modes as of Dec. 31, to bearish from bullish. Based on the January performances of the stock market in general and SPY in particular, I anticipate a continuation of this mode for another month (at least). Figure 2: Highest And Lowest Risk Months, Per SMC Risk Rank (click to enlarge) Source: This table is based on proprietary analyses of monthly securities-market-credit data at NYSE’s online site. December is No. 43 among all 143 months evaluated since the January 2003 baseline by my SMC Risk Rank methodology, which carries out a comparative assessment of the data NYSE has reported in three discrete series: Margin Debt , Free Credit Cash Accounts and Credit Balances in Margin Accounts . The dynamic SMC Risk Rank is designed as a measure of equity market risk associated with speculation, ranking each month in the data set on an ongoing basis. At present, June 2014 is No. 1 , February 2014 is No. 2 and December 2013 is No. 3 among all months ranked (Figure 2). November’s SMC Risk Rank of No. 43 means I consider the stock market risk associated with speculation last month was higher than 69.93 percent and lower than 29.73 percent of all other months evaluated by the methodology. A high SMC Risk Rank for a given month indicates the market may be close to a significant peak, and a low SMC Risk Rank for a given month suggests the market may be close to a significant trough. In my interpretation, the term close in this context typically has meant within three to six months . Figure 3: NYSE Margin Debt And SPY, January 1993-December 2014 (click to enlarge) Source: This chart is based on monthly margin debt data at NYSE’s online site and adjusted closing monthly share prices of SPY at Yahoo Finance . Historically, NYSE margin debt and SPY have tended to move together, with an almost perfect positive correlation coefficient of 0.97 between them since the exchange-traded fund began trading in 1993 (Figure 3). I anticipate this close relationship will become increasingly important in the absence of Federal Reserve asset purchases under a QE program. If I were a party to either side of a margin debt transaction, then this is the time when I would start wondering whether more speculation is the wisest way to go. Disclaimer: The opinions expressed herein by the author do not constitute an investment recommendation, and they are unsuitable for employment in the making of investment decisions. The opinions expressed herein address only certain aspects of potential investment in any securities and cannot substitute for comprehensive investment analysis. The opinions expressed herein are based on an incomplete set of information, illustrative in nature, and limited in scope. In addition, the opinions expressed herein reflect the author’s best judgment as of the date of publication, and they are subject to change without notice. Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article.

Critiquing Klarman

Seth Klarman wrote a very good piece for the FT yesterday on the 12 things he’s learned from Warren Buffett. Only an idiot would disagree with Klarman so, like any good idiot, I wanted to write my own version/critique of Klarman’s thoughts: 1. Value investing works. Buy bargains. CR here – Yes, value investing works. I embrace value investing where appropriate . But it’s also tremendously difficult. As Buffett has stated on several occasions, you’re probably better off not trying to do what he does. You’re better off buying low fee index funds. More importantly, you should think of “investing” as your primary source of income. The thing most people call investing is actually a reallocation of savings. Treat it like savings and avoid the gambler mentality that leads so many astray. 2. Quality matters, in businesses and in people. Better quality businesses are more likely to grow and compound cash flow; low quality businesses often erode and even superior managers, who are difficult to identify, attract, and retain, may not be enough to save them. Always partner with highly capable managers whose interests are aligned with yours. CR here – Couldn’t agree more. As Buffett has stated, surround yourself with people who are smarter than yourself. If you’re me, just surround yourself with other people. 3. There is no need to overly diversify. Invest like you have a single, lifetime “punch card” with only 20 punches, so make each one count. Look broadly for opportunity, which can be found globally and in unexpected industries and structures. CR here – I think this is great advice in your personal life. I always talk about how real “investments” are made in our primary source of income. Don’t diversify there. Do one thing and do it well. Your savings, however, should be treated like savings. Diversify it broadly across many asset classes so it protects you from purchasing power loss and permanent loss, but don’t take so much risk here that it creates instability in your ability to plan for your financial future. 4. Consistency and patience are crucial. Most investors are their own worst enemies. Endurance enables compounding. CR here – Brilliant. You are own worst enemy. Educate yourself, create a process/plan and get out of the way. 5. Risk is not the same as volatility; risk results from overpaying or overestimating a company’s prospects. Prices fluctuate more than value; price volatility can drive opportunity. Sacrifice some upside as necessary to protect on the downside. CR here – Risk is the potential that we won’t meet our financial goals. Most of us don’t need to waste time looking at individual firms that have already been scoured by the smartest investment bankers and investment managers on Earth. If we beat inflation and do so without creating excessive permanent loss risk then we are beating most of the people engaged in the investment world. 6. Unprecedented events occur with some regularity, so be prepared. CR here – In other words, diversify so that you protect yourself not only from the unknown, but from your own stupidity. 7. You can make some investment mistakes and still thrive. CR here – you won’t just make some mistakes. You will make consistent mistakes. The goal is to engage in a strategy that exposes you to high probability of positive outcomes. Losses are part of the process. Learn from them and improve the odds of your future processes. 8. Holding cash in the absence of opportunity makes sense. CR here – as Buffett says, think of cash like a call option. A little bit of cash provides you with flexibility, permanent loss protection and the ability to contribute consistently to a broader plan. Your savings portfolio needs to be fed. Feed it consistently so it gets nice and fat. 9. Favour substance over form. It doesn’t matter if an investment is public or private, fractional or full ownership, or in debt, preferred shares, or common equity. CR here – think macro, not micro. Different asset classes are a function of differing legal structures and behaviors. When pieced together correctly they should complement one another even if they don’t always agree with one another. 10. Candour is essential. It’s important to acknowledge mistakes, act decisively, and learn from them. Good writing clarifies your own thinking and that of your fellow shareholders. CR here – in other words, write a financial site where you critique people who are much smarter than you are. 11. To the extent possible, find and retain like-minded shareholders (and for investment managers, investors) to liberate yourself from short-term performance pressures. CR here – if your investment manager doesn’t eat his own cooking then maybe they shouldn’t be cooking for you. 12. Do what you love, and you’ll never work a day in your life. CR here – don’t do what you love. Do something other people will love you for doing. Good capitalists serve themselves best by serving others.