Tag Archives: management

Hold Off On VXUP And VXDN For Now
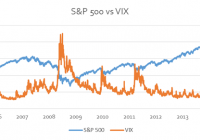
Summary VXUP and VXDN do not provide the “spot” VIX exposure as promised. VXUP and VXDN have had consistently high tracking errors. Distributions are not necessarily in cash and may be in the form of the opposing share. Volatility Products and VIX Exposure A variety of products have been developed over the years to mimic the performance of the VIX implied volatility index as well as possible. There are 3 distinct types of product available on VIX: VIX Futures – This provides indirect exposure to the movements in the index. There is a term structure in the VIX futures market. It is typically in contango. The implication of this is that long contract investors are paying a premium to contract sellers for portfolio insurance. The term structure will switch to backwardation when there are market sell-offs because VIX is mean reverting; this means that the VIX will drop and investors need to be compensated for the expected drop in the form of lower prices. It is important to note that the term structure will not be flat – this is akin to free insurance, and we all know there ain’t no such thing as a free lunch. VIX Options – This variety of call option performs excellent as portfolio insurance, because they capture the positive upside and are capped on the downside. It is likely that the option premium should reflect this, however, they are relatively illiquid. VIX-derived Exchange Traded Products – Products such as the iPath S&P 500 VIX Short-Term Futures ETN ( VXX) are ETFs based on VIX futures and therefore seek to mimic the futures market results. They are suitable for investors who are prevented by their mandates to invest in derivative products. However, it is worth noting that the significant issue with these products is that they necessarily lose out due to roll yield. A negative roll yield plagues markets in contango, where near futures are cheaper than further futures. The VIX futures market is generally in contango. These products should be held for short-term, tactical trades. Realized vs. Implied Volatility There is a significant body of literature on the subject and linkages between realized and implied volatility. Realized volatility is the actual average annualized volatility which occurred over a certain period. Implied volatility is the volatility that market expects to occur over a time period. Historically, implied volatility overestimates subsequent realized volatility. The implication is that there is a “volatility risk premium” in the options market – participants selling put options demanding more than fair value for the risk of providing portfolio insurance. What is the link between this and VIX? VIX is calculated from a wide range of option prices; it represents the market’s broad estimate of implied volatility. Thus, it also represents the market’s expectation of future volatility. This is why it is used as the “market fear gauge”. The value of VIX is driven most heavily by at-the-money put options on the S&P 500 Index. S&P 500 put options are a very simple manner in which to obtain portfolio insurance. One purchases the put option at the current level; if that market falls below that level, your portfolio drops as well, but you profit from the put option. Now, sellers of these options are effectively providing insurance to investors. How has volatility behaved over the last decade or so? The weeks where there were market drops of between 5% and 10% are tabulated below: Week Return VIX Performance 26 February 2007 – 5 March 2007 -5.19% 76.05% 8 August 2007 – 15 August 2007 -6.06% 42.98% 31 December 2007 – 8 January 2008 -5.32% 13.02% 14 January 2008 – 22 January 2008 -7.47% 35.41% 10 September 2008 – 17 September 2008 -6.14% 47.72% 22 September 2008 – 29 September 2008 -8.34% 38.02% 16 December 2008 – 23 December 2008 -5.48% -14.03% * 8 January 2009 – 15 January 2009 -7.25% 19.83% 27 February 2009 – 6 March 2009 -7.03% 6.43% 19 January 2010 – 26 January 2010 -5.05% 39.65% 30 April 2010 – 7 May 2010 -6.39% 85.71% 17 May 2010 – 24 May 2010 -5.57% 24.25% 25 June 2010 – 2 July 2010 -5.03% 5.57% 26 July 2011 – 2 August 2011 -5.85% 22.54% 15 August 2011 – 22 August 2011 -6.70% 33.17% 16 September 2011 – 23 September 2011 -6.54% 33.15% 26 September 2011 – 3 October 2011 -5.48% 16.48% 16 November 2011 – 23 November 2011 -6.07% 1.40% 8 October 2014 – 15 October 2014 -5.40% 73.73% *This is an outlier – VIX was coming off of its historical high. It has a mean reversion property. We can see that, for our narrowed down dataset, we can generally associate large VIX returns with relatively large market corrections. There is, however, no increasing/linear relationship here. This is probably due to mean-reversion property of the VIX itself. AccuShares VXUP and VXDN Recently released, the AccuShares Spot CBOE VIX Up Shares ETF ( VXUP) and the AccuShares Spot CBOE VIX Down Class Shares ETF ( VXDN) products seek to provide investors with a 1-month exposure to the pure VIX index. This is difficult because one cannot own a unit of volatility. Indeed, attempting to replicate the VIX index is a complex and costly exercise. How Does It Work? The total fund is effectively split into two separate funds that mirror one another. The “Up” and the “Down” fund. The assets in the fund are not related to volatility and are based entirely on U.S. treasury securities. The manner in which they achieve spot exposure is by simply offsetting the Up and Down shares against each other. Thus, the two move in the completely opposite direction. This means that they have created a zero-sum game and cannot lose. Only the investors can lose. If the VIX Index value is 30 or below as of a distribution date (which is basically a reset date) then a Daily Amount of 0.15% is subtracted from the Up fund and accrued to the Down fund. This works out to 4.5% monthly decay on being long volatility. You can think of this as a negative roll yield you would incur in the futures market. There are a variety of distributions which are paid to the investor and form the return. Regular Distribution – The intrinsic value of the Up and Down share match the percentage move of the VIX index over the 16th to 15th of every monthly cycle. Now, whichever fund wins, gets a distribution equal to the difference between its final value and the losing funds value. Then, the intrinsic value for both funds is set at the value of the losing fund. So the investor loses in capital gains what he gains over and above his return. The analysis of tax implications is a separate discussion. Special Distribution – The maximum gain in any month is capped at 90% to protect Down share investors from losing their entire investment. If any gains more than 75%, then there is a special distribution, which is simply an immediate distribution with the same rules as the regular distribution. Corrective Distribution – This occurs when the tracking error between intrinsic value and the market price is greater than 10% for 3 consecutive trading days. What happens is that the fund issues the equivalent number of the opposite shares to all investors, effectively resetting the fund values. For instance, say an investor hold 2 Down shares. After the corrective distribution, they will hold 2 Down shares and 2 Up shares. The value of each share is then also halved, ensuring that the investor is back at the intrinsic value they are entitled to. Does this imply that market prices should adjust back to intrinsic value after a Corrective Distribution? Not necessarily. The Issues It is claimed that the Authorized Participants will utilize arbitrage trades to keep the market prices in line with intrinsic value. The arbitrage trade is as follows: If market prices are higher than intrinsic value, purchase more primary shares from the ETF provider, and sell them in the market. The increased supply will reduce the market price and move prices in line. A similar argument holds for the reverse. Why will this not work? The futures market guarantees that there will always be a premium/discount for these shares, and this depends on the degree of contango in the market. It goes even further than this; the market price as of the 11th of June 2015 of the VXUP share is trading at a 12.95% premium to its intrinsic value, the contango between front-month and the closest back-month future is 11.72% (as of 11 June 2015). As an example of why this is so, think of a simple VIX futures market that is in contango (standard situation). This means that purchasing near-term futures are cheaper than longer-term futures. It also means that futures prices are above the spot price. VIX futures prices will converge toward the underlying index value at maturity. Consider the case where the VXUP share has intrinsic value equal to the VIX underlying value (this is a simplifying case) and it is trading in the secondary market at intrinsic value. If you purchased the share, and shorted the front-month future, you would make a positive amount right now (because the future is more expensive than spot). In the future, you would simply deliver the share you are holding that trades at intrinsic value (which is necessarily the VIX index value at that time). Thus, for no future loss and positive gain now, you have found an arbitrage opportunity. If market participants exploited this opportunity, they would bid up the price of VXUP to more than its intrinsic value, introducing the premium. And, this premium would equal the degree of contango. If one factors in the Daily Amount, it simply reduces the return on the VXUP share and reduces the premium the market impounds into the price of VXUP, by the exact Daily Amount. Thus, the Authorized Participants and the market are at odds. The sum of the premium and discount should sum to zero, however, will not disappear because AccuShares requires the shares to be created in pairs. Why are these premiums an issue? The primary issue around these premiums relates to the corrective distribution. Remember, a corrective distribution occurs if there has been a consistent premium of 10% for 3 consecutive days. The corrective distribution then does a stock split and issues the other share class. The issue is reinvestment fees that would be incurred from these distributions. One would end up with the opposite share to what is desired at the end of a period and this would then need to be sold at a discount to what you should get at intrinsic value, resulting in a loss. And brokerage fees. Conclusion The problem of tracking VIX returns is not a new one. Products such as VXX sap investor funds due to their negative roll yield. A variety of other structural issues limit their effectiveness. While VXUP would provide exposure to the VIX index, it does it at considerable cost (4.5% a month if the VIX is below 30) and risk (corrective distributions incurring trading costs). An additional risk in the product is that the prospectus does not guarantee regular distributions will be provided in cash – they may be issued in paired-share equivalents to maintain fund liquidity. From the prospectus: ” Regular and Special Distributions will ordinarily be made in the form of cash during the first six months of trading in the Fund’s shares. Thereafter, the Fund will pay all or any part of any Regular or Special Distribution in paired shares instead of cash where further cash distributions would adversely affect the liquidity of the market for the Fund’s shares or impact the Fund’s ability to meet minimum asset size Exchange listing standards. All payments made in paired shares shall be made in equal numbers of Up and Down Shares. To the extent a share distribution would result in the distribution of fractional shares, cash in an amount equal to the value of the fractional shares will be distributed rather than fractional shares. ” Waiting on the sidelines and seeing how the fund deals with corrective distributions and tracking errors is the best course of action at the moment. I would like to credit Vance Harwood’s blog post over at Six Figure Investing for aiding in the research of this instrument. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article.
Why The Law Of Large Numbers Dictates Effective Risk Management

Summary It is effective risk management that determines profitability rather than the incidence of wins to losses. The law of large numbers suggests that a larger number of trades with a positive reward to risk ratio will be more effective than a smaller number of trades. In this regard, it is possible for a trader to be “wrong” a majority of the time while continuing to remain profitable. “It’s not whether you’re right or wrong that’s important, but how much money you make when you’re right and how much you lose when you’re wrong.” – George Soros The entire dynamic of successful trading could probably be summed up in the above sentence. When I started out trading forex, I was overly concerned with getting the trades right. However, I have come to learn that the most successful traders are not the ones who are right all the time; rather they are the ones who know how to manage their risk most effectively . For instance, the odds that a plane will crash somewhere in the world are 1 in 11 million. Indeed, this is a very low probability. However, when one considers the vast number of flights that take off and land every day, it is sadly almost inevitable that there will be a plane crash at some point in the future. The odds of a golfer getting a hole in one are 5,000 to 1. However, across the world there are far more than 5,000 games of golf being played in a single day; it is therefore almost inevitable that a player somewhere in the world will manage to score a hole in one today. The above phenomenon is known as the law of large numbers ; where an event with a low probability of occurring on its own has a higher probability of occurring when subjected to a large number of trials. This has important implications for risk management, and moreover it demonstrates how a trader can still be wrong the majority of the time while continuing to be profitable. Let us take this as an example. Suppose that we have eight forex trades in a particular month, with a 1:3 risk-reward ratio, or a stop loss of 50 pips and a take profit of 150 pips. For each trade (discounting technical or fundamental factors), the odds are greater that we will make a loss rather than a profit. However, the profit on each trade far outweighs the potential loss. With a 1:3 risk-reward ratio, we have a 75 percent chance of the price hitting our stop loss with a 25 percent chance of it hitting our take profit ratio. However, this also means that only two of the eight trades need to be profitable for us to breakeven. Moreover, the law of large numbers dictates that at least two of our trades are indeed likely to be profitable. 1-(1-p)^number of trials where p is the probability of an event occurring In the above instance, we need at least three of our trades to hit the take profit point in order to be profitable. Given that we have a 0.25 probability of this happening, our probabilities are as follows: 1-(0.25)^1 = 0.25 1-(0.25)^2 = 0.4375 1-(0.25)^3 = 0.5781 1-(0.25)^4 = 0.6835 1-(0.25)^5 = 0.7626 1-(0.25)^6 = 0.8220 1-(0.25)^7 = 0.8665 1-(0.25)^8 = 0.8998 We see that with eight trades being placed, we have an 89 percent probability that at least one trade will hit our take profit point. Given that we need three trades to be profitable: 0.8998^3 = 72.85 percent probability of three trades being profitable In this regard, we see that the law of large numbers provides us with an attractive risk-reward set up in that it limits our downside while maximizing our upside. Moreover, we can be wrong more often than we are right and still remain profitable. One of the big reasons why most new traders fail is the inability to manage risk effectively. For instance, if we decided to set up trades with a high risk and low return, e.g. 150-pip stop loss and 50-pip profit, then even if we were right a majority of the time it would only take a couple of losing trades to wipe out our winnings. Ultimately, being a successful trader is not always about being right. It is about managing your risk effectively. As we can see, the law of large numbers plays a key role in doing so. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.

Vietnam Holding: Nearly Triple The Return Of The VN Index

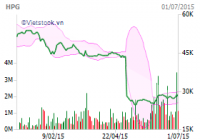
Summary Vietnam Holdings Ltd. had a 1 Year Return of 23.25%, which is substantially higher than the VN Index gain of 8.88%. A further increase in the fund’s price is highly likely for the following reasons: low valuation, recovery of multiple industries, and irrational drops in stock prices that will recover. Vietnam Holdings Ltd. is the best option for investors to gain exposure to Vietnam through US Exchanges. In a previous article , I mentioned the opportunities of investing in Vietnam, and how the Market Vectors Vietnam ETF (NYSEARCA: VNM ) was not the best means to profit off of the growth in Vietnam. When an investment fund is unable to outperform the index and has a negative return in a country with substantial growth, skepticism is befitting. The Market Vectors Vietnam ETF has had a 1 year return of -6.82% , while VN index has had a return of 8.88% . While the most successful funds are generally not listed on US Exchanges, Vietnam Holding Ltd.(OTC: VNMHF ) is a superior alternative that has outperformed the VN Index. Investors, who are bullish on Vietnam and want to trade on US Exchanges, should consider this fund as the most appropriate vehicle. Vietnam Holdings Ltd. is a closed end investment holding company in Vietnam that is listed on the US OTC market. The advantages of this fund include more attractive valuation, consistently higher returns, and its investment in two companies fully held by foreign investors. Performance Comparison Market Vectors Vietnam ETF Vietnam Holdings Ltd. P/E Ratio 15 5.33 Number of companies held with full foreign ownership None 2 1 year return -8.53% 23.25% 3 year return 2.68% 19.4% 5 Year Return -3.70% 14.7% ROE 12% 24.35% Vietnam Holding Ltd. has a very strong portfolio, with extreme low valuation, and more than double the ROE of the top listed equity holdings of the Market Vectors Vietnam ETF. Moreover, the fund’s financial performance has been excellent, particularly in the past year with a return of 23.25% . The current low valuation, coupled with specific companies that demonstrate high potential, will attribute to future success. Its success is mostly attributed to very recent successful performance in the past year, and the growth appears to be in the initial stages. The portfolio is holistically very strong, while I would say that the greatest potential will result from the performance of DHG Pharmaceutical, Petrovietnam Drilling and Well Services, Vinamilk, and Hoa Phat Group. Hoa Phat Group Hoa Phat Group is the most undervalued company, as its share prices have dropped substantially over the past months. The company is currently rated as one of the top 50 best listed companies in Vietnam Forbes and No. 7 for enterprises with the largest turnover. The company has the largest market share for steel production and steel pipe segments, with approximately 18% and 19.8%, respectively . The stock’s price has been constantly declining, although the sharp decline in the middle of May represents an adjustment of stock price due to the issuance of dividends and bonus stocks. I am currently holding Hoa Phat Group at a 9.15% loss, after investing initially in late April and buying down after this drop. Financial performance of the company has been consistent, with strong growth in net income, net revenue, and ROE since 2012. Moreover, Net Income increased by 37% in the 1st quarter of 2015. An increase in steel prices is projected for the future, which will result in recovery of the stock’s price. Vinamilk and DHG Pharmaceutical JSC Although it does not represent a large portion of the fund’s portfolio, the holding of Vinamilk and DHG Pharmaceutical JSC is very strategic, as these companies are fully held by foreign investors. Vinamilk is one of the most sought after companies by foreign investors, as many foreign investors are willing to pay a premium of up to 20% for shares of this company. The slight decline in net income in 2014, coupled with valuation that is not relatively attractive for Vietnam, has not been enough to deter investment away from this company; considerable growth is ahead for the company and its share price will surely increase. Its key position in the dairy market in Vietnam is crucial, as the industry is expected to grow by 9% up to 2020 . DHG Pharmaceutical is another very strategic holding of this portfolio, with average valuation for Vietnam and consistent growth. The company’s EPS is projected to grow by 34% in 2015 , making a rebound in its stock price extremely likely. These two holdings can be considered a major strength of this portfolio, although they only represent 13.7% of the fund’s portfolio. Moreover, there are certainly other companies fully held by foreign investors with better valuation and more potential for growth; some of these include Refrigeration Electrical Engineering Company, Military Commercial Joint Stock Bank, and FPT Corporation. The removal of the foreign ownership limitation in Vietnam, which will begin in some industries in September , will be extremely beneficial for this fund. Both companies are trading very near to their 52 week lows, and an increase in share price in the near future is highly likely, due to company’s valuation, projected growth, and prestige of being fully held by foreign investors. Petrovietnam Drilling and Well Services Petrovietnam Drilling and Well Services is another holding that is extremely undervalued and holding this company will be beneficial, as a rebound in price is inevitable. The sharp drop in price has been very irrational, resulting from the fear of the declining price of oil and some large investment funds selling holdings of this company. Despite the sharp drop in its share price, a large number of foreign investment funds are still keeping this company in their portfolio, in anticipation of a rebound in price. Beyond having extremely attractive valuation, the company has had consistent growth in net revenue since 2003 , even when oil prices fell below $40/barrel in 2009; net revenue increased by 9.9% and net income only fell by 9.5% in 2009. History has shown that the company is capable of continual growth, and its financial performance will not suffer if the price of oil plunges further. Currently trading at 53,000 dong, opportunity for a rebound is substantial as the company is extremely undervalued; the company’s share price dropped to its 52 week low at 42,800 dong earlier this year. General Strengths A large number of companies that this investment fund holds will have a significant increase in their share prices. This will result from a wide variety of factors, including: High value of companies fully held by foreign investors, and the removal of the foreign ownership limitation for some industries beginning in September . Adverse performance of industries, which are on track for recovery. Irrational drops in stock prices, which will be reconciled. A portfolio of companies with low valuation, that have demonstrated consistent financial performance. Favorable outlook for Vietnam stocks, as the VN Index was projected to increase to a seven year high to 655 : it is currently at 605.7 Conclusion I recommend Vietnam Holdings Ltd. as the best option for US investors wishing to invest in Vietnam. Moreover, investment into this fund should be a long-term endeavor, to ensure that investors profit off of the recovery of all industries and the reconciliation of companies that are undervalued. For those wishing to venture further and explore options not listed on US Exchanges, the following investment funds are most suitable: PXP Vietnam Emerging Equity Fund, Asia Frontier Capital’s Vietnam Fund, Tundra Vietnam Fund, and PYN Elite Fund. Editor’s Note: This article covers one or more stocks trading at less than $1 per share and/or with less than a $100 million market cap. Please be aware of the risks associated with these stocks. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.