Tag Archives: investing ideas

Why Energy ETFs Are Now A No-No For Wealth-Building Investors
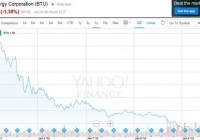
Summary Their prices are all driven by the common denominator of WTI crude prices. Long and Inverse, Leveraged and Unleveraged, all are negatively impacted as crude fights to retain its present share of energy demand. The most telling influence on energy investments, both near term and long term is uncertainty. Near term: Fuel price changes. Longer term: Various fuel shares in energy markets competition. Supply and demand set prices. Surprised? Probably no one is. But is lack of demand the culprit, causing falling prices? Hardly. A revolution in extractive technology has revealed the extent of available, economically attractive natural gas resources, not only in North America, but also worldwide. In comparison to the $4+ prices available in US payoffs up to a year ago for 1 million BTUs of heat generation from reliably available fuel sources, developer-producers in the northeast USA (under financial pressures created in acquiring natural resources) have had to flood the market. The forced surplus over normal demand causes the products to change hands in volume at prices less than half of what used to be. Worse yet, there are reports that major, established NG producers have costs as low as $1.50, and in key areas, sub-$2 prices are the norm. The geology providing this bonanza is not limited to the US. Europe and Asia have identified similar deposits and the extractive technology learning curve is in motion. Coal, which a decade ago was regarded as the USA’s electrical energy backbone, with over 600 years of domestic reserves available, is now facing a virtual complete takeover of its demand market by natural gas. Utilities, prodded by ecological regulations, are converting as fast as they can to get pipeline connections. The stock of Peabody Energy Corporation (NYSE: BTU ), the largest coal supplier, sold above $60 as recently as mid-2011. Now it trades at under $1.20 a share, just 5 years later. (click to enlarge) This is not a transient, irregular, or cyclical phenomenon. It is a major change in the state of energy economics. It is already having major effects in the sources of energy conversion. Before a decade from now passes, it will produce major changes in motive power for personal transportation. It is already impacting commercial hauling. Obama may take credit for a major shift in carbon reductions at electric power plants, but should only get props for being politically agile. Major, established energy producers will have to adapt to the new scene, or become minor players as others in the chain of energy production to consumption become more important. It remains to be seen whether the petroleum industry’s giants, many of whom have been faltering in their efforts to maintain their competitive stature will find a way to utilize the resources at their disposal to acquire new strengths and shuck off major commitments that have high risk quotients for economic disaster. Some, like deep-water offshore development well projects with huge capital commitments cannot dodge return on investment disaster. The major profit source for petroleum producers is gasoline, refined from crude oil, consumed largely in the US by the transportation sector. When crude was priced above $100 a barrel (little more than a year ago) nat gas was quoted at $4.50-$5. Elaborate engineering tests quoted extensively by Wikipedia indicate equivalent miles per gallon operating costs on a wide variety of in-production automobiles to be 2 ½ times as costly for ICE gasoline-consuming vehicles as purely electric-drive vehicles. Annual fuel costs under average operating conditions were shown as $2,300 for popular present-day ICE cars and less than $1,000 for electric models. Since then, crude costs have declined from $100+ to under $50. Gasoline costs have declined less, from $4.50 a gallon to $3.50. Nat gas prices have declined from $5 to $2.30 in major exchanges, but in many areas they are quoted well under $2. To be more specific, with electricity costs declining and electrical utility presence pervasive geographically, fuel economics and environmental concerns will cause widespread auto conversions from internal combustion engines (ICE) with relatively low energy conversion efficiency from high-cost gasoline or diesel fuel to more efficient electrical motor-powered vehicles. Vehicles residentially fueled overnight by electrical power from Utilities using low-cost natural gas economically delivered to their generating stations by pipeline distribution systems from producing areas. Currently average new car purchase prices average $33,000 to $35,000. Most electric car models currently being offered or in development are priced or aimed at less than this, even before governmental promotion discounts of as much as $7,500. The current major inhibition is distance range. Most electric cars are limited to under 100 miles. The attempted marketing quick-fix is hybrid vehicles, basically still an ICE car, but with electric assist, touted as an electric car with an ICE recharging lifeboat when the volts are depleted. As long as a major part of the gullible consuming public will lease the hybrids or long term finance them, the conversion will be slow. But progress in battery development and increasing awareness of the reduced per-mile transportation cost of the bulk of everyday driving will hit the accelerator at some point. Then, fashion will move from the back seat into the driver’s position. At that point, the ICE and gasoline demand are threatened. Could Chevron (NYSE: CVX ) and Exxon Mobil (NYSE: XOM ) become a BTU? Why aren’t energy stocks ready to recover? Big-money investment funds are nibbling at diversified energy ETFs. That is evident in the risk/reward tradeoff signaled by Market-Maker (MM) hedging of volume (block) trades, often involving $1 million or more at a time. Present day markets can’t handle such trades “regular-way” (by automation or high-frequency trading algorithms) so the Market-Makers are called on to provide liquidity. That only happens where they can find a speculator to take on the risk, usually via a hedging deal, done thousands of times a day. Such hedging reveals just how far knowledgeable investors think the involved securities prices might go, both up and down. Figure 1 shows how major Exchange Traded Funds (ETFs) are currently being viewed by players in the game who have the money muscle to move prices. Figure 1 (Used with permission) In this map of upside to downside prospects, lower-right (green) is good, upper-left (red) is bad, and the dotted diagonal is where they balance. Location [8] is the Energy Select Sector SPDR ETF (NYSEARCA: XLE ). Its minimal downside and passable upside suggest prospects for a favorable tradeoff. To check that out, let’s see how the same crowd views each of XLE’s largest holdings. Figure 2 (Source: Yahoo Finance) XLE’s roundup of ten of the usual suspects brings in over 60% of its committed capital. When we put them to the test of what the market-making professionals think their big-$ portfolio-manager clients are likely to do next, Figure 3 tells an interesting story. Figure 3 (click to enlarge) Hedging actions by MMs in block trades on each of the major holdings of XLE and in XLE itself imply the prospective price ranges in columns (2) and (3). (5) is the upside of (2) above (4). (6) tells the typical actual stresses experienced in 3-month holdings following forecasts like today’s, encountered the sample number of times (12) in the past 5 years. (9) shows what the net gains of those experiences were, and (8) tells what proportion of them recovered from the traumas of (6) to bring home a profit. Now, let’s look at these quantities for the average of the ten largest XLE holdings, and compare those averages to what is expected of XLE. The (5) upside is supported, but there seems to be some anti-gravity legerdemain at work on the downside. Maybe it is because the small sample of 1 in (12) for XLE may not be as convincing as the average of 122 experiences for each of the ten holdings. Also, disturbing is the fact that barely half of the holdings were able to dig themselves out of the drawdowns back into a profit (9). Not a very magnificent profit at that, less than 1%, particularly when compared to the +10%+ earned by the 20 currently top-ranked equities in our daily list. There about 7 of every 8 positions was a winner. The implied upside recovery potential of the holdings lacks credibility (13) where (9) actual history of 0.8% is compared to (5) implied profit prospects of +12.2%. Is this all just fantasy, numbers sucked out of the thumb of some analyst? When things don’t fit together well, such concerns may be justified. We need to have some reassurance that this is not some ENRON or LIBOR situation. Figures don’t lie, but … we all know what has happened. I can tell you that there is evidence in the form of double-entry recorded actual exchange transactions in the hedging deals that can’t be faked. In addition, real money has been endangered to transfer risk from one party to another, and the trade initiator in each case has wanted badly enough to get his order filled to say that the cost of the price insurance required is not excessive enough to prevent him from paying it. Consenting adults from 3 directions form a financial menage-a-trois. Real life in the investment world often means someone is wrong and gets … disappointed. Conclusion There is enough rational discontinuity here to encourage serious thinkers to look elsewhere for profitable pursuits. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
HHYX: International Junk Bond Exposure With Protection From A Strong USD

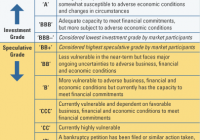
Summary IShares recently listed a new USD hedged high yield bond ETF. This fund is composed of Canadian dollar, British pound sterling, and Euro denominated corporate junk bonds. This fund may be useful to an investor looking for international fixed income exposure without the foreign exchange risk. The Fund On July 28th, iShares from Blackrock (NYSE: BLK ) listed a new ETF, the iShares Currency Hedged Global ex USD High Yield Bond ETF (NYSEARCA: HHYX ). As stated in the fund’s prospectus, this fund seeks to invest in corporate junk bonds …while mitigating exposure to fluctuations between the value of the component currencies and the U.S. dollar. HHYX seeks to track the Markit iBoxx Global Developed Markets ex-US High Yield (USD Hedged) Index . HHYX principally invests in another iShares fund, and/or the components of that fund, the iShares Global ex USD High Yield Corporate Bond ETF (BATS: HYXU ). The difference between the two is that, while both achieve exposure to non-USD denominated high yield bonds, only HHYX actually protects and hedges against the foreign exchange risk associated with international investing. In this article, I will briefly go over the components of the new fund and the structure of the currency hedging strategy used by this fund. Components Geography: The top five geographic areas of exposure in HHYX are: Italy (22.23%) United Kingdom (15.22%) Germany (14.87%) France (12.36%) Spain (5.97%) Investors may also note that 1.36% of the exposure comes from Greece. Remember that HHYX is strictly exposed to corporate junk bonds, and not municipal or government debt. That being said, I think most investors are aware that there is some concern in the market about the status of Italy’s debt levels. Sovereign debt is at an all time high in Italy, and there are some analysts saying that Italy will be the “next Greece.” For these reasons, I see the large exposure to Italy as one of the principle risks. Sectors: The most represented sectors in the fund are: Financials (18.85%) Telecommunication (17.10%) Capital Goods (16.91%) Consumer Cyclical (16.75%) Consumer Non-cyclical (9.40%) Grades: The primary credit ratings of the underlying investments are BB (63.67%) and B (30.71%). As far as where these credit ratings are derived from, iShares states that: Credit quality ratings on underlying securities of the fund are received from S&P, Moody’s and Fitch and converted to the equivalent S&P major rating category. From the S&P’s Credit Ratings website, here is how the various ratings are described: Of course, there are many risks associated with speculative grade junk bonds, but I will assume that if you are seeking exposure to them, then you have some understanding of these risks. How the Currency Hedge Works: In order to hedge against fluctuations of exchange rates between the USD and other currencies, HHYX shorts forward contracts for each of the non-dollar currencies in the portfolio. What this means is that if one of the underlying currencies in the portfolio loses value compared to the USD, the losses will be offset by the gains from the forward contracts. It is important to realize that the forward contracts will offset and limit, but not necessarily eliminate, losses from foreign exchange risk. It should be also noted that the inverse of this is also true. If the underlying currency of one of the portfolio’s investments gains value compared to the U.S. dollar, the gains would be offset by a loss from the forward contract. In other words, the investor would not benefit from the foreign exchange, whereas he or she would if they had purchased the asset using converted U.S. dollars. Conclusion: This article is not necessarily intended to encourage or discourage investors from investing in international high yield bonds. However, if one is inclined to do so, I believe that this new ETF is a reasonable way to gain exposure. I do have concerns about the large allocation towards Italian debt, but the underlying index could possibly rebalance if the situation deteriorated further. Arguably, it is a benefit that the fund is geared towards the higher-end of speculative grade debt. In short, if an investor is seeking to diversify his or her portfolio with exposure to international speculative grade corporate debt, this new ETF may be a worth further investigation. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article. Additional disclosure: This article is not intended to be a buy/sell recommendation, it is simply offered as an analysis of a new exchange traded product that some investors may find useful for their portfolios.

Another Most Competitive Wealth-Builder ETF Investment

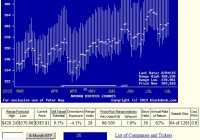
Summary From a population of some 350 actively-traded, substantial, and growing ETFs this is a currently attractive addition to a portfolio whose principal objective is wealth accumulation by active investing. We daily evaluate future near-term price gain prospects for quality, market-seasoned ETFs, based on the expectations of market-makers [MMs], drawing on their insights from client order-flows. The analysis of our subject ETF’s price prospects is reinforced by parallel MM forecasts for each of the ETF’s ten largest holdings. Qualitative appraisals of the forecasts are derived from how well the MMs have foreseen subsequent price behaviors following prior forecasts similar to today’s. Size of prospective gains, odds of winning transactions, worst-case price drawdowns, and marketability measures are all taken into account. Today’s most attractive ETF Is the iShares Nasdaq Biotechnology ETF (NASDAQ: IBB ) The investment seeks to track the investment results of an index composed of biotechnology and pharmaceutical equities listed on the NASDAQ. The fund generally invests at least 90% of its assets in securities of the underlying index and in depositary receipts representing securities of the underlying index. The underlying index contains securities of NASDAQ® listed companies that are classified according to the Industry Classification Benchmark as either biotechnology or pharmaceuticals and that also meet other eligibility criteria determined by the NASDAQ OMX Group, Inc. The fund is non-diversified. The fund currently holds assets of $9.04 billion and has had a YTD price return of +21.65%. Its average daily trading volume of 1,601,730 produces a complete asset turnover calculation in 15 days at its current price of $383.81. Behavioral analysis of market-maker hedging actions while providing market liquidity for volume block trades in the ETF by interested major investment funds has produced the recent past (6 month) daily history of implied price range forecasts pictured in Figure 1. Figure 1 (used with permission) The vertical lines of Figure 1 are a visual history of forward-looking expectations of coming prices for the subject ETF. They are NOT a backward-in-time look at actual daily price ranges, but the heavy dot in each range is the ending market quote of the day the forecast was made. What is important in the picture is the balance of upside prospects in comparison to downside concerns. That ratio is expressed in the Range Index [RI], whose number tells what percentage of the whole range lies below the then current price. Today’s Range Index is used to evaluate how well prior forecasts of similar RIs for this ETF have previously worked out. The size of that historic sample is given near the right-hand end of the data line below the picture. The current RI’s size in relation to all available RIs of the past 5 years is indicated in the small blue thumbnail distribution at the bottom of Figure 1. The first items in the data line are current information: The current high and low of the forecast range, and the percent change from the market quote to the top of the range, as a sell target. The Range Index is of the current forecast. Other items of data are all derived from the history of prior forecasts. They stem from applying a T ime- E fficient R isk M anagement D iscipline to hypothetical holdings initiated by the MM forecasts. That discipline requires a next-day closing price cost position be held no longer than 63 market days (3 months) unless first encountered by a market close equal to or above the sell target. The net payoffs are the cumulative average simple percent gains of all such forecast positions, including losses. Days held are average market rather than calendar days held in the sample positions. Drawdown exposure indicates the typical worst-case price experience during those holding periods. Win odds tells what percentage proportion of the sample recovered from the drawdowns to produce a gain. The cred(ibility) ratio compares the sell target prospect with the historic net payoff experiences. Figure 2 provides a longer-time perspective by drawing a once-a week look from the Figure 1 source forecasts, back over two years. Figure 2 (used with permission) What does this ETF hold, causing such price expectations? Figure 3 is a table of securities held by the subject ETF, indicating its concentration in the top ten largest holdings, and their percentage of the ETF’s total value. Figure 3 source: Yahoo Finance In contrast to the approach taken elsewhere of a wide net of holdings among early-development biotech companies, IBB focuses more than half its holding investments in strongly-resourced market-established companies serving flourishing product markets and related step-out demand opportunities. Each of these holdings frequently appears among our daily intelligence lists of the top 20 odds-on wealth-building stocks and ETFs out of an active population of 2,500+ securities. Figure 4 is a table of data lines similar to that contained in Figure 1, for each of the top ten holdings of XBI. Figure 4 (click to enlarge) In an industry as unpredictably dynamic as this, wide variations in market experience seem to be the rule. Column (5) contains the upside price change forecasts between current market prices and the upper limit of prices regarded by MMs as being worth paying for price change protection. The average of +10.7% of the top ten IBB holdings is above the average of our daily intelligence list ranking of the top 20 odds-on wealth-building stocks and ETFs. That population of 2500+ equities has ambitious MM upside price change forecasts of +12.6%. The IBB largest holdings prospects, according to the MMs is about 1 ½ times the upside forecast for SPY price change. The other side of the coin is column (6), which shows what actual worst-case price drawdowns have been typical in the 3 months following each time there has been a forecast like those of the present day. Those risk exposures have been only -6.7% in the holdings top ten, less than -8.6% by equities at large. But these holdings are attractive reward tradeoffs between returns and risks, with the top ten (column 14) at a ratio of 1.6, compared to equities overall at 1.5 times. The market-proxy of SPY provides a best ratio of 2.1 times risk avoidance, but is based on an upside of only +6.8%, deficient in comparison to the alternatives . Another qualitative consideration is the credibility of the ten IBB big holdings after previous forecasts like today’s. The net average price change (column 13) of the ten has been 0.8 times the size of the upside forecast average, +8.1% compared to +10.7%. The equity population’s actual price gain achievement, net of losses has been a pitiful +3.4% compared to promises of 12.6%. The ability of IBB holdings to recover from those worst-case drawdowns and achieve profits occurred in 81% of experiences. The equity population only recovered less than two thirds of the time, and while the SPY recovery experiences were more consistent like the ten IBB holdings, the achieved gains were much smaller. SPY has had only +3.7% gains previously from like forecasts of +6.8%. Conclusion IBB provides attractive forecast price gains, supported by equally appealing largest holdings. Both the ETF and many of its major holdings offer very attractive prospects in near-term price behaviors, demonstrated by previous experiences following prior similar forecasts by market makers. The ETF provides an excellent holdings balance to other biotech ETFs that cover early-stage developing companies. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.