Tag Archives: investing ideas

Will A Fidelity Select Funds Portfolio Perform Well In A Rising Interest Rates Environment?
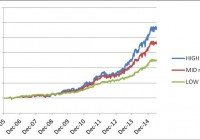
Summary Old portfolio: FBMPX, FSCHX, FSELX, FSPHX, FGMNX. New portfolio: FBMPX, FSCHX, FSELX, FSPHX, FIBIX, FSBIX. The new portfolio significantly outperforms the old one. In a previous article , we presented the performance of a portfolio made up of five Fidelity select mutual funds. That portfolio had a stellar performance over the whole 27-year period from 1987 to 2015, but we are concerned about its performance in a stock bear market within a rising interest rate environment. To increase its robustness for such events, we decided to replace the GNMA fund (MUTF: FGMNX ) with two high-quality government bonds. The portfolio is made up of the following funds: Fidelity Select Multimedia Portfolio No Load (MUTF: FBMPX ) Fidelity Select Chemicals Portfolio No Load (MUTF: FSCHX ) Fidelity Select Electronics Portfolio No Load (MUTF: FSELX ) Fidelity Select Medical Delivery Portfolio No Load (MUTF: FSHCX ) Fidelity Spartan Intermediate Trust Bond Index Fund Inv (MUTF: FIBIX ) Fidelity Spartan Short Term Trust Bond Index Fund Inv (MUTF: FSBIX ) Our old portfolio performed very well during the two big bear markets of 2000-03 and 2008-09. During those markets, the portfolio was invested mostly in the GNMA fund that experienced growth due to declining interest rates associated with economic contraction. But if a stock bear market happens while interest rates are rising, the GNMA fund most likely would not offer protection. We expect that a short-term government bond would allow the portfolio capital to be preserved during such adverse market environments. Due to their low sensitivity to interest rates, the short-term Treasury bonds act mostly as cash. Basic information about the funds was extracted from Yahoo Finance and is shown in the table below. Table 1 Symbol Inception date Net assets Yield% Category FSELX 7/29/1985 2.32B 0.47% Technology FBMPX 6/30/1986 803M 0.24% Consumer Cyclical FSPHX 7/14/1981 10.75B 1.90% Health FSCHX 7/29/1985 1.47B 1.02% Natural Resources FIBIX 12/20/2005 1.35B 1.90% Intermediate Term Treasuries FSBIX 12/20/2005 863M 0.76% Short Term Treasuries Since the historical price data of the bond funds is available only from December 2005 on, and we need 65 trading days for estimating market parameters, we were able to simulate our optimal allocation strategy starting with April 2006. We performed an analysis of the difference in performance of the old and the new portfolios. The data for the study were downloaded from Yahoo Finance , using the Historical Prices menu for FGMNX, FBMPX, FSCHX, FSELX, FSPHX, FIBIX, and FSBIX, respectively. We use the daily price data adjusted for dividend payments. The portfolio is managed as dictated by a variance-return optimization algorithm developed on the Modern Portfolio Theory ( Markowitz ). The allocation is rebalanced monthly at market closing of the first trading day of the month. In table 2 below, we present the performance of the new portfolio for three levels of risk. Table 2. Portfolio performance from April 2006 to June 2015 TotRet% CAGR% No. of trades maxDD% VOL% Sharpe Sortino Low risk 247.96 14.41 112 -8.02 8.81 1.63 2.27 Medium risk 363.25 18 108 -9.86 12.35 1.46 2.01 High risk 457.9 20.39 94 -13.26 15.01 1.36 1.9 SPY 91.37 7.26 0 -55.18 20.98 0.35 0.41 In figure 1, we show the graphs of the portfolio equities. (click to enlarge) Figure 1. Equity curves for three portfolios adaptively optimized for low-, medium- and high-risk targets. Source: This chart is based on EXCEL calculations, using the adjusted monthly closing share prices of securities. In figure 2 below, we show the time variation of the percentage allocation of the funds for medium risk. (click to enlarge) Figure 2. Asset allocations for the new portfolio adaptively optimized for the medium risk target Source: This chart is based on EXCEL calculations, using the adjusted monthly closing share prices of securities. In figure 2, it can be observed that during the bear market of 2008-09, most money was allocated to the intermediate-term bond fund, FIBIX. During the market corrections of 2010 and 2011, most money was allocated to the short-term bond fund, FSBIX. The current fund allocations are shown in table 3. Table 3. Asset allocations for July 2015 FSELX FBMPX FSPHX FSCHX FIBIX FSBIX Low risk 30% 70% 0% 0% 0% 0% Medium risk 0% 100% 0% 0% 0% 0% High risk 0% 100% 0% 0% 0% 0% We also simulated the performance of the old portfolio over the same time period from April 2006 to June 2015 and for the same risk levels. Consistently over the whole simulation period, the new portfolio outperformed the old one by about a 40% increase in annual returns and a 20% or more decrease in maximum drawdown. We compared the returns of the portfolios over the bear market of 2008 and the market corrections of 2010 and 2011. The results are shown in table 4. Table 4. Total returns of the portfolios during market downturns Time Period SPY Old Portfolio New Portfolio 12/2007 – 3/2009 -48.92 -11.08% 9.74% 3/2010 – 7/2010 -10.95 -5.75% -0.30% 4/2011 – 9/2011 -16.22 -1.59% 15.51% From table 4, it is clear that the new portfolio performs better than the old one, and that it is very robust to market downturns. Unfortunately, there were no long enough periods of rising interest rates to allow us to make any judgment about the behavior of the portfolios during such times. It is our belief that in a long period of rising interest rates, the new portfolio will suffer only small losses by parking the money in the short-term bond fund. Conclusion The modified Fidelity portfolio performed significantly better than the old one. It even made gains during the 2008 bear market and the 2011 market correction. While there is no empirical data to prove it, we believe that the new portfolio is robust and will perform well even during a prolonged period of rising interest rates. Disclosure: I am/we are long FSELX, FSPHX. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
A 13.7% Yield From GreenHunter Resources Preferred Shares

GRH’s oilfield waste water disposal business is running at full capacity and expanding rapidly despite low oil and natural gas prices. GRH-PC is a cumulative preferred issue that now yields 13.7%. Gary Evans has successfully built valuable midstream assets at MHR and is doing the same thing at GRH. GreenHunter Resources (NYSEMKT: GRH ) was initially formed by Magnum Hunter founder Gary Evans with the goal of developing alternative energy sources. The company soon realized that biomass and other “green” energy technologies were unprofitable and has exited that business. GRH is now focused on developing cost effective and environmentally friendly oilfield fluid management solutions. GRH-PC is a par $25 cumulative preferred convertible issue. GRH-PC has a 10% coupon and dividends are paid monthly. It now yields 13.7% at a recent price of $18.25. See prospectus for additional details. GRH-PC dividends were classified as Return of Capital for 2014, which provides some tax advantages. ROC dividends lower your cost basis, but are not taxable as income when received. Given that GRH has accumulated substantial tax losses, GRH-PC dividends are likely to remain ROC for quite some time. Why is GRH’s oilfield waste water disposal business running at full capacity (turning away business in fact) even with low oil and natural gas prices? GRH initially developed operations in several regions, but made the wise strategic decision to focus on Appalachia. Disposal wells in other regions were sold and equipment was moved. This resulted in lower Q1 revenues, but paves the way for future profitable growth. Appalachia is a region where the permitting of disposal wells is a difficult and lengthy process. Waste water must often be trucked for long distances at high cost to be properly disposed of. The scarcity of attractively located disposal wells and the difficulty in building more is a key competitive advantage for GRH. Many GRH customers have signed “take or pay” contracts. They are required to pay for access to the company’s disposal capacity, even if they don’t actually use it. GRH serves customers in the Utica and Marcellus fields. These are among the best fields with the highest returns on drilling. Drilling reductions have been less severe for the Utica and Marcellus fields than for other regions with higher production costs. GRH is doing some innovative things that are years ahead of its competitors. Several new disposal wells are coming online over the next few months that are expected to increase their water disposal capacity by about 50%. These wells are being connected to a central offloading terminal by a network of wastewater pipelines. This is an extremely efficient system that will give GRH a significant cost advantage. GRH has also been building a network of barging terminals along the Ohio River and expects to start barging waste water to their central disposal terminal later this year. Barging is a great solution for the pollution and traffic problems associated with trucking. Note that barges are already being used to transport oil and other cargos that are far more hazardous than oilfield water. GRH estimates that barging is about 25% cheaper than trucking. Ironically, barging has been opposed by some “environmentalists.” Some extremists believe we should shut down virtually all oil and natural gas production, but this is just not practical. GRH is developing the right infrastructure for the safe, cost effective and environmentally friendly disposal of waste water. What are the advantages of owning the GRH-PC preferred stock as compared to the GRH common stock? While GRH is building some unique and valuable midstream assets, it’s been a painful growth process for common stockholders. Preferred holders have continued to receive generous monthly dividends while the GRH common has been diluted to raise additional capital. The preferred dividend was maintained even when cash got extremely tight. Fortunately liquidity has improved greatly as GRH closed a new $16 million secured credit facility on 4/15/2015. Cash flow has been challenging for GRH, but should also improve dramatically over the next few quarters as new disposal wells and barging come online. GreenHunter Resources was founded by Gary Evans and he controls a majority of the GRH common stock. The preferred stock is senior to the common stock, so it’s comforting to know that insiders have such a large stake in the company. Gary Evans is better known for founding Magnum Hunter Resources (NYSE: MHR ). MHR also has a strong record of continuing to pay preferred dividends even when liquidity gets tight ( see my recent MHR article ). The MHR preferred issues rallied when MHR announced plans to sell some of their midstream assets for $600 million-$700 million. Many of my newsletter subscribers (see additional article disclosure) are long-time investors in the MHR preferred issues and were not surprised to see Gary Evans come through. GRH-PC is a smaller issue and is not nearly as well known as the MHR preferred issues. Gary Evans has already shown a knack for building valuable midstream assets at MHR and appears to be doing it again at GRH. MHR preferred stock investors should consider the “other” Gary Evans yield play. Editor’s Note: This article covers one or more stocks trading at less than $1 per share and/or with less than a $100 million market cap. Please be aware of the risks associated with these stocks. Disclosure: I am/we are long GRH-PC,MHR-PD. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article. Additional disclosure: The author is the publisher of the Panick Value Research Report. The Panick Report is focused on high yield preferred stock issue, email mrpanick@yahoo.com for the 2 week free trial.

The ProShares USD Covered Bond ETF: Covering All The Bases

One of the few ways for a retail investor to participate in the covered bond market. The fund features U.S. Dollar denominated AAA rate covered bonds. The fund is actively managed, with total annual expenses of 0.35%. Anyone who knows the game of baseball will tell you that in order to play effective defense, the team must know how to keep the bases covered at all times. It’s not as simple as it sounds. It depends on the baserunners, on what bases and then what to do on the next pitch. Covering all the bases carries over to investing and choosing a fund while keeping that well-worn baseball axiom in mind. According to European Covered Bond Council : …Covered bonds are debt instruments secured by a cover pool of mortgage loans (property as collateral) or public-sector debt to which investors have a preferential claim in the event of default… In other words a covered bond is a bond whose cash flow originates from other bonds or loans called a ‘cover pool’. This might remind some investors of the infamous ‘collateralized’ or ‘securitized’ mortgage backed securities, but covered bonds are not that. First, a covered bond is not an ‘off-balance-sheet’ asset. It is an obligation kept on the balance sheet of the issuer; it is a ‘bond’ in every way. The issuer bears full accountability for the bond and the payments. In other words, the bondholder has full recourse to the issuing credit institution, if need be. Second, the bondholder also has a claim to the covered pool, senior to unsecured creditors. Third, it is the responsibility of the issuer to maintain sufficient assets in the cover pool to satisfy the claims of bondholder during the life of the bond. Lastly, to be able to issue a covered bond, the issuing institution must be an accredited, regulated institution. What it amounts to is that all the bases are covered. At this point, it’s necessary to mention a little known general fact about bonds: a bond may be issued in a currency other than the issuer’s sovereign currency. So, for example, an accredited, regulated European institution may issue U.S. Dollar denominated bonds , even if the native currency is the Euro. There are various reasons for this. For example, a U.S. Dollar denominated bond might be intended for a particular segment of the U.S. market; a pension fund for instance. Also, advanced economy nations may issue foreign denominated bonds as part of a trade agreement. This is particularly true of emerging market nations trying to attract foreign, fixed capital investment. Most importantly, a foreign denominated bond is a hedge against originating currency volatility. One other critically important characteristic of this fund is that does not choose yield over risk. ProShares USD Covered Bonds ETF, ” focuses exclusively on the highest rated U.S. Dollar denominated bonds ” and ” is the only corporate bond fund in the United States with substantially all of its assets rated AAA. ” Thus the fund has an added measure of safety in a financial world rife with unsound fixed income investments. The fund first traded in May of 2012 and has been consistent on returns with a steady Net Asset Value as well as a steady flow of monthly distributions. (click to enlarge) The average dividend return for 2012 was $0.085491 per month for the 7 months of the fund’s inception year. In 2013 the average dividend was $0.0821472 per month; in 2014 it was $0.0847515 per month and for 2015 $0.0930747, to 7/1/15. Hence the dividend has been consistent since inception. The average NAV since inception is $101.42368 and the June 19 NAV close $101.53, hence about 0.108% above its average and 1.53% above its inception value. The dividends paid since inception total $3.159669 on the $100.25 per ETF share, or 3.1517895%, if purchased on the inception date. This is in comparison with the 3 year U.S. Treasury note’s 0.41% and the 30 year U.S. Treasury bond’s 2.80% secondary market yields on the fund’s inception date of 5/21/2012. Hence this fund with its AAA, rating had a better yield, to date, than a 30 Year U.S. Treasury bond if purchased on the same date. (click to enlarge) Dividend Distributions chart: data from ProShares The ETF market shares have returned -1.546% since inception, as of the June 29, 2015 close. This means that, currently, the market shares are trading well below the NAV, meaning the shares are selling at a 2.67% discount to the NAV. This is a rare event. The share price has traded at a discount on only 40 of the 785 days since inception or 3.82% of the time. It has traded at a premium on 96.13% or 745 days over the life of the fund. It’s possible that the ETF shares are selling at a discount to the NAV on expectations that the U.S. Fed is expected to tighten. If this is the case, the investor must consider the U.S. Feds plan to raise by small increments. The Maturity Distribution Chart demonstrates that the largest portion of the covered pool, 55%, is held in 2 to 4 year bonds, and 34% in 0 to 2 year bonds. Since the fund is actively managed , the higher likelihood it will anticipate and adjust quicker than a rules based passively managed fund. It is interesting to note the fund’s performance during the global bond selloff from about the middle of April until the beginning of June. The NAV closed at a high of $102.10 on April 15, paid a dividend of $0.087976 on May 11, $0.101797 on June 9 and closed at a low of $101.04 on June 10, averaging 101.57, or about $0.15 above its average since inception. The average dividend paid was $0.09489, $0.01274 above its average since inception. The ETF share price closed at a high of $102.15 on April 22 and closed at a low of $99.39 on June 8 a decline 2.70%, or $2.76 from the April high. Most recently, the ETF shares closed at $98.70 on July 1, while its calculated NAV as of July 1, was $101.41. It’s important to note then, the market shares are trading well below the NAV, a discount of -2.67%. This is a rare event. The share price has traded at a discount on only 30 of the 740 trading days since inception or 4.05% of the time. It has traded at a premium on 95.95% or 700 trading days over the life of the fund. There are currently 25 covered bonds in the fund, and a cash position of $48285.95. The weighted average yield to maturity is 1.48%. The trailing twelve month yield is 1.06% and the annualized yield based on the last distribution is 1.18%. The fund’s net assets as of June 19 are $6.563 million. It’s worth noting that the tracking index is comprised of 44 issues, has a weighted average maturity of 3 years, a weighted average yield to maturity of 1.52%. This indicates that this actively managed fund is more efficient than the unmanaged index. Almost all of the covered bonds are “144A” bonds. Investopedia defines SEC Rule 144A a modification of: … a two-year holding period requirement on privately placed securities to permit qualified institutional buyers to trade these positions among themselves … In other words, the rule creates a more liquid market for these securities. The fund’s largest holding is Australia’s Westpac Banking Corp (NYSE: WBK ) 144A 1.850% due 11-26-18. According to Westpac, its covered bond rating by Fitch is AAA and by Moody’s, Aaa. Just as a side note, a Seeking Alpha contributor Donald van Deventer recently updated his analysis of Westpac Banking Corporation noting that: … Westpac Banking Corporation has continued to be a prominent bond issuer in international markets… The bank ranks in the safest 10% of the world-wide banking peer group for default probability maturities of 5 years or more, but the banking sector is a risky one … The second largest market value holding is The Royal Bank of Canada’s (NYSE: RY ) 144A 2% due 10/1/18. Moody’s rating of the bank’s covered bond program is Aaa and Fitch ranks it at AAA. SpareBank ( OTC:SRMGF ) is a Norwegian Bank which, coincidentally, specializes in covered bond issuances. The cover pool consists of high quality single family residential mortgages. It must be emphasized that these are not securitized or collateralized off-balance-sheet debt instruments, but actual bonds for which the issuer bears full responsibility. Further, in the aftermath of the global credit bubble, the financial and legal consequences suffered by the rating agencies served to strengthen the quality of analysis and that of ratings. SpareBank 1 Boligkreditt mortgage-cover-pool, covered bonds, are rated Aaa by Moody’s and AAA by Fitch. Stadshypotek AB , is a Swedish mortgage lender and subsidiary of Svenska Handelsbanken ( OTCPK:SVNLY ), whose covered bond program receives an Aaa rating from Moody’s. Since it is a subsidiary, it should be noted that S&P rates the issuer Stadshypotek AA-; Fitch AA-, and lastly Handelsbanken receives ratings of AA- from S&P, Aa3 from Moody’s and AA- from Fitch. ING Groep (NYSE: ING ) of Netherlands, has a global reach but is mainly a European based bank. Their 144a 2.625% coupon, due 12/5/2022 receives Aaa from Moody’s, AAA from S&P and AAA from Fitch. ING’s ‘hard-bullet’ covered bonds are backed by Dutch Prime Residential Mortgages, the Dutch legal standard for mortgage cover pools. Covered Bond ETFs are a rarity in the ETF universe. iShares offers an investment grade , Euro denominated, Covered Bond ETF (ICOV.LN). The returns on the holdings are better, but the description refers to ‘ investment grade ‘ investments, meaning BBB or higher. Lastly, U.S. based Pimco in cooperation London based Source also markets a covered bond ETF (COVR:XTER) however it trades on the German DAX and in Euros. To some up, the ProShares USD Covered Bonds ETF (NYSEARCA: COBO ) offers investors a way to participate in an asset class not accessible to individual retail investors. Further, the fund has a strong bias towards highly rated covered bonds with the best possible yields. Further, the high rating bias extends to the ‘cover pool’ of securities. The fund’s performance during the recent global bond market correction demonstrated its stability. The ETF shares did lose value but the Net Asset Value of the fund remained well within its long term deviation, thus creating a discount arbitrage for the shares vs the NAV. According to the prospectus , the fund is actively managed by ProShares Advisors and the total fees, expenses waivers and reimbursements result in total operating expenses of 0.35%. If it’s expected that low rates of return are to be the new normal, this may be a good opportunity to earn surprisingly good returns and very high degree of safety. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.