Tag Archives: management

Adams Express Is Proof That Closed-End Funds Can Survive Big Dividends

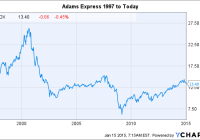
Closed-end fund ADX has been around since 1929. It’s paid dividends continuously since 1935. Since 1997, it’s paid $18 out in distributions—more than $5 more than it’s share price on 1/1/97. Adams Express Company (NYSE: ADX ) is something of an outlier in the closed-end fund, or CEF, world. It was founded in 1929 and, unlike most of its peers, is a stand alone company without a parent. What’s most impressive, however, is that Adams Express has long paid large dividends to shareholders and lived to tell about it. Proof that closed-end funds can pay worthwhile dividends and not self liquidate. A buyout that started it all Adams traces its current form back to World War I. It had been in the business of moving parcels, but was essentially shut out of the local mail angle of that by the government and the United Postal Service. Then, during the War, its business moving parcels by rail was taken over by the government. While it received nothing when the Post Office put it out of business delivering mail, in return for its rail express business it received shares in a company called American Railway Express Company. After the war those shares would be sold to the major railroads, leaving Adams with a lot of cash and, well, no business. That was when Adams Express shifted gears and became a closed-end fund. Oddly enough, that change took place pretty much right before the 1929 market crash and start of the Great Depression. At that point, the CEF had around $73 million. Today , the fund’s value is in the area of $1.5 billion. It started paying dividends, meanwhile, in 1935 and has done so continuously ever since-including through the depths of the 2007 to 2009 “great recession.” One important difference between Adams Express and most other closed-end funds is that it really is a separate company. In fact, the CEO is also the fellow who heads up its research and investing efforts. Most closed-end funds don’t have this type of independence, with a sponsor company like Eaton Vance (NYSE: EV ) calling all the shots and being paid to manage the fund. The fund’s day to day managers, meanwhile, usually work for the sponsor or another asset manager hired by the sponsor. Apples and Oranges? So, in some ways, it isn’t fair to make a direct comparison between Adams Express and other closed-end funds. Although that comparison isn’t exactly apples and oranges, it could easily be like comparing a Red Delicious to a Granny Smith. They are both apples, for sure, but they are vastly different other than that. That said, one thing that Adams proves is that dividends and closed-end funds can go very well together over long, long periods of time. In fact, more than 75 years . And the numbers are pretty amazing when you do some simple math. ADX data by YCharts Between 1997 and 2014 , Adams Express paid out $18 a share in distributions. The CEF traded hands for around $13 a share on January 1, 1997. And while the price has gone through its share of ups and downs over that 18-year span, that’s $5 more in distributions per share than what you would have paid to buy a share at the start of the period. Recently, the shares have been trading hands at around $13.50. That’s a pretty impressive feat. How did it do that? The thing about Adams Express’ dividend that helps make this possible is that it’s variable. Over that 18-year period the distribution was as high as $1.85 (2000) and as low as $0.45 (2009). So there should be no expectation of a steady payout here. In fact, the relatively new policy of paying out 6% of net assets a year in distributions means the payment will vary with performance. Many closed-end funds today use a managed or level distribution policy that ensures a high yield. Investors seeking income like this and often jump aboard for the income without much consideration for anything else. However, overly high payouts can lead to a slow bleed of net assets to shareholders. A quicker bleed in bad years. For long-term investors that could be a problem and means distribution policy is one of the most important things to consider. While a variable policy can leave you short of cash in weak markets, it can also ensure your investments keep paying you down the road. Another thing about Adams that is unique is a very low expense ratio . At around 0.6%, it’s similar to some of the more exotic, perhaps esoteric, exchange traded funds. That’s pretty cheap and helps to boost performance over long periods. Expenses are another important issue to keep an eye on for long-term investors. Not a recommendation, but… This isn’t meant to be a recommendation of Adams Express (I’ll write a more formal review shortly). It is more to hold up an example of a closed-end fund that has paid shareholders well via distributions and hasn’t slowly liquidated itself. That slow bleed is one of the concerns I read about most frequently in comments to CEF articles. And while most CEFs aren’t made of the same stuff as Adams Express, this quirky old bird still proves an important point about closed-end funds and dividends.

DGRW Is A Solid ETF In Every Metric, But Still Faces An Uphill Battle

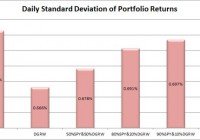
Summary I’m taking a look at DGRW as a candidate for inclusion in my ETF portfolio. The risk level on the ETF looks good with heavy trading volume. The yield is lower than I would expect for an ETF focused on dividend growth. The exposure to oil companies might be a bit much when I’m also planning a portion of my portfolio for natural resources. I’m not assessing any tax impacts. Investors should check their own situation for tax exposure. How to read this article : If you’re new to my ETF articles, just keep reading. If you have read this intro to my ETF articles before, skip down to the line of asterisks. This section introduces my methodology. By describing my method initially, investors can rapidly process each ETF analysis to gather the most relevant information in a matter of minutes. My goal is to provide investors with immediate access to the data that I feel is most useful in making an investment decision. Some of the information I provide is readily available elsewhere, and some requires running significant analysis that, to my knowledge, is not available for free anywhere else on the internet. My conclusions are also not available anywhere else. What I believe investors should know My analysis relies heavily on Modern Portfolio Theory. Therefore, I will be focused on the statistical implications of including a fund in a portfolio. Since the potential combinations within a portfolio are practically infinite, I begin by eliminating ETFs that appear to be weak relative to the other options. It would be ideal to be able to run simulations across literally billions of combinations, but it is completely impractical. To find ETFs that are worth further consideration I start with statistical analysis. Rather than put readers to sleep, I’ll present the data in charts that only take seconds to process. I include an ANOVA table for readers that want the deeper statistical analysis, but readers that are not able to read the ANOVA table will still be able to understand my entire analysis. I believe there are two methods for investing. Either you should know more than the other people performing analysis so you can make better decisions, or use extensive diversification and math to outperform most investors. Under CAPM (Capital Asset Pricing Model), it is assumed every investor would hold the same optimal portfolio and combine it with the risk free asset to reach their preferred spot on the risk and return curve. Do you know anyone that is holding the exact same portfolio you are? I don’t know of anyone else with exactly my exposure, though I do believe there are some investors that are holding nothing but SPY . In general, I believe most investors hold a portfolio that has dramatically more risk than required to reach their expected (under economics, disregarding their personal expectations) level of returns. In my opinion, every rational investor should be seeking the optimal combination of risk and reward. For any given level of expected reward, there is no economically justifiable reason to take on more risk than is required. However, risk and return can be difficult to explain. Defining “Risk” I believe the best ways to define risk come from statistics. I want to know the standard deviation of the returns on a portfolio. Those returns could be measured daily, weekly, monthly, or annually. Due to limited sample sizes because some of the ETFs are relatively new, I usually begin by using the daily standard deviation. If the ETF performs well enough to stay on my list, the next levels of analysis will become more complex. Ultimately, we probably shouldn’t be concerned about volatility in our portfolio value if the value always bounced back the following day. However, I believe that the vast majority of the time the movement today tells us nothing about the movement tomorrow. While returns don’t dictate future returns, volatility over the previous couple years is a good indicator of volatility in the future unless there is a fundamental change in the market. Defining “Returns” I see return as the increase over time in the value known as “dividend adjusted close”. This value is provided by Yahoo. I won’t focus much on historical returns because I think they are largely useless. I care about the volatility of the returns, but not the actual returns. Predicting returns for a future period by looking at the previous period is akin to placing a poker bet based on the cards you held in the previous round. Defining “Risk Adjusted Returns” Based on my definitions of risk and return, my goal is to maximize returns relative to the amount of risk I experienced. It is easiest to explain with an example: Assume the risk free rate is 2%. Assume SPY is the default portfolio. Then the risk level on SPY is equal to one “unit” of risk. If SPY returns 6%, then the return was 4% for one unit of risk. If a portfolio has 50% of the risk level on SPY and returns 4%, then the portfolios generated 2% in returns for half of one unit of risk. Those two portfolios would be equal in providing risk adjusted returns. Most investors are fueled by greed and focused very heavily on generating returns without sufficient respect for the level of risk. I don’t want to compete directly in that game, so I focus on reducing the risk. If I can eliminate a substantial portion of the risk, then my returns on a risk adjusted basis should be substantially better. Belief about yields I believe a portfolio with a stronger yield is superior to one with a weaker yield if the expected total return and risk is the same. I like strong yields on portfolios because it protects investors from human error. One of the greatest risks to an otherwise intelligent investor is being caught up in the mood of the market and selling low or buying high. When an investor has to manually manage their portfolio, they are putting themselves in the dangerous situation of responding to sensationalistic stories. I believe this is especially true for retiring investors that need money to live on. By having a strong yield on the portfolio it is possible for investors to live off the income as needed without selling any security. This makes it much easier to stick to an intelligently designed plan rather than allowing emotions to dictate poor choices. In the recent crash, investors that sold at the bottom suffered dramatic losses and missed out on substantial gains. Investors that were simply taking the yield on their portfolio were just fine. Investors with automatic rebalancing and an intelligent asset allocation plan were in place to make some attractive gains. Personal situation I have a few retirement accounts already, but I decided to open a new solo 401K so I could put more of my earnings into tax advantaged accounts. After some research, I selected Charles Schwab as my brokerage on the recommendation of another analyst. Under the Schwab plan “ETF OneSource” I am able to trade qualifying ETFs with no commissions. I want to rebalance my portfolio frequently, so I have a strong preference for ETFs that qualify for this plan. Schwab is not providing me with any compensation in any manner for my articles. I have absolutely no other relationship with the brokerage firm. Because this is a new retirement account, I will probably begin with a balance between $9,000 and $11,000. I intend to invest very heavily in ETFs. My other accounts are with different brokerages and invested in different funds. Views on expense ratios Some analysts are heavily opposed to focusing on expense ratios. I don’t think investors should make decisions simply on the expense ratio, but the economic research I have covered supports the premise that overall higher expense ratios within a given category do not result in higher returns and may correlate to lower returns. The required level of statistical proof is fairly significant to determine if the higher ratios are actually causing lower returns. I believe the underlying assets, and thus Net Asset Value, should drive the price of the ETF. However, attempting to predict the price movements of every stock within an ETF would be a very difficult and time consuming job. By the time we want to compare several ETFs, one full time analyst would be unable to adequately cover every company. On the other hand, the expense ratio is the only thing I believe investors can truly be certain of prior to buying the ETF. Taxes I am not a CPA or CFP. I will not be assessing tax impacts. Investors needing help with tax considerations should consult a qualified professional that can assist them with their individual situation. The rest of this article By disclosing my views and process at the top of the article, I will be able to rapidly present data, analysis, and my opinion without having to explain the rationale behind how I reached each decision. The rest of the report begins below: ******** (NASDAQ: DGRW ) WisdomTree U.S. Dividend Growth Fund Tracking Index: WisdomTree U.S. Dividend Growth Index Allocation of Assets: 80% Invested in components of the index or other securities that are considered to be almost identical Morningstar Category: Large Blend Time period starts: June 2013 Time period ends: December 2014 Portfolio Std. Deviation Chart: (click to enlarge) (click to enlarge) Returns over the sample period: (click to enlarge) Correlation: 96.34 Liquidity: 498,146 average shares/day Days with no change in dividend adjusted close: 10 Yield: 1.77% Expense Ratio: .28% Discount or Premium to NAV: .23% premium Holdings: (click to enlarge) Further Consideration: Yes. I am planning to allocate a portion of my portfolio to focus on dividend growth stocks because I want them to be over-weighted in my portfolio. Conclusion: DGRW doesn’t offer much in the way of diversification with a correlation that is over 96% and 10 days with no change in dividend adjusted close. There were only 2 days where SPY reported no change in dividend adjusted close during the same period. DGRW having 10 days rather than 2 may simply be a rounding error because DGRW trades around $31 to $32 and SPY is trading at over $200. A one cent movement in DGRW is similar to a six cent movement in SPY. The liquidity based on shares/day combined with the relatively low standard deviation results in an ETF that should fit nicely into portfolios that are requiring some liquidity. However, the distribution yield of 1.77% (lower than SPY’s 1.87%) is interesting for an ETF that suggests dividends are a primary focus. The expense ratio isn’t too bad and wouldn’t be enough to scare off, though I would prefer to buy closer to NAV since I expect to rebalance frequently which makes spreads and premiums or discounts more important to my strategy. With this much liquidity I would expect spreads to remain fairly small whenever the market is open and I would expect the premiums to disappear fairly fast. My biggest concern on this ETF would probably be the concentration of holdings. I don’t mind having a large position in Exxon Mobil, but I may be creating that position through an ETF that focuses on exposure to natural resources. Since I intend to include sections for a replacement for SPY and an allocation to an ETF that focuses on dividends, there will naturally be some significant exposure coming from three ETFs, but I’d like to keep the company specific risk as low as possible so that no company can compose more than 2 to 3% of my portfolio. Since the yield on the ETF is relatively low and it substantially overlaps with other positions I intend to create, I think it will face a slightly uphill battle despite being attractive ETF. As shown from the ending Portfolio Value, the high correlation also has a very similar total return. That isn’t always the case when using daily standard deviation, but it has been the case for DGRW. Comments I’m testing a new layout for my ETF articles. It is intended to optimize the articles for my followers. Let me know what you think of the new layout in the comments section. I’m always looking for feedback and trying to find ways to improve my writing for my readers.

Are Housing Stocks Ready To Rock Or Roll Over?

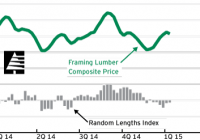
Housing stocks have begun to recover from the bubble and crash of last decade. Some individual homebuilders have attractive fundamentals, but none of the stocks are cheap. Some difficult portents from industry leaders make me wary of the sector for the short term. Longer term, positive factors may come together to make the sectors lead the market once more. Background : With the declining trend in interest rates reasserting itself, this is a good time to discuss a highly rate-sensitive industry, housing. Housing stocks consist of homebuilders (NYSEARCA: ITB ) and also related companies such as lumber stocks, home improvement chains, furniture companies. These are included along with home builders in another large ETF (NYSEARCA: XHB ). ITB and XHB tend to move together; the latter has been stronger since inception and for the past five years. This article reviews several identifiable factors that can be used to make an informed decision about the housing sector, and discusses individual companies within it. Introduction : Since the way houses are built change gradually rather than through breakthroughs such as the GUI and iPhone introduced over the years by Apple (NASDAQ: AAPL ), and because houses are core to human life, they can be great businesses. These stable characteristics have attracted Warren Buffett’s Berkshire Hathaway (NYSE: BRK.A ) (NYSE: BRK.B ) into the business of building and selling homes, manufacturing carpet, and other related businesses. That said, housing is subject to many cycles of different duration, and it used to be said that all housing was local and was not likely to allow the growth of large, geographically-diversified homebuilding companies. Thus, housing stocks go in and out of favor with some regularity. In 1999 and 2000, I used to exclaim to Mrs. DoctoRx that the housing stocks were in such disfavor, trading at such low valuations, that there was no way that the stock market was a valid discounting mechanism – not with Cisco (NASDAQ: CSCO ) at 150X P/E and Yahoo! (NASDAQ: YHOO ) at 100X sales per share at the peak. And so it was that Mr. Market changed his tune, got tired of the techs, and pumped up the housing stocks. I then did very well buying homebuilders in the up-cycle beginning in or around 2002, often for tangible book value – which had started to rise rapidly as the housing bubble inflated. So the stocks did well for us. In the spring of 2005, I was lucky enough to be watching CNBC one morning when an official from the Office of the Comptroller of the Currency came on and warned the public that certain mortgage practices had gotten dangerous. I sold my homebuilder stocks promptly, shortly before they all peaked that summer, and now own just one. My view is that if America is to keep on succeeding, housing must be a big part of that success, so it’s important for a diversified investor to be there when the sector really returns to strength. Let’s look into some of the straws in the wind that could tell us whether now is a good time to find alpha in ITB, XHB or any individual name in or related to those indices. We’ll start by looking to see if lumber products are in uptrends or not. Lumber and panel prices – the trends : An industry weekly, Random Lengths , lets us see yoy trends. This is the latest data: Framing lumber: And structural panels (composites): Not bad. Framing prices are down modestly yoy, but panels are up several per cent. Lumber is also traded on futures exchanges. FINVIZ tracks it: (click to enlarge) This looks less inspiring; there are of course different grades of lumber, and the Random Lengths data is probably more representative. Therefore, my impression is so far, so good. Wood products looked at on a one-year time frame look OK, certainly much better than the average commodity, but since those crashing commodities have a great deal to do with China’s and Europe’s problems, and wood is largely related to domestic demand, it’s hard to be enthusiastic. A longer-term look at lumber prices is more troubling. It looks to me like a classic convex downward topping pattern following the stimulation of the market during 2013’s QE 3 and then a failing set of rallies as the Taper went to its end. Here’s a multi-year look, from the “weekly” setting on the same FINVIZ link: (click to enlarge) Everyone’s eyes will see this differently, but I see it as tracking the recent cycle of stimulus being applied (QE 3 in 2013) and then being withdrawn (the Taper of QE 3 in 2014). So my guess here is toward the negative for what lumber’s chart may be portending. It’s just a guess, though. Let’s look at other data to see how the builders are faring. Homebuilders – recent results : There is actually a fairly consistent pattern here that suggests that demand has been pulled forward a bit, that prices have exceeded the buying power of those who would buy if they could, and that the stocks may therefore be in some trouble. Note I’m going to focus on the builders, as they tend to set the pace for the rest of the XHB. KB Home (NYSE: KBH ), the old Kaufman & Broad, created a contretemps this week. They reported a strong quarter but then on the conference call had some negative comments about the current quarter. The stock simply tanked. It peaked along with lumber prices in the spring of 2013 and now is down close to 50% from that peak. It is down roughly 80% from its mid-2005 peak. Hovnanian Enterprises, Inc. (NYSE: HOV ), which threatened to go bankrupt in last decade’s crash, survived to have a decent October. Nonetheless, its EPS prospects have darkened and it trades at nearly 20X current year EPS estimates given how much they have been cut. With negative book value, HOV could be in trouble. This is what one typically sees after a bubble bursts, and that companies survive on the edge like Hovnanian makes life more difficult for the healthier ones. Toll Brothers (NYSE: TOL ), which is the builder I own a bit of, also reported recently. TOL has a book value of $3.8 B, all of which is tangible book. Because of its exclusive only on higher-end homes and its long history as a market leader in that higher-margined niche, I believe that TOL has substantial intangible value. It ought to be a potential acquisition candidate for Berkshire Hathaway. Nonetheless, despite reporting a “beat” for the October quarter, TOL has seen EPS estimates for its FY ending Oct. 2015 drop about 10%. The stock is off its 12-month high but is much closer than KBH or HOV to its all-time high near $60. I take this as a sign of strength. TOL is selling at about 17X forward 12-month estimates, which are not set in stone. But at about 1.6X book value, it is solidly within a long-term buy-and-hold range, given that apart from the nonsense of 2004-5, it typically trades between 1X and 2X book value. I like TOL for the long haul. Lennar (NYSE: LEN ) reports Thursday (I am writing this Wednesday night). Like TOL, it has a relatively strong chart and could be a differentiated star in the next up-cycle. One other large builder that I like, which has had a little bit of mismanagement in at least one region, but has a stock that has uniquely lifted into all-time high territory is NVR (NYSE: NVR ). That it is in ATH ground is by itself reason to follow this name. NVR’s price:book is distorted by massive shrinkage of its float before the Great Recession. Periodically, NVR sees nice insider buying, and every once in a while, I trade it – but I don’t love its valuation enough to make it a core holding. Other larger builders, such as MDC Holdings (NYSE: MDC ) have declining EPS and declining estimates. So the sector has mixed prospects without any clear uptrend despite the interest rate downtrend the entire last twelve months. This situation does not merit a high, or necessarily any, allocation from smaller investors and usually does not encourage large investors to overweight the sector. Interest rates and general valuation issues : The periods of dropping interest rates which followed the ends of QE 1(mid-2010) and QE 2 (Q3 2011) were not good periods for ITB or XHB. We are here again and something similar looks to be happening; this pattern merits close attention to see if it in fact evolves similarly. This is another reason that I am cautious about the stocks right here. Given how low mortgage rates already are, there is no reason that they should have to drop any further to stimulate boom times for the housing sector. Unfortunately, through no special fault of the builders, the first-time home buyer is too often living in his/her parent’s home or else is renting, unable to scrape together even a 3% down payment for a new home. These are some of the well-known but not easily-solved problems for the homebuilder and related stocks. Both ITB and XHB have no special allure on a valuation basis. They trade at high-teen’s P/E’s and above 1.5X book. Dividend yields are low, EPS trends are difficult for analysts to predict more than a year out, and most companies in each index have modest if any moats. So I’d like cheaper valuations before committing much money to the sector. Toll is a partial exception as it has a decent moat; Lowe’s (NYSE: LOW ), which is a member of XHB, is a category-killer. So is Home Depot (NYSE: HD ), which is too much of a mega-cap to be included in XHB. Again, aside from those giants, which I offer no opinion of in this article, the components of these ETFs should in my view trade at lower valuations before they become really attractive. Concluding thoughts – the importance of burst bubbles : There’s a lot to be said for industries that are important and glamorous enough to be the subject of bubbles. America itself was the subject of a bubble via stocks in 1929, and while the bubble broke very badly, the market had it right: the future was bright indeed for the United States. Certainly, investors had it right about home-based and laptop computing, plus mobile communications, in the 1990s, but of course they overpriced many stocks for a number of years. Then the Great Recession came, and lo and behold, tech did not suffer badly in the market; it then became the market leader since it bottomed before the overall market during the post-Lehman crash period. Assuming there will be another bear market in the next few years (not necessarily anything as severe as the 2008 period), homebuilders might act the way tech did then. There are good reasons to hypothesize this outcome. Interest rates have come down for reasons much of which have little to do with domestic issues and a lot to do with what might be a bursting bubble in China, plus what used to be called Eurosclerosis. Millenials have obvious unfilled demand for housing, and the housing stock in this country is getting a mite aged. So, while there may be a period of further indigestion ahead as the malinvestments of the housing bubble work themselves out, I’m optimistic that at some point, ITB and XHB will be market leaders in a future bull market just as tech has been in the current one. For now, focusing on the homebuilders, the only reasonably valued stock that is differentiated enough to keep as a long term hold in my view is TOL. Should it prove to be doing something really right based on Thursday’s upcoming earnings report, perhaps LEN could join it. Longer term, NVR has been a quite impressive outperformer, and thus might merit attention as an individual stock to own, especially on a general market or sector pullback. Looking at the XHB for non-homebuilder stocks, I do not see any special bargains. An old rule of thumb which was thrown away during the housing bubble was that homebuilders should in fact trade around 1.5X book value, because there was not much of a moat behind their business models. I think that as the bubble recedes into memory, this is a sensible approach to investing in the sector that helps to smooth out the often-violent earnings cycles. To answer the question in the title, my guess is that the housing stocks are, in the short run, more likely to roll over than rock on after a strong several years. That’s not a high conviction opinion, though. But I’m positive on a longer term basis, especially if Mr. Market allows a less expensive purchase price. Neither ITB nor XHB is a fund for the faint of heart. Neither is TOL, which has never paid a dividend and which typically sees substantial insider selling. As usual for non-blue chip companies, market, company and sector risks are non-trivial here. To summarize my views on the sector, there are several positives that combine to make for an attractive set-up even as the debris of the bubble makes the immediate future perhaps bumpy and dangerous for these stocks. These positives include demographic pressure, low interest rates and large areas of land suitable for development. It appears likely that this concatenation of favorable factors will allow ITB and XHB to shine again. Thus I think that investors should keep these funds and high-performing individual names in the sector in their sights, though I am not bullish on these stocks right now.