Tag Archives: management

TransCanada: What’s Next After The Looming Presidential Veto Of Keystone XL Pipeline?
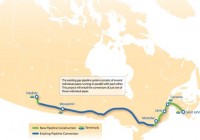
Summary TransCanada’s Keystone XL has received a majority “yes” vote from Senate, but it will likely get vetoed by President Obama. There are several things the company can do, including asking for remedies under the North American Free Trade Agreement. Further delays, however, will not jeopardize TransCanada’s future as the company has bigger and better projects in its capital program. Last week, the Democrats blocked the passage of TransCanada’s (NYSE: TRP ) Keystone XL pipeline bill in the U.S. Senate, lingering on the house’s discussion over the construction of the project. On Thursday, however, the Republicans — who have favored the pipeline — successfully passed a slightly amended version of the bill with 62 “yes” votes, thanks to the support from nine Democrats. But the bill is still five votes short of 67 required to bypass a presidential veto. The White House has already said that the President is going to use his authority to stop the bill from becoming a law on the pretext of the completion of the ongoing U.S. government review. The proposed 1,179-mile pipeline will carry 830,000 barrels of heavy oil a day from Canada’s tar sands to Nebraska’s Steele City, where it would connect with existing pipelines headed for refineries at the U.S. Gulf Coast. The pipeline will be built with a price tag of C$8 billion and could lift TransCanada’s annual EBITDA by US$1 billion when fully operational. The bill will likely get vetoed by President Obama, but that won’t be the end of Keystone XL. The fact that the project got the green light from the U.S. Senate for the first time since it was proposed in 2008, and a favorable ruling from Nebraska’s Supreme Court earlier this year, could be a harbinger of more positive things to come. It also helps that Keystone XL supporting Republicans now control both houses of Congress. Following the veto, the Republicans can modify the bill and resubmit for another round of debate. The legislative act with two-thirds majority will override the need for a presidential permit. Additionally, TransCanada could opt to seek remedies under the North American Free Trade Agreement (NAFTA), arguing that the rejection of the project is in violation of this historic agreement. The energy chapter of the free-trade agreement stipulates uninterrupted flow of oil, except under exceptional circumstances. Although it is debatable whether such an action would be a desirable for TransCanada, I believe it could certainly have an impact on the senators’ and President Obama’s decision. Alternatively, to avoid all the controversy surrounding the construction of a border-crossing pipeline and eliminate the requirement of a presidential permit — while also giving Canadian oil producers access to the U.S. Gulf Coast — TransCanada could construct a rail loop that would link up U.S. and Canadian crude pipelines. The company has already said that it is mulling the establishment of a rail terminal in Hardisty, Alberta — where the Keystone XL pipelines would have begun — and an import terminal in Cushing, Okla., which is the heart of the U.S. oil storage capacity with access to all the major markets. That said, TransCanada’s future prospects aren’t wrecked by the political wrangling over Keystone. That’s because over the years, Keystone has become less relevant to the company. In fact, Keystone XL is neither the largest nor the most profitable project in TransCanada’s C$46 billion backlog of capital programs. The C$12 billion Energy East pipeline is currently the biggest project in the company’s backlog. The Energy East pipeline would carry as much as 1.1 million barrels of crude oil a day from Alberta to shipping terminals located in eastern Canada, while lifting the company’s annual EBITDA by C$1.7 billion. Analysts believe Energy East could offer better margins than Keystone XL. (click to enlarge) Energy East Pipeline Map, Project Website . Besides the major pipelines, TransCanada also has C$13.2 billion of small- to medium-scale projects, which will gradually come online over the next three years. These projects, the company’s CEO Russ Girling said during the third-quarter conference call, will “provide visible benefits” to the company’s shareholders and will increase EBITDA. Furthermore, TransCanada has also diversified into power generation and gets around one-fifth of its earnings from this business. The company owns around 11,800MW of power generation capacity, serving customers in Alberta, Ontario, Quebec, and the northeastern United States. TransCanada’s 2,480MW Ravenswood Generating Station in Queens, N.Y., is its biggest plant and can handle around 21% of N.Y. City’s peak load. Meanwhile, due to the delays, the Canadian oil sands producers that would have been the biggest beneficiaries of the Keystone XL pipeline — such as Canadian Natural Resources (NYSE: CNQ ) , Suncor Energy (NYSE: SU ) and Cenovus Energy (NYSE: CVE ) — have been using other sources to ship their crude. Consequently, according to latest data from the National Energy Board of Canada, crude oil exports via rail have climbed 11.6% sequentially and 47.1% year over year to 182,059 barrels a day in the third quarter of 2014. Bottom Line The Nebraska Supreme Court ruling on Keystone XL removed a key hurdle in the construction of the project and the recent Senate approval is another step in the right direction. The bill will likely get vetoed by President Obama, but TransCanada will still have several options on the table. Ultimately, despite delays, I believe the pipeline will be built. That said, TransCanada has several other projects in its pipeline that are bigger, better, and less controversial than Keystone XL. TransCanada’s shares have fallen by 10% over the last six months, settling at $44.48 when the markets closed on Friday. The company’s shares are reasonably priced at 23.5 times its trailing 12 months earnings. The shares have been largely priced between 21 and 26 times over the last three years. Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) Business relationship disclosure: This article was written by Sarfaraz A. Khan, with valuable contributions from Adnan Mushtaq, research assistant at Half Bridge Business Review. Neither Sarfaraz A. Khan nor Adnan Mushtaq have any positions in the stock(s) mentioned in this article. The article expresses the author’s own opinions and does not constitute investment advice. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article.
Why I’m Buying Gilead And Selling Celgene

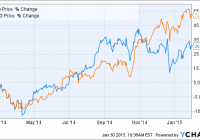
Summary Gilead appears very cheap compared to Celgene. In this article I compare growth expectations to valuation for the two companies. I think that a “pair trade” long Gilead and short Celgene makes sense at this time. Today I am starting a new mock portfolio on Seeking Alpha: the Pairs Trade Portfolio. Every transaction made in the portfolio will be a pair of trades of equal value (as close to $20,000 for each stock as can be), one long trade and one short trade. I plan on adding to this portfolio – and readjusting as necessary – over the next months and years and it will probably end up being a rather large study. The first trade is to go long Gilead (NASDAQ: GILD ) and short Celgene (NASDAQ: CELG ). My apologies for the length and description of this article. As it is the first in the series I will define and describe the strategy of pairs trading in detail here and refer to this page in future articles. Those readers familiar with the concept can skip over the next part and begin reading at the “Gilead vs. Celgene” section below. What is a “pair trade” and why would an investor want to do it? Pairs trading takes two highly correlated investment instruments and essentially pits them against each other. What stock will do better, Lowe’s or Home Depot? Pfizer or Merck? The investor goes long on the stock he/she thinks is undervalued relative to the overvalued one. The (relatively) overvalued one gets shorted. The investor is thus hedging bets and isolating a trade that only takes into account the relative value between two stocks. The strategy is often thought of as a very technical, statistics-driven exercise in which an outperforming stock is always shorted and the underperforming one is always the long. “Reversion to the mean” is counted on to make money in the pair trade. However, I feel that approach is short-sighted and I won’t be a slave to it. There are countless examples of stocks that outperform others consistently despite a high degree of correlation in the short term. Those are cases in which a pair trade with the underperforming stock as the long should be avoided. The motivation for making a pair trade is largely due to the fact that the strategy is a market-neutral hedge. It does not matter if the overall market crashes or zooms to new heights; the investor makes money if and only if the long stock pick outperforms the short stock pick. For example, let’s assume we set up a pair trade that is long Gilead at $100 per share and short Celgene at $120 per share and a market crash hits us in 2014. At the end of 2014, Gilead sits at $60 per share and Celgene goes to $60 as well. If the original position was $20,000 in each stock, then our pair trading investor has made $2,000 during 2014 (long GILD loses $8,000, short CELG gains $10,000) – a gain of 5% overall. Pairs trading is potentially a great defensive strategy. The market-neutral aspect of it makes it something to consider when it appears that stocks are overvalued in general. Pairs trading protects the investor from high valuations. Here’s a simplistic example: an investor believes that company A is a great company in a great industry. He/she really wants to invest in company A but the market is in the stratosphere and A sports a P/E of 70 – the risk seems to outweigh the reward. But he/she sees that company B, which has similar prospects to company A has a P/E of 110. The investor can go ahead and invest in company A as a pair trade with B and those P/E ratios might as well be 7 and 11, or 700 and 1100 for that matter. Recently I hear a lot of statements like “there’s nothing to buy”, “money has to be invested somewhere”, or “I’m afraid of valuations, but I don’t know what else to do but buy and hold.” At this point in time, I feel that every investor should consider any and every conservative strategy available. In my opinion, the US markets are in for a correction and I have written about the macro outlook a couple of times recently: One could think of a pairs trade strategy as another “what to do” when a bear market looks likely. Gilead vs. Celgene Both Gilead and Celgene are large biotech companies (market caps of about $157 billion and $96 billion respectively) and therefore it is not surprising that the correlation between the stock prices of the two companies was high during the past year: GILD data by YCharts A major divergence occurred recently – in early November – when Gilead started drifting lower/sideways while Celgene powered higher. On December 22, GILD took a fairly large plunge when Express Scripts (NASDAQ: ESRX ) announced that it would exclusively cover the AbbVie (NYSE: ABBV ) hep C drug. The question is, does that divergence mean that Gilead is undervalued compared to Celgene? The above chart suggests that might be the case and a further look is in order. I think that GILD is a better buy than CELG and the next sections will cover the growth prospects and valuation comparisons. Growth for Gilead The average analyst estimate for sales growth in 2015 is 17.8%. A quick look at where that growth will come from is in order to see if it makes sense. Estimates for worldwide growth in Sovaldi/Harvoni sales in 2015 are all over the map and while it is certainly difficult to guess where that will land, I’d say a conservative estimate is for 5% growth in sales. I’ve seen estimates from -5% to 30% growth. Sovaldi/Harvoni will likely account for more than half of Gilead’s total sales in 2015, but other drugs are growing fast and becoming more important for the company. In a previous article about Gilead, I noted that: According to Thomson Reuters, sales of idelalisib [Zydelig] are forecast to exceed $1 billion by 2017, with consensus sales forecasts of $1.218 billion that year. Zydelig began sales last quarter and it will be interesting to see how well it did in Q4 2014. It should add somewhere between $500 million to $700 million in 2015. In my article referenced above, I also singled out Stribild and noted that it was expected to see sales of over $2 billion in 2016. In 2014, it should easily clear the $1 billion mark. Like Zydelig, Stribild should also add a considerable amount to the top line. My estimate is an additional $700 to $900 million in 2015 sales. Complera/Eviplera is another in Gilead’s best-in-class HIV stable of drugs that is growing fast. In the first nine months of 2014, sales grew over 60% year to year and will eclipse the $1 billion mark for all of 2014. I expect it to add $500 to $600 million in sales to 2015 figures. A look at Gilead’s most recent 10-Q (see part 13. Segment Information) shows that the other drugs will likely be slightly up or slightly down. Add in any new approvals and there should be slight growth in the “other” category of those products that I did not mention above. Adding everything up (and making some assumptions for Q4 2014) puts my rather conservative 2015 revenue growth at about 12% – 14%. So by my back-of-the-envelope reckoning, the analyst expectations for 17.8% revenue growth look reasonable to me. Growth for Celgene Celgene’s growth is much easier to estimate as the company just gave guidance yesterday. Management expects 2015 revenue to grow 22.3% over 2014. Analyst estimates show a number of 21%, so it looks safe to assume something in the low 20s. Valuation I have recently written about Celgene’s GAAP and non-GAAP reporting in an article titled ” Celgene: Could You Be More Like Gilead, Please? ” and because I believe that the non-GAAP numbers inflate EPS, I will use GAAP figures for the P/E calculations below. Gilead should report EPS of about $7.25 for 2014. At a current stock price of $104.80, that equates to a P/E of 14.5. Celgene has reported EPS of $2.39 for 2014. At a current stock price of $119.16, that equates to a P/E of 49.9. Let’s take a look at cash generation: GILD Cash from Operations (TTM) data by YCharts Gilead’s market cap is about 60% higher than Celgene. However, it generates more than 300% cash than Celgene. The above chart shows the trailing 12 months, so once Gilead’s Q4 results are put into it, the figure will likely be something like 400% more cash from operations. Finally, a look at revenue: GILD Revenue (TTM) data by YCharts Again, Gilead’s soon-to-be-released Q4 results are not included. Once they are, the TTM sales number should be around $23 billion, or 200% higher than Celgene. Conclusion When we look at sales, earnings, and cash flow, we can see that Gilead is at a level anywhere from two to four times higher than Celgene. And yet the market cap of Gilead is only 60% higher than Celgene. 2015 growth estimates favor Celgene by 22.3% to 17.8%. Gilead’s incredible growth in 2014 will plateau and we will see good – but not exceptional – growth in 2015. For that reason, Celgene clearly does deserve a higher multiple, but not a multiple that is more than three times that of Gilead. I expect to see the difference in multiples between the two stocks narrow, thus favoring GILD in a pair trade. The Portfolio So here is what the mock portfolio looks like so far after executing the first pair trade: (click to enlarge) Not terribly exciting yet, but there will be more to come. Be sure to click “follow” if you would like to get real-time alerts on my future articles. Disclosure: The author is long GILD. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article.

Learning From The Past

I wish I could tell you that it was easy for me to stop making macroeconomic forecasts, once I set out to become a value investor. It’s difficult to get rid of convictions, especially if they are simple ones, such as which way will interest rates go? In the early-to-mid ’90s, many were convinced that interest rates had no way to go but up. A few mortgage REITs designed themselves around that idea. Fortunately, I arrived at the party late, after their investments that implicitly required interest rates to rise soon, fell dramatically in price. I bought a basket of them for less than book value, excluding the value of taxes that could be sheltered in a reverse merger. For some time, the stocks continued to fall, though not rapidly. I became familiar with what it was like to go through coercive rights offerings from cash-hungry companies in trouble. Bankruptcy was not impossible… and I burned a lot of mental bandwidth on these. The rights offerings weren’t really good things in themselves, but they led me to buy in at a good time. Fortunately I had slack capital to deploy. That may have taught me the wrong lesson on averaging down, as we will see later. As it was, I ended up making money on these, though less than the market, and with a lot of Sturm und Drang. That leads me to my main topic of the era: Caldor. Caldor was a discount retailer that was active in the Northeast, but nationally was a poor third to Wal-Mart (NYSE: WMT ) and KMart. It came up with the bright idea of expanding the number of stores it had in the mid-90s without raising capital. It even turned down an opportunity to float junk bonds. I remember noting that the leverage seemed high. What I didn’t recognize that the cost of avoiding issuing equity or longer-term debt was greater reliance on short-term debt from factors – short-term lenders that had a priority claim on inventory. It would eventually prove to be a fatal error, and one that an asset-liability manager should have known well – never finance a long-term asset with short-term debt. It seems like a cost savings, but it raises the likelihood of insolvency significantly. Still, it seemed very cheap, and one of my favorite value investors, Michael Price, owned a little less than 10% of the common stock. So I bought some, and averaged down three times before the bankruptcy, and one time afterwards, until I learned Michael Price was selling his stake, and when he did so, he did it without any thought of what it would do to the stock price. Now for two counterfactuals: Caldor could have perhaps merged with Bradlee’s, closed their worst stores, refinanced their debt, issued equity, and tried to be a northeast regional retail player. It didn’t do that. The investor relations guy could have given a more understanding answer when he was asked whether Caldor was having any difficulties with credit lines from their factors. Instead, he was rude and dismissive to the questioning analyst. What was the result? The factors blinked and pulled their lines, and Caldor went into bankruptcy. What were my lessons from this episode? Don’t average down more than once, and only do so limitedly, without a significant analysis. This is where my portfolio rule seven came from. Don’t engage in hero worship, and have initial distrust for single large investors until they prove to be fair to all outside passive minority investors. Avoid overly indebted companies. Avoid asset liability mismatches. Portfolio rule three would have helped me here. Analyze whether management has a decent strategy, particularly when they are up against stronger competition. The broader understanding of portfolio rule six would have steered me clear. Impose a diversification limit. Even though I concentrate positions and industries in my investing, I still have limits. That’s another part of rule seven, which limits me from getting too certain. The result was my largest loss, and I would not lose more on any single investment again until 2008 – I’ll get to that one later. It was my largest loss as a fraction of my net worth ever – after taxes, it was about 4%. As a fraction of my liquid net worth at the time, more like 10%. Ouch. So, what did I do to memorialize this? Big losses should always be memorialized. I taught my (then small) kids to say “Caldor” to me when I talked too much about investing. They thought it was kind of fun, and I would thank them for it, while grimacing. But that helped. Remember, value investing is first about safety, and second about cheapness. Cheapness rarely makes something safe enough on its own, so analyze balance sheets, strategy, use of cash flow, etc. This is not to say that I did not make any more errors, but this one reduced the size and frequency. That said, there will be more “fun” chapters to share in this series, because we always learn more from errors than successes. Disclosure: None.