Tag Archives: management

ETB Vs. ETV: What’s The Difference?
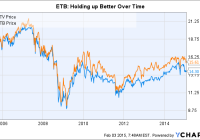
Summary At a quick glance, ETV and ETB look like almost mirror images of one another. ETV’s longer-term performance hasn’t been as good as ETB’s, based on market price. But based on total return, ETV has done a little better over time. If I had to choose, ETB would be my call. A pet peeve of mine is when a fund sponsor has two similar funds available that, on the surface, appear to be clones of one another. That’s exactly the case with the Eaton Vance Tax-Managed Buy-Write Opportunities Fund (NYSE: ETV ) and Eaton Vance Tax-Managed Buy-Write Income Fund (NYSE: ETB ). But when you look just a little closer, the differences are there – they’re just subtle. The same… One of the first things I look at when examining a fund is its objective. In the case of ETV : “The Fund’s primary investment objective is to provide current income and gains, with a secondary objective of capital appreciation.” ETB’s objective is, word for word, the same. And the managers are the same, too. With Walter A. Row and Thomas Seto heading things up since each of the funds’ initial public offerings. Which brings us to one relatively minor distinction between the two funds. ETV IPO-ed on June 30, 2005. ETB IPO-ed on April 29, 2005. This is a virtually irrelevant fact at this point, but it is a difference. Even the standard deviation, a measure of share price volatility, of the two funds is roughly the same. According to Morningstar, both funds have five-year standard deviations of about 9.5 versus a standard deviation for the S&P 500 of around 13. So they aren’t as volatile as the overall market, which can be good and bad. For example, over the trailing five-year period, they each captured around 60% of the market’s advance and 60% of the market’s decline. ETV is a touch better on both sides, gaining a little more and losing a little less. But the variance is tiny. … But different So, in a number of ways, ETV and ETB are virtual clones of each other. For example, over the trailing five-year period through the end of January (neither has 10-year numbers just yet), ETV’s annualized return is 11.4% based on its net asset value, or NAV, and 12.7% based on its share price. ETB’s annualized returns are 11% and 11.2%, respectively, over the same time span. Morningstar’s numbers are total return, which includes distributions, but it’s worth noting that the returns are fairly similar based on NAV. Furthermore, total return since the inception of each fund is only nine basis (0.09) points different based on NAV, according to Eaton Vance, bringing the pair’s performance even closer together. Yield, however, is a noteworthy differences. ETV’s yield is around 9.5%, according to the Closed-End Fund Association, and ETB’s yield is about 8.2%. Right now, ETV’s monthly distribution is $0.1108 and ETB’s distribution is $0.108. ETB’s NAV is a little over a dollar higher than that of its sibling. The biggest difference, however, is probably in the portfolios. At the end of last year, ETV’s largest sector weighting was in technology, at nearly 36% of the portfolio. That was more than double the second- and third-largest sectors combined (consumer discretionary at 14.6% and healthcare at 14%). Technology was materially overweighted relative to the S&P 500, where tech stood at roughly 20% of the index. Technology was ETB’s largest sector weighting, too. But it came in at roughly 18%, a couple of percentage points lower than the index. The financial sector, meanwhile, was the fund’s number two sector, at just a touch under 18%. The consumer discretionary sector came in third, with a weighting of about 14%. The weighting of both the consumer discretionary and financial segments were just slightly above the index. In fact, when looking at the broader portfolios based on sectors, ETB looks far more like the index than its sibling. It isn’t an index clone, but the differences are at the margins. ETV, on the other hand, is clearly making a big bet on technology – that must be where the managers see “opportunity.” The weighting given to each fund’s largest holdings is also worth a comment. ETV, for example, had over 20% of its assets in its top four holdings – all of which were tech names. And eight of the top 10 holdings were tech, with a ninth that could arguably be technology, too. ETB’s top four holdings were closer to 10% of its portfolio. In fact, you’d have to reach out to the top 10 holdings at ETB to get to 20% or so of assets. And the mix in that top 10 was comparatively diverse. “Opportunity” is the key Clearly, the use of the word “opportunity” in the name of ETV is about the fund’s ability to stray quite far from its benchmark. That’s neither good nor bad, but is something investors should keep in mind. Over the longer term (since inception) it doesn’t appear to have done too much to help performance, though over the past five years it looks like it has been a slight benefit. That said, looking at each fund’s distributions, return of capital has been a big component. The use of options strategies virtually guarantees this. However, between 2010 and year-end 2013, ETV’s NAV went from roughly $14.50 to $14.80. The NAV is currently around $14.50 again. So, over last four years, the NAV has gone virtually nowhere. ETV data by YCharts ETB, meanwhile, watched its NAV go from $15.60 at the start of 2010 to $16.25 at the end of 2013. Its current NAV is about $15.85. ETB has been better able to build value for its shareholders than ETV, if only by a little bit. That is likely attributable to the lower distribution and yield – even though ETB’s name includes the word “income.” For my money, I’d recommend ETB over ETV, leaving the upside potential of seeking out “opportunities” to someone else. Slow and steady is more my speed, because the relatively large bets that ETV is taking may pan out, but there’s the chance that they don’t. For example, if you look at NAV back to the start of 2009, ETV actually looks like a better option because of a 39% NAV advance that year, compared to ETB’s 30% increase. That said, go back one more year to 2008, and you see that ETV fell 25% more than ETB in what was a brutal year for the stock markets (ETV fell 28.5%, compared to ETB’s more modest decline of 22.8%). There are always trade-offs in investing and ETV and ETB are no exception. The differences are somewhat minor, and even where they do show up, performance hasn’t been disproportionately impacted over the long term. That leads me to err on the side of caution – the more diversified portfolio and lower distribution of ETB. Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article.
Traditional Equal Weighting May Not Be As Diversified As You Think

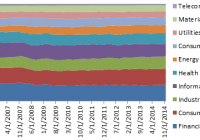
Summary The simplest of smart beta methodologies is widely accepted to be equal weighting. But traditional equal weighting also introduces static sector biases since the weight allocated to each sector is determined solely by the number of companies in the sector. We believe employing sector equal weighting followed by constituent equal weighting in the rebalancing process may ultimately be a better way to distribute risk across the portfolio. By John Feyerer The core belief that we have held at PowerShares since we were founded back in 2002, and continue to hold today, is that funds tracking market-capitalization-weighted indexes may not represent the optimal investment strategy. Why? If one believes (as we do) that markets aren’t perfectly efficient and security mispricing can and does exist, market-capitalization-weighted indices will, by definition, have overweighted those securities that through time proved to be overvalued and similarly will have underweighted those securities that proved to be undervalued – thus creating a relative drag on investment performance. Of course the quest for active managers is to accurately identify which camp each security falls into at a given point in time (overvalued versus undervalued) and position portfolios to capitalize on the reversion to the mean. In contrast, smart beta strategies are objective, rules-based, index methodologies that sever the link between price and portfolio weight and employ a disciplined rebalancing mechanism. From there a lot of fun can be had talking about the different risk factors that can serve as the basis for these methodologies, but it is important to remember the two basic ingredients that lie at the core of all smart beta strategies: weighting by non-price-related measures and systematic rebalancing. ‘Naïve’ doesn’t necessarily mean balanced The simplest of smart beta methodologies is widely accepted to be equal weighting. This technique is commonly referred to as ‘naïve’ as it entails allocating the same weight to each constituent in the index and regularly rebalancing back to base weights. Why is this approach described as ‘naïve’? Because it does not make any assumptions about the index constituents (their size, prospects for future return, etc.) but instead simply weights them all equally. While traditional equal weighting certainly contains the basic ingredients of smart beta -non-price-weighted and systematically rebalanced – it also introduces static sector biases since the weight allocated to each sector is determined solely by the number of companies in the sector. For example, if an index contains 100 financial stocks and 50 technology stocks, the portfolio weight in financials would be double that of technology, regardless of the relative size between the two sectors. The number of companies in a given sector alone is unlikely to be related to the relative prospects of that sector versus others, yet a simple constituent equal-weight strategy will statically allocate more (in some cases substantially!) weight to some sectors than others for the arbitrary reason of the difference in the number of constituents. For example, as seen in Figure 1, the constituent equal-weight approach employed in the S&P 500 Equal Weight Index results in significant sector concentration, with three of the 10 sectors (financials, consumer discretionary and industrials) consistently comprising between 44% and 47% of the weight of the portfolio during the last 10 years. In fact, in some cases constituent equal weighting can introduce greater sector-specific risk than capitalization weighting, as demonstrated by Figure 2. If one were to take a constituent equal-weight approach to the Russell 1000 Index, that would result in an allocation of 22.2% of the portfolio to the financial services sector versus just 4.8% to consumer staples – a spread of over 17%. An alternative to constituent equal weighting is the approach that Russell Indexes takes with its Russell 1000 Equal Weight Index. The firm initially equally weights the sectors (at each quarterly rebalance 11.1% is allocated to each of the nine sectors within the Russell Global Sector classification system) and then follows that by equally weighting the constituents within each sector. This results in a portfolio that we believe is both “naïve” from a sector and constituent level and helps mitigate the sector biases inherent in a constituent equal-weight approach. This methodology also enables the index to contra-trade against the most recent price movements at the sector level as well as at the constituent level as the index rebalances. While clearly aligning with the basic elements of smart beta – the traditional equal-weight approach may not be as diversified as many investors think, and it may, in fact, be introducing unintended sector-specific risk to an investment portfolio. Employing sector equal weighting followed by constituent equal weighting in the rebalancing process is an approach that we believe ultimately results in a better way to distribute risk across the portfolio. EXHIBITS: Figure 1: S&P 500 Equal Weight Index – Sector Composition through time Source: Global ETF Products & Research with underlying data from FactSet; Data as of Dec. 31, 2014 Figure 2: Russell 1000 Sector Allocation Comparison Source: Russell Investments as of Dec. 22, 2014. The Russell 1000® Index is an unmanaged index considered representative of large-cap stocks. The Russell 1000® Index is a trademark/ service mark of the Frank Russell Co. Russell® is a trademark of the Frank Russell Co. The Russell 1000® Equal Weight Index is a trademark of Frank Russell Company and has been licensed for use by Invesco PowerShares. The Product is not sponsored, endorsed, sold or promoted by Frank Russell Company and Frank Russell Company makes no representation regarding the advisability of investing in the Product. An investment cannot be made directly into an index. *Russell 1000 CEW is not an actual index, but illustrates how the Russell 1000 Index could look under a constituent equal-weighting approach. To create this hypothetical index, equal weight was given to each constituent of the Russell 1000 Index, using the index’s holdings as of Dec. 22, 2014. Important Information The Russell Global Sector classification system categorizes stocks into nine sectors: technology, health care, consumer discretionary, consumer staples, energy, materials and processing, producer durables, financial services and utilities. As the index rebalances back to base weights, it increases weight in those sectors/stocks that have decreased in price while decreasing weight in those sectors/stocks that have increased in price – thus contra-trading against recent market movements. The S&P 500 Equal Weight Index is the equally weighted version of the S&P 500 Index. The S&P 500 Index is an unmanaged index considered representative of the U.S. stock market. Before investing, investors should carefully read the prospectus/ summary prospectus and carefully consider the investment objectives, risks, charges and expenses. For this and more complete information about the Funds call 800 983 0903 or visit invescopowershares.com for prospectus/summary prospectus. Diversification does not guarantee a profit or eliminate the risk of loss. Beta is a measure of risk representing how a security is expected to respond to general market movements. Smart Beta represents an alternative and selection index based methodology that seeks to outperform a benchmark or reduce portfolio risk, or both. Smart beta funds may underperform cap-weighted benchmarks and increase portfolio risk. There are risks involved with investing in ETFs, including possible loss of money. Index-based ETFs are not actively managed. Actively managed ETFs do not necessarily seek to replicate the performance of a specified index. Both index-based and actively managed ETFs are subject to risks similar to stocks, including those related to short selling and margin maintenance. Ordinary brokerage commissions apply. The Fund’s return may not match the return of the underlying index. Investments focused in a particular industry are subject to greater risk, and are more greatly impacted by market volatility than more diversified investments. The Global Industry Classification Standard was developed by and is the exclusive property and a service mark of MSCI, Inc. and Standard & Poor’s. The information provided is for educational purposes only and does not constitute a recommendation of the suitability of any investment strategy for a particular investor. Invesco does not provide tax advice. The tax information contained herein is general and is not exhaustive by nature. Federal and state tax laws are complex and constantly changing. Investors should always consult their own legal or tax professional for information concerning their individual situation. The opinions expressed are those of the authors, are based on current market conditions and are subject to change without notice. These opinions may differ from those of other Invesco investment professionals. NOT FDIC INSURED MAY LOSE VALUE NO BANK GUARANTEE All data provided by Invesco unless otherwise noted. Invesco Distributors, Inc. is the U.S. distributor for Invesco Ltd.’s retail products and collective trust funds. Invesco Advisers, Inc. and other affiliated investment advisers mentioned provide investment advisory services and do not sell securities. Invesco Unit Investment Trusts are distributed by the sponsor, Invesco Capital Markets, Inc., and broker-dealers including Invesco Distributors, Inc. PowerShares® is a registered trademark of Invesco PowerShares Capital Management LLC (Invesco PowerShares). Each entity is an indirect, wholly owned subsidiary of Invesco Ltd. ©2014 Invesco Ltd. All rights reserved. blog.invesco.us.com

‘The Turn’ Is Near For Natural Gas Pricing, Buy UGAZ

Summary UGAZ is about to bottom on Thursday despite a few poor inventories to follow. I lay the factors that will help lead natural gas pricing higher. Although plenty of volatility will follow, get long UGAZ and ride the longer term trend higher. “The Turn” for natural gas pricing, as I like to call it, should be taking place beginning with capitulation trading on next Thursday’s natural gas inventory report which should be a bloodbath for natural gas longs, of which I am as of a few days ago. 2014 was murderer’s row for natural gas bulls as natural gas couldn’t find a cold winter or anything resembling a winter outside of the occasional cold snap. Hilariously, for those like myself short the entire way down, that would cause an unwarranted and ill-advised #NotablePop (twitter hashtag searchable) buying of natural gas trading vehicles like The United States Natural Gas ETF, LP (NYSEARCA: UNG ) and even more hilariously the VelocityShares 3x Long Natural Gas ETN (NYSEARCA: UGAZ ). Take a look at these execution charts: (click to enlarge) (click to enlarge) (click to enlarge) Keep in mind that during the winter of 2013 UGAZ reached the high $40s. The ETN now trades in the $2s. I sold it to somebody at $45 (highlighted in the white box above), which frankly I still feel bad for the buyer. The good news is, I’ve switched hats from black to white and I’m now long a starter position of UGAZ at $2.90 with plenty of beaten and bloodied 2014 natural gas bull money to spend on lower buys. That can mean only one thing, natural gas pricing has bottomed and is about to go much higher. What’s my natural gas pricing increase thesis based around?: Falling rig counts hurt overall production – that’s good for the supply side of the equation as production is slowed overall. Less oil E&P to come on lower CAPEX across the board for oil and natural gas E&Ps – that’s also good for the supply side of the equation (Source: Bloomberg.com). I’m betting on the fact that spring will start early and Summer will be, well, it’ll be hot – that’s good for the demand side of the equation – for clarity these projections are based on longer term weather models from Weather.com which may be unreliable. I believe at poor hedging or at lower than ideal aggregate hedging that natural gas E&P names won’t “pump baby pump” as hard into what has been excellent hedging in size the last few years – that’s also good for the supply side. Examples of companies I’ve reviewed that have 1) less than ideal pricing hedging or 2) less than ideal aggregate hedging coverage are Chesapeake Energy Corporation (NYSE: CHK ) , Antero Resources Corporation (NYSE: AR ) , Ultra Petroleum Corp. (NYSE: UPL ) , H alcon Resources Corporation (NYSE: HK ) , SandRidge Energy, Inc. (NYSE: SD ), Quicksilver Resources Inc. (NYSE: KWK ), etc. This list could have been 50 names deep. Obviously the big variable portion of the equation above is weather. Let me do you guys a favor and make this real easy. Go ahead and pull up the city of Austin, TX into your weather app in your smart phone. Only view that city’s weather. Don’t EVER look at another city’s weather or another part of the country’s weather. Austin is the bell weather for natural gas demand. Why is that? I have no idea. Actually I think it has something to do with the fact that Austin is centrally-located, located near a major creator of weather systems – the equator, and that Texas in general is a huge user of natural gas. The fact that Austin sees the fewest of the far end of the spectrum weather developments when it comes to Texas cities makes it a great middle-spectrum city to judge Texas weather. Take a look at the following charts and consider the following: (click to enlarge) My models use a ground level temperature of 50 degrees as the demand generator for heating demand in the heating seasons and 75 degrees for cooling demand in cooling seasons. The redline in the graph on the left, which lists Austin temps the last twelve months, is indicative of this 50 degree temperature. Notice that when temps fall below the line (indicated by the blue streaking bars), UNG pricing moves higher. When it does not, UNG pricing moves lower. The correlations have been boxed in red . You can see a very high level of correlation between the two. Now, also notice that during the summer of 2014 there was in fact cooling demand (red lines on the chart to the left spiking above 80 degrees) but that demand was offset by greater than expected injections from natural gas producers (Source: U.S. Energy Information Administration) which held pricing flat through the summer and allowed for a further lack of cooling demand during the “winter” of 2014 (boxed in red toward the right hand side of each graph) to destroy natural gas pricing (also listed as a factor that will now contribute to the bull thesis as I believe from analysis of E&P sector names that hedging is not as comprehensive as it has been nor will production be as great because of the other factors bulleted). Notice that while the temperature curve remains the same from a slope line perspective the correlation falls apart in other regions – this is Chicago which stays in a much tighter temperature range: (click to enlarge) I’ve boxed Chicago temps in red below 50 degrees simply as a comparable temperature range but notice that Chicago temps stay in a 30 degree range basically year round with heating demand necessary just about 9 months out of the year. The correlation falls apart on this graph. How about New York City?: (click to enlarge) Again, we see the correlation fall apart. I have modeled in the correlation between UNG and every major city in the U.S. where demand is meaningful (based on population and the cities’ usage of natural gas) and Austin’s is the most reliable I could find. Again, with such tight temperature ranges it makes using other cities hard when trying to isolate a specific temperature at which demand is created and at which other weather systems will be effected. So, as I bid my short weapon of choice goodbye I’ll leave readers with a quick look at the chart that developed since I got long the VelocityShares 3x Inverse Natural Gas ETN (NYSEARCA: DGAZ ) at ~$2.75: (click to enlarge) If you haven’t already, I would begin accumulating a position in UGAZ on dips as I think the lowest it goes is ~$2.00 on Thursday’s smoke show. Even though several inventory reports in a row after that will be terrible, I think the big energy desks that trade this commodity will begin building positions that will start to support pricing. When you’re moving real weight, not the 100 share lots of retail, you have to do it over the course of a month or so and I think that starts in 6 days. For the record, I plan to run this column weekly or as often as I have a meaningful update to provide on inventory reports. That means you can tune in for tasty treats every Thursday. I have bought UGAZ but make no particular recommendation to any other person or entity to do so. Buying a 3X leveraged commodity trading vehicle should be done after one’s own analysis and at one’s risk. Disclosure The risks of investing in a 3X leveraged commodity trading vehicle like UGAZ/DGAZ are much greater than those of other vehicles. These risks include (Source: Velocitysharesetns.com/ugaz): ETNs are only suitable for knowledgeable investors seeking daily exposure (including inverse or leveraged exposure) to the underlying index. ETNs are intended for short-term trading, therefore investors with a horizon longer than one day trading should carefully consider whether the ETNs are appropriate for their investment portfolio. Because the inverse leveraged ETNs and leveraged long ETNs are linked to the daily performance of the applicable underlying Index and include either inverse and/or leveraged exposure, changes in the market price of the underlying futures will have a greater likelihood of causing such ETNs to be worth zero than if such ETNs were not linked to the inverse or leveraged return of the applicable underlying Index. The ETNs do not guarantee any return of principal at maturity and do not pay any interest during their term. At higher levels of volatility, and since the ETNs are not principal protected, there is a significant chance of a complete loss of ETN value even if the performance of the index is flat. The closing indicative value on each valuation date is determined in part by reference to the daily percentage change in the level of the underlying index. As a result, to the extent the closing indicative value of the ETNs is greater than or less than the initial indicative value, subsequent changes in the level of the index may have a bigger or smaller impact on the closing indicative value of the ETNs than if the closing indicative value remained constant at the initial indicative value. For example, assuming an initial indicative value of $100, if the closing indicative value of the ETNs increases above $100, a subsequent 1% daily change in the level of the index will result in more than a $1 decrease in the closing indicative value of the ETNs. Likewise, if the closing indicative value of the ETNs is less than $100, a 1% increase in the level of the index will result in less than a $1 increase in the closing indicative value of the ETNs. If the level of the underlying index decreases or does not increase sufficiently (or if it increases or does not decrease sufficiently in the case of the inverse ETNs), to offset the effect of the Daily Investor Fee over the term of the ETNs, the investor will receive less than the principal amount of his investment upon early redemption, acceleration or maturity of the Notes. This particular ETN also runs the risk of being decayed by contango which is defined by Investopedia as: A situation where the future price of a commodity is above the expected future spot price. Contango refers to a situation where the future spot price is below the current price, and people are willing to pay more for a commodity at some point in the future than the actual expected price of the commodity. This may be due to people’s desire to pay a premium to have the commodity in the future rather than paying the costs of storage and carry costs of buying the commodity today. Finally, there are general risks that should also be considered such as liquidity risk (Source: Investopedia.com): The risk stemming from the lack of marketability of an investment that cannot be bought or sold quickly enough to prevent or minimize a loss. Liquidity risk is typically reflected in unusually wide bid-ask spreads or large price movements (especially to the downside – which are magnified in leveraged ETNs) . The rule of thumb is that the smaller the size of the security or its issuer, the larger the liquidity risk. Disclosure: The author is long UGAZ. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article.