Tag Archives: management

Best And Worst Q3’15: All Cap Value ETFs, Mutual Funds And Key Holdings
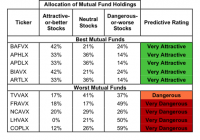
Summary All Cap Value style ranks fifth in Q3’15. Based on an aggregation of ratings of 0 ETFs and 257 mutual funds. BAFVX is our top-rated All Cap Value mutual fund and COPLX is our worst-rated All Cap Value mutual fund. The All Cap Value style ranks fifth out of the twelve fund styles as detailed in our Q3’15 Style Ratings for ETFs and Mutual Funds report. It gets our Neutral rating, which is based on aggregation of ratings of 0 ETFs (no All Cap Value ETFs are currently under coverage) and 257 mutual funds in the All Cap Value style. See a recap of our Q2’15 Style Ratings here. Figure 1 shows the five best and worst rated All Cap Value mutual funds. Not all All Cap Value style mutual funds are created the same. The number of holdings varies widely (from 21 to 521). This variation creates drastically different investment implications and, therefore, ratings. Investors seeking exposure to the All Cap Value style should buy one of the Attractive-or-better rated ETFs or mutual funds from Figure 1. Figure 1: Mutual Funds with the Best & Worst Ratings – Top 5 (click to enlarge) * Best mutual funds exclude funds with TNAs less than $100 million for inadequate liquidity. Sources: New Constructs, LLC and company filings LSV U.S. Managed Volatility Fund (MUTF: LSVMX ) (MUTF: LVAMX ) is excluded from Figure 2 because its total net assets are below $100 million and do not meet our liquidity minimums. The Brown Advisory Value Equity Fund (MUTF: BAFVX ) is the top-rated All Cap Value mutual fund and earns a Very Attractive rating. The Copley Fund (MUTF: COPLX ) is the worst-rated All Cap Value mutual fund and earns a Very Dangerous rating. Oracle Corporation (NYSE: ORCL ) is one of our favorite stocks held by All Cap Value funds and earns our Attractive rating. Over the past decade, the company has grown after-tax profit ( NOPAT ) by 15% compounded annually. Oracle currently earns a top quintile return on invested capital ( ROIC ) of 25%. Despite one of the highest ROIC’s in the business and consistent profit growth, ORCL remains undervalued. At its current price of ~$39/share, Oracle has a price to economic book value ( PEBV ) ratio of 1.1. This ratio implies that the market expects Oracle’s profits to grow by no more than 10% over current levels for the remainder of its corporate life. If Oracle can grow NOPAT by just 5% compounded annually for the next ten years , the stock is worth $53/share – a 36% upside. Intersil (NASDAQ: ISIL ), a previous Danger Zone pick , is one of our least favorite stocks held by All Cap Value funds and earns our Very Dangerous rating. Since 2009, Intersil’s NOPAT has fallen by 31% compounded annually. The company currently earns a bottom quintile ROIC of 1% and has a NOPAT margin of only 2%. Such a low margin leaves little room for error in the highly competitive semiconductor industry. With such poor fundamentals, Intersil’s stock, despite being down 18% year to date, remains overvalued. To justify the current price of $11/share, Intersil must grow NOPAT by 30% compounded annually for the next 19 years. Betting on double digit NOPAT growth for such an extended period of time is overly risky given the past profits profile of this company. Investors should, instead, invest in quality stocks like Oracle. Figure 2 shows the rating landscape of all All Cap Value mutual funds. Figure 2: Separating the Best Mutual Funds From the Worst Funds (click to enlarge) Sources: New Constructs, LLC and company filings D isclosure: David Trainer and Max Lee receive no compensation to write about any specific stock, style, style or theme. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article.
Active Power: At An Inflection Point?

ACPW is a name that has long been a disappointment. But it appears that new management is showing to have an effect on shaping operations at the company – ACPW just reported its sixth quarter of greater than 1:1 book/bill. ACPW is also growing sales while managing higher gross margins – this had the effect of reducing overall cash burn, always a concern for microcaps. If ACPW can sustain its operating momentum it should scale up market cap with each quarter reported as the niche has a well-established EV/revenue multiple. Active Power (NASDAQ: ACPW ) is an interesting name that I came across recently. The company’s headquarters is coincidentally located just a few blocks away from my home. After passing by its offices time and time again, and this is a name that I’ve seen trend in the social arenas a few times over the last year, I decided to take a look into the filings. What I found looks like a company that might be at an inflection point that has long been in the making. First, ACPW is “engaged in designing, manufacturing and selling of flywheel-based uninterruptible power supply (“UPS”) products and modular infrastructure solutions (SOURCE: ACPW 10-K)”. Put simply, the company helps regulate power to facilities and entities that can ill afford to not have a steady power flow; and provides essential infrastructure to facilities and entities that want greater control over microgrids. The latter functionality taps into the burgeoning market for off-grid power production from a single or multiple sources of alternative energy production (e.g. solar power installations, wind power farms, etc.). Both UPS power regulation and microgrid applications are growing more evident value-props in 1) an increasingly stressed electrical infrastructure (international electrical infrastructures are already stressed) and 2) an infrastructure in which microgrids (read: hospitals, university campuses, massive server host facilities, etc.) are becoming more valuable. While these are long term, secular trends to be sure – there is no denying that the visibility of the necessity for equipment and services provided by ACPW is increasing. In that the value prop and visibility of value prop are set up in this instance to be longer term, I’m viewing ACPW as strictly a long-term buy and hold opportunity. Shares of ACPW likely will not trade sharply higher overnight, but I believe they will trade higher steadily over extended durations. (click to enlarge) In saying that, through 1H/15 reporting ACPW is showing to have steadily improving operations and a more consistently stable overall model. Trading at less than one times EV/revenue (TTM) and trading 30 bps below a peer group EV/revenue multiple average of 1X (consisting of Capstone Turbine (NASDAQ: CPST ), FuelCell Energy (NASDAQ: FCEL ), Maxwell Technologies (NASDAQ: MXWL ) and PowerSecure International (NYSE: POWR )), now might be a good time to consider initiating a position in ACPW. ACPW has generated ~$58 million in TTM revenues, showing a healthy revenue base for a microcap – certainly having such revenues allows the company certain flexibilities not inherent in pre/low revenue microcap models, and is on pace to achieve approximately the same figure in full year 2015 (annualizing 1H/15 performance – it should be noted that ACPW does report lumpy revenues from time to time). The company also recently posted its first quarter of positive Adjusted EBITDA in quite some time and greatly closed its long-standing net loss and negative EPS: (click to enlarge) When coupling this income statement performance with the fact that the company has ~$10.6 million in C&CE on its balance sheet, $37.4 million in assets, $19.8 million in liabilities, and $5.5 million in debt, I consider the company to not be at any near-term structural risk. ACPW’s cash, which is always important to monitor in this market cap space, should last at least the next 12 months. I anticipate the cash balance will likely last much longer, basing this assumption on ACPW’s 10-K filing and cash burn generally associated with total net loss. I could realistically see full year 2015, which through 1H/15 ACPW has shown roughly half the total cash burn as 1H/14, being the lowest cash burn print in 4 years . If ACPW can prove out 2015 to be at or near cash flow breakeven, management has not given guidance to this, this would materially move forward the bull case. Typically with microcaps, dilution and/or a reliance on debt as a result of high rates of cash burn is at or near the top of the risk list. ACPW, depending on sales ramp, might be close to negating this risk. In regards to sales at ACPW, upon reviewing the company’s 10-K filing for the year ended 12/31/14 this was a red flag to me in considering ACPW for a bullish recommendation. I noticed that the company had, as of its now 6-month-old 10-K filing, a history of falling sales on flat operating expenses – which was particularly concerning. I also knew that ACPW had changed management teams less than two years ago and the lack of progress visible on the topline was adding to my initial concerns. However, when viewing the current year’s Q1 and Q2 10-Q filings, of course, I saw the data illustrated in the image above which speaks quite to the contrary of the performance in the 10-K. ACPW appears to have turned a corner in selling as of the first two quarters of 2015. Still, even knowing this, it was encouraging to see that ACPW broke out its sales in its August Investor Deck into book to bill ratios. ACPW, as of Q2/15, reported its sixth consecutive quarter of a greater than 1.0 book to bill ratio – this has led to a much healthier trend line: (click to enlarge) Again, this increased consistency and overall scale has led to a return to positive Adjusted EBITDA for ACPW as well as increasing gross margins – another sign of increasing operating health: (click to enlarge) Finally, it should be noted that ACPW has fragmented and diversified both its geographical revenue dependence as well as its dependence on any singular revenue channel – yet more reasons to believe that the increased book to bill ratio is sustainable under the new regime: (click to enlarge) All told I believe ACPW is deserving of a hard look at this point in its development by those interested in securing an ownership in electrical grid and microgrid management. I don’t believe there is any denying that there are secular growth trends supporting both a need and desire for these types of services. ACPW, while being largely a disappointment since its IPO many years ago, appears to be changing course under new management. The story at ACPW has been slowly progressing – to management’s credit this does have quite a bit to do with the fact that ACPW is a capital equipment company – but it is now having a positive effect on the company’s health. If ACPW is at an inflection point, which I’m leaning heavily into the fact that it is, it should be able to grow its market cap. Despite improved financial performance in the first half of the year, the stock has not moved. The realization of a continuation of greater than 1:1 book to bill ratios bodes well for the company and its shares. Good luck everybody. Editor’s Note: This article covers one or more stocks trading at less than $1 per share and/or with less than a $100 million market cap. Please be aware of the risks associated with these stocks. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.

Is The USDA Right About Cotton?

Summary The most recent report shows a 20% decline in production. Crude oil remains near 6 year lows. Global stocks are shrinking, but not by much. October is peak harvesting season for cotton. This article will center around the recent United States Department of Agriculture (USDA) projections on cotton and the subsequent affect that could have on the iPath Dow Jones-UBS Cotton Total Return Sub-Index ETN (NYSEARCA: BAL ). During our last article on BAL, which you can read here , we discussed how oil and cotton shared a correlation. We will revisit that discussion and end with an analysis of current conditions. USDA For the full context of what we are going to discuss in this article, here are the links to the USDA’s August crop production and world markets and trade circulars for cotton. I highly recommend viewing the links as we will not cover the global supply and demand factors in this article (except for a summary in the conclusion). (click to enlarge) Chart obtained from the USDA. The above chart explains the recent increase in cotton prices. United States production is projected to be down almost 20% over last year. The keyword I want to highlight here is projected. See below for a more detailed view of the projections: (click to enlarge) Chart obtained from the USDA. The reason I was highlighting the word “projected” is because some Texas farmers were on record saying that they believe the numbers for abandonment are way off. These farmers are part of a coalition that represents 60% of the states production. Abandonment is when farmers plant the crop, but do not harvest it due to low market prices or other market conditions. If this had been a farmer from New Mexico, no one would pay attention. However, Texas is the largest state for U.S. cotton production, by a long shot. Earlier this year we discussed how the flooding there delayed the planting but farmers were still expected to get a full harvest in. Bottom line from this report is that yield per acre is down a bit and the number of planted acres is down significantly. The conclusion I come to is that even if Texas farmers have lower abandonment numbers, they will not be able to completely overcome the overall drop in yield and planted acreage. BAL Let’s view the price action of BAL over the last month: (click to enlarge) Chart obtained from Optionshouse.com Here is another view showing the percentage of change: BAL has been hampered by the continuing decline in crude oil prices. See the crude chart below: I have been in the camp that crude oil is going to rebound to about $60 per barrel by the end of the year. I had sold a few Puts on The United States Oil Fund (NYSEARCA: USO ), but bought them back recently for a small loss. Given the current supply and demand factors and market factors, I don’t know if we will see $60 by years end. Saudi Arabia seems bent on eliminating competition, Iran is coming online, U.S. production has not slowed drastically, and demand has not increased substantially. The U.S. dollar is a wild card with a projected Fed liftoff this September. A stronger dollar means additional pressure on oil. How is all of this affecting BAL? Cotton will face continued price pressure from cheap oil. This presents the case more for a ceiling on spot prices than a floor. I suspect it was the lower prices of crude that swayed farmers to plant more profitable crops this year than the lower spot price of cotton. Oils first plunge this year came right before peak planting season for cotton. Conclusion In closing, I believe the USDA’s numbers and projections are more in line with reality than the Texas farmers are leading you to believe. However, if the farmers can obtain a more reasonable rate for their crop, then naturally abandonment will decrease, further increasing supply. The global supply and demand of cotton remains stable. Stocks are still trending lower off of their all-time highs but are still not being reduced enough to make a substantial impact on the spot price of U.S. cotton and in turn BAL. I would use caution with this current spike in spot prices. I do not see this a buy signal. Given the current state of crude prices, I see higher risks to the downside for cotton going forward. I would keep an eye out for the September USDA reports to see if their current projections hold or are revised. If the Texas farmers are correct about the abandonment, then I see higher than projected production and further downward pressure on spot prices. This would have the opposite effect of the nice green candle you see in the chart above. By November, I hope to have a full report out for you on my 2016 outlook for cotton. I see 2016 as a more profitable year for BAL as lower cotton production reduces supply and we finally see a rebound in crude prices. Crude remains a wild card and anything can happen with the flick of a Middle Eastern switch. If you are investing in BAL your current focus should be the monthly USDA reports (and any other production news) and crude. As we enter peak harvesting season for cotton, those monthly reports are very valuable. As always, I appreciate you reading and I hope you have a profitable end to 2015! Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.