Tag Archives: management

New Normal Income

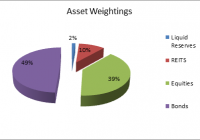
The State Street Fund is mainly comprised of the well-known SPDR ‘Sector Select’ funds. An Income Allocation fund provides better returns than a Government Bond fund. An Income Allocation fund is less risky than a high yield fund. Investors are living in interesting times. Before the 2008 credit crisis, the only mention of deflation might be heard or described in a television documentary. Deflation , as far as most people were concerned, was a thing of the past, the aftermath of an asset bubble combined with a naive economic policy. To be sure, deflation may have faded in living memory, but was still very much a reality of macroeconomics. Since 2008, many advanced global economies have been slipping in and out of deflation and their central banks have been walking a fine line on decisions to direct economic policy. The problem, it seems, is primarily due to a digitally connected, integrated global economy. Disinflation in one region will directly or indirectly affect interest rates and currency values in others. This ‘network effect’ has impacted individual investors who seek relatively safe income. However, to attain reasonable incomes, investors now must venture further out on the risk curve. This begs the question whether there’s some comfortable median, in particular, a way to reasonable returns without incurring high risk. State Street Global Advisors offers investors the opportunity to do just that; earn a steady stream of income with manageable risk through its actively managed SPDR Income Allocation ETF (NYSEARCA: INKM ) . According to State Street the fund’s objective seeks to: Provide total return by focusing on investment in income and yield-generating assets. The fund tracks primarily the MSCI World Index , and secondarily , Barclays U.S. Long Government/Credit Bond Index . According to the prospectus , the fund invests primarily in four different asset classes through exchange traded products (ETP): domestic and international equities; domestic and international investment grade and high yield debt securities; preferred and convertible securities and lastly, real estate investment trusts. Since the fund seeks to achieve its objectives through investments in Exchange Traded Products it is essentially a fund of funds. There are similar funds; however, SPDR’s Income Allocation ETF has the best short and long term returns when compared to the top three similar as summarized below: Fund and Inception 1 Month YTD 1 Year 3 Year Since Inception Types of Holdings SPDR (INKM) 4/25/2012 1.25% -0.35% 1.07% 5.10% 5.46 ETP; Reits convertibles, Equities PowerShares CEF Income Composite Portfolio ETF (NYSEARCA: PCEF ) 2/19/2010 -1.61 0.84 -3.04 5.52 6.41 ETP investment grade funds; high yield funds iShares Morningstar Multi-Asset High Income Index ETF (BATS: IYLD ) 4/3/2012 -0.55 -2.57 -2.65 4.15 5.21 ETPs, high yield fixed income funds (Data From State Street Global Advisor ) T he fund is compact, holding just 21 funds; 17 of those holdings are State Street Advisor’s SPDR funds . Of the top five holdings accounting for nearly half of the fund’s asset allocations, three are SPDR bond funds, one SPDR REIT and the WisdomTree Japan Hedged Equity ETF (NYSEARCA: DXJ ) . (Data from State Street) The fund’s heaviest allocation is in bonds, accounting for nearly half of the funds asset allocation. Of the 7 bond funds, 2 are U.S. Treasury bond funds, 10.83%; 2 are corporate bond funds, 14.32%; 1 high yield fund, 15.79%; 1 emerging market bond fund, 3.05%, and 1 convertible securities fund accounting for 5.08%, of total holdings. Hence, the fund is well diversified over the risk spectrum. The next heaviest allocation is in dividend generating equity funds. Of the 11 equity funds, 6 are international, 22.99%; three are SPDR ‘Select Sector’ funds, 6.09%; one SPDR preferred equity fund, 5.13% and one SPDR dividend fund accounting for 5.11% of the fund’s total holdings. Two SPDR REITs account for 10.27% of the fund’s holdings and lastly 1.34% is classified as ‘liquid reserves’. The question sure to arise is on the usefulness of allocating a fund of funds in a long term portfolio. The question may be answered when the long term investor makes a careful study of the global fixed income market. Most advanced economies are experiencing “disinflation’ or outright “deflation”. In order to prevent a deflationary spiral, central banks have gone to extraordinary lengths to depress deposit rates in order to direct liquidity into economies. These extreme efforts have met with some measure of success, but by far, have not returned fixed income markets to ‘normalcy’. Three recent notable examples of central bank actions in ‘secular stagnation’ economies are for instance, Japan’s unexpected expansion of its bond purchasing program in October of 2014 weakening the Yen to historic lows against major currencies; the ECB’s expansion of its bond purchasing program and depressing its deposit rate to -0.20%; most recently the People’s Bank of China reference rate reductions and an outright devaluation of the dollar pegged currency. The list is long and growing. Worsening the matter has been the commodity market collapse, particularly in crude oil and decelerating global demand. By all indication, the individual investor might, at the very best, expect a gradual return to normalcy, which might take several years. There’s a risk in being locked into historically low yielding high quality sovereign debt at the long end of the curve. Should sovereign rates return to normal after just a few years, the loss of principal on bonds purchased at the highs, would certainly result in a negative yield when held to maturity, particularly should inflation return to a 2% rate. On the other hand, should major global economies continue to struggle to “reflate”, even the most risky high yield bonds will experience declining yields. (click to enlarge) It has often been said that a ‘fund of funds’ results in over-diversification. In a new normal world, a fund of diversified fixed income funds, particularly if it’s actively managed such as the State Street Global Advisors Income Allocation Fund ETF is a far more holding tool for the individual investor, well diversified over many income producing sectors and, most importantly, diversifies risk as well. The fund has total net assets of $118.94 million distributed over the 21 holdings including the liquid reserves. The trailing dividend yield is currently 3.28% and the ETF shares currently are trading at its NAV price, hence neither at a premium nor discount to NAV; there are 3.80 million shares outstanding. The fund has a somewhat high management fee of 0.70% without any mention of waivers or cap. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article. Additional disclosure: CFDs, spread betting and FX can result in losses exceeding your initial deposit. They are not suitable for everyone, so please ensure you understand the risks. Seek independent financial advice if necessary. Nothing in this article should be considered a personal recommendation. It does not account for your personal circumstances or appetite for risk.
Sector ETFs: Current Market-Maker Expectations For Coming Prices

Summary Over two dozen Exchange Traded Funds [ETFs] hold investments focused on broad related industry groups considered to be sectors. Ones intended to track or mimic economic indexes. They provide an easy means of emphasis in a portfolio’s attempt to attain capital growth in excess of that offered by ETFs that track the entire equity market. They present a means of portfolio diversification more concentrated, more precise than groupings by company capital sizes or by artificial, arbitrary accounting “style” definitions of growth or value. Behavioral Analysis of Market-Maker [MM] hedging actions to protect against risks taken in facilitating volume trades for big-$ fund clients reveals coming ETF price expectations. Those forecasts’ qualities are verified by the histories of subsequent market price actions of prior forecasts having similar upside-to-downside expectation proportions. The ETFs being compared here Figure 1 lists the symbols, names, and marketability considerations of the ETFs of interest: Figure 1 (click to enlarge) What may be the customary investor reactions? Some investors are likely to make different preference choices than others in their portfolio emphasis, depending on their time horizons. Long-term speculators (buy&holders) may view the Past Year Volatility and Past Range Index columns as signals of great opportunity in the Energy sector. Whether they would shift capital from Healthcare (high Past Year Volatility and now high Past Year Range Index) into Energy’s low Past Range Index prices is an interesting question. Those who never want to sell anything are likely to hang on to the healthcare gains and hope for recovery in their present badly wounded Energy holdings. The Past Range Index is simply a comparison of that part of the past year’s full price range that is between the current price and the year’s low. A small Past Range Index means the stock is near its year’s low, a large one means the Price Now is near its high. What the investor does with that information may be a “half-full or half-empty” decision: Is a low Past RI a confirmation of continuing trouble, or a big opportunity? Is a big Past RI encouragement for continuation of rewards, or a warning of the potential for loss? Of course, what is needed for an intelligent decision is not a measure of what has already happened, but a measure of what may be coming. Not a past Range Index, but a forecast Range Index. The activist investor’s opportunity/dilemma Making intelligent shifts in a portfolio’s capital assigned to various sectors requires better guidance than can usually be obtained by looking back in time for expectations of what is to come in the future. “Past performance is no guarantee of future results” is the investment lawyer’s security blanket for his employer. True it may be, but that offers little constructive guidance as to what to do about the verity. So, many information venders (and investment managers) take the easy way out. They have observed that if no alternative is readily available, investors will tend to accept the past as the best they have to work from. It’s human nature. And the past information is widely available, cheap and easy to access, and freed from legal liability, so “let ’em play with it.” But it is far from being productive in leading to above average rates of return on equity investments in the future. So, because everyone has it, past checks on its effectiveness as a forecasting means regularly justifies that legal security blanket quoted above. Other human reactions can lead to far more productive thinking, and demonstrate rewarding investment results. One is the natural aversion of humans to being hurt. In the investment game, a universally avoided hurt is loss of capital. Only the brave (speculators) take on the risk of exposure to that kind of hurt. And even then only when they can do it repeatedly under odds that let them exact prices for the service that virtually guarantee them, over a reasonable time, of totally avoiding that possibility of hurt. It’s the Las Vegas casino approach. Or the Investment Bank’s proprietary trading desk approach. Where to find such players on the investing scene? They exist in the Investment Banks, at the Market-Making function. There where big-money investment fund clients repeatedly ask for their help in forcing the gargantuan-sized trades their portfolio sizes require, through the much smaller ordinary transaction windows that serve individual investors adequately most of the time. To get those big trade orders filled usually requires the IB to put some of its firm capital at risk temporarily on the “other side of the trade” from the client. Not as an adversary, but as a transaction facilitator. Back to the hurt-avoidance reaction. The MM protects itself by finding some organization willing to let itself take on the potential price risk the MM wants to avoid. This is a bread-and-butter part of the business that IB prop trading desks thrive on. Their vigorish is ultimately paid by the MM’s client-originator of the trade. Its cost is part of the market liquidity requirement to make desired capital allocation shifts in billion-dollar portfolios. What payments it takes to get the deals done, and the way the hedging deals are structured, tells quite precisely what the participants believe at the time could happen to future prices for the subject securities involved. Contained there are forward-looking forecasts, both of risks and of rewards. Are their forecasts sufficiently accurate to give investing guidance? Here in the discussion it is legitimate to go back to using history, because we have prior examples of forecasts, made in real time of days, weeks, months, and years ago. What happened to prices of the forecast subjects subsequently is a legitimate verification of those implied expectations, not just a projection of past trends. We can look at upside price expectations and see to what extent actual price achievements made them credible. We can compare downside price concerns with worst-case price drawdowns to see what concerns were justified, or perhaps needed to be enlarged. In addition, we can find out what proportion of the forecasts produced winning propositions and infer the odds for success of similar forecasts at present. We can find out what holding periods were required to accomplish targets or to limit risks. Because the forecasting process has been continued daily without change since Y2K, those results may be reasonable reassurances of recurrences. (isn’t alliteration useful?) As long as investors seek to avoid getting hurt, rather than turning masochistic, it ought to be a useful guide. (An aside: Our daily ranking of top-20 stocks and ETFs YTD in 2015 is proving that it is, with 2500+ basis point alphas on over 2,000 closed positions.) All these things are common to any equity investment, making them appropriate dimensions of comparability between all equity investments. That makes unnecessary our rediscovery of the minutia needed by parties to the hedging deal to reach their conclusions. They have done the heavy research lifting for us. What do their forecasts indicate now? Figure 2 is a map of Reward~Risk comparisons between the ETFs in Figure 1. Forecast upside price prospects are on the horizontal green scale at bottom, and actual worst-case price drawdown experiences are measured by the red vertical scale. We use the average worst experiences of prior similar forecasts because they are typically more extreme than the forecast downsides. Figure 2 (used with permission) Looking like the germ that caught penicillin, the SPDR S&P Metals and Mining ETF (NYSEARCA: XME ) at [12], the metals & mining ETF, reflects the volatility of its precious metals holdings more than interests in its base metals. The Vanguard Financials ETF (NYSEARCA: VFH ) at [10] offers the most attractive risk-reward tradeoff, while the Vanguard Information Technology ETF (NYSEARCA: VGT ) at [17] or the Vanguard Utilities ETF (NYSEARCA: VPU ) at [18] has the most price drawdown exposure for the upside payoff being offered. This map contrasts the risk and reward dimensions often most critical to investment selection decisions. But there are other qualitative considerations that enter into good choices of emphasis in portfolio management. They are detailed in Figure 3, along with their parallels of the 2400+ stocks and ETFs in our survey population, the 20 most attractive of that group today, and the MM forecasts for the SPDR S&P 500 Trust ETF (NYSEARCA: SPY ) as a proxy for the most widely-regarded market index. Figure 3 (click to enlarge) These sector ETFs have been ranked by attractiveness on a wealth-building basis. The ranking measure is in column (15) at right. It odds-weights the prospective upside price rewards of (5) with the Win Odds of (8), and the risk exposures of (6) with the complement of (8). Emphasis of frequency of opportunity indicated in the count of prior forecasts (12) having the balance between upside and downside of (7) and conditioned by credibility comparisons of (5) with (9) all enter into the measure. We include all of the factors because different investment objectives and investor preferences may call for alternative importance weightings. Conclusion What may be evident in the blue summary rows at the bottom of the Figure 3 list is that sector investing by across the board use of these 32 ETFs might produce an ultra-conservative portfolio, given current-day prices and MM expectations. The blue-row average payoffs of 2.6% in (9), resulting from prior Forecast Range Indexes (7) like today’s, have been only half of the 5.3% hoped for in (5). That suggests this may not be a wonderfully opportune market environment for fresh broad-brush capital commitments. The next blue row down shows the averages of a ranked selection of the 20 best choices (for wealth-building) equity investments from our large (2475) population of currently available MM price range forecasts. They offer expected +10% gain opportunities that have been more than realized previously. Their win rate of profitable recovery from worst price drawdowns (6) has been of 7 out of every 8 commitments. Average holding periods of 37 calendar days, less than two months, produce annual gain rates of +101%, 6 times the +17% prospect of the average sector ETF in the row above. Differences of this type are not unusual and make passive investing strategies uncompetitive for investors with capital-building objectives constrained by time. Sector ETFs likely to be most favored by wealth-builders today lean to health-care, consumer, financials, and technology orientations. None are outstanding in comparison with the average of the larger population’s best 20, except in the odds of profitable recovery from bad price experiences. But the cost of that advantage in rate of return give-up is quite high. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.

VCR: An ETF For Both Traders And Long-Term Investors

Summary The sector specific exposure makes the ETF a reasonable pick for investors who expect the sector to outperform. The low expense ratio makes it a viable long-term holding for the buy and hold investor. The biggest weakness for a buy and hold strategy here is that the dividend yield would be insufficient to provide retirement income without an enormous portfolio. Investors should be seeking to improve their risk adjusted returns. I’m a big fan of using ETFs to achieve risk-adjusted returns relative to the portfolios that a normal investor can generate for themselves after trading costs. I’m working on building a new portfolio and I’m going to be analyzing several of the ETFs that I am considering for my personal portfolio. A substantial portion of my analysis will use modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. In this article, I’m reviewing the Vanguard Consumer Discretionary ETF (NYSEARCA: VCR ). Does VCR provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use the SPDR S&P 500 Trust ETF (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. The correlation is about 88%, which is low enough that I’m expecting some diversification benefits, but I would not expect it to be dramatic. Standard Deviation The standard deviation of annualized returns for VCR was 12.8% compared to SPY at 12.1%. So VCR is slightly more volatile but using it as a small part of a portfolio would get past even that problem. For instance, using VCR at 10% would have brought the annualized volatility down to 12.0%. Yield and Taxes The distribution yield is 1.11%. Simply put, the ETF doesn’t make much sense for retiring investors who want to use portfolio yields as a large part of their retirement income. Sure, they could sell shares to generate income, but that may create a temptation to change the portfolio strategy at the wrong time. Expense Ratio The ETF is posting 0.12% for an expense ratio. That is not bad compared to other ETFs, though it is slightly higher than SPY at 0.09% and higher than a few of the other more popular Vanguard ETFs. Market to NAV The ETF is trading at a 0.02% premium to NAV currently. I don’t see that as being a big enough issue to matter. A few very small ETFs may see their values deviating from NAV but this Vanguard fund should be staying very close to NAV. Largest Holdings The diversification within the ETF would be weak compared to a whole market ETF, but given that this is a specific sector allocation for consumer discretionary stocks, the diversification is better than many investors might expect. (click to enlarge) Through diversification it may be possible (just barely) to lower portfolio risk by adding the ETF due to the correlation. However, the most logical argument for adding the ETF to the portfolio is an investor believing that this sector is set to outperform based on analysis of macroeconomic factors. A belief that the sector is likely to do well would be a great rationale for holding the ETF; however, it would imply more of a short to intermediate term trading mentality rather than a long-term core holding. Does That Make it Bad for Retail Investors? I would not go that far. The volatility is reasonable and the expense ratio is low. So long as the expected returns are keeping up with the market, there is no reason to say the portfolio is unsuitable for a long-term buy and hold investor. I think it makes an ideal fit for a trader who is moving their assets based on macroeconomic analysis, but it is still a reasonable option for the buy and hold investor as well. The thing those investors should remember is to take advantage of the benefits of lower correlation by rebalancing their portfolio. If it is tax exempt, that could be accomplished easily by buying and selling. If the portfolio is not tax exempt, it may be better to adjust exposure by simply adding cash and buying the fund that has fallen below the ideal weighting. Conclusion This is a solid all-round ETF for any investor who wants to add an emphasis on the “consumer discretionary” sector to their asset allocations. As a sector ETF, it would work well for traders, but the low expense ratio and reasonable level of volatility make it a fine choice for the long-term buy and hold investor as well. The one concern for the buy and hold investor may be the weak dividend yields which would be insufficient for retirement income. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis.