Tag Archives: investing ideas

Building The Core With Vanguard: Foreign Stocks
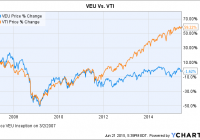
Summary Every ETF investor needs to consider what holdings will form the very core of their portfolio. For the portion relating to foreign stocks, the Vanguard FTSE All-World ex-US ETF is a compelling choice. Also discussed are reasons every investor should consider holding foreign stocks in their portfolio, along with links to additional background reading for those who desire such. For my first articles for Seeking Alpha, I decided to start simple: tackling the question of building a solid core portfolio using ETFs offered by Vanguard Funds. I started with domestic stocks featuring the Vanguard Total Stock Market ETF (NYSEARCA: VTI ), followed by domestic bonds featuring the Vanguard Total Bond Market ETF (NYSEARCA: BND ). As can quickly be discerned, however, both of the above options relate to U.S.-centric investments. For their portfolio to be complete, investors should also seriously consider going beyond the borders of the U.S. and into the world of foreign equities. For your first venture into this brave world, the Vanguard FTSE All-World ex-US ETF (NYSEARCA: VEU ) makes an excellent choice. Why Foreign? Why Now? For an overview of the risks and benefits of investing in foreign stocks, I offer this article from my personal blog. It offers a relatively brief, yet comprehensive overview, supported by links to further reading if desired. Essentially, what you will read there is that foreign stocks offer two potential benefits, growth and diversification . Hopefully, this material will answer that first question, Why Foreign? But what about that second question, Why Now? I hope to write about the concept of rebalancing one’s portfolio in a future article. But for now, let me just say that a key to good portfolio management is to “sell high and buy low;” in other words, to take a certain portion of your investments out of asset classes that have outperformed and put them to work in asset classes that have underperformed. With that in mind, have a look at the graph below. It compares Vanguard’s VTI (Domestic Stocks) with the ETF featured in this article, VEU, since VEU’s inception on March 2, 2007: VEU data by YCharts Do you notice anything interesting about that chart? I thought you might. After a period of relatively similar performance between roughly 2007 and 2012, U.S. stocks have outperformed their foreign brethren by a fairly significant margin. Further, foreign stocks have been roughly flat over the roughly 8-year span covered by the chart, while U.S. stocks have risen almost 60%. Let me be clear, there have doubtless been good reasons for this. While the U.S. economy has struggled, in particular since 2008, other countries have done even worse. Further, I am in no way predicting that foreign stocks will outperform their U.S. brethren moving forward. I don’t have a crystal ball. However, based on an analysis similar to this that I performed approximately two months ago, I decided to lower my personal weighting in U.S. stocks by 2.5% and shift those funds to foreign stocks. Certainly, this is no dramatic move. I simply decided that I wished to take a little from the asset class that had experienced significant gains and move it to the class that had been flat. With that big picture background, let’s now turn to the composition of VEU, as well as the expense ratio. Composition VEU is named well (Vanguard FTSE All-World ex-US ) because, as it happens, that is the name of the index it tracks. As such, VEU offers incredibly broad and diversified foreign exposure. As of the latest factsheet , we find that VEU actually contains a slightly greater number of securities than the index, 2,492 vs. 2,377. Let’s look a little closer. First, here is the fund’s geographic allocation: As you can see, the fund leans heavily toward developed markets such as Europe and the Pacific (Asia). At the same time, it offers reasonable exposure to emerging markets; those whose economies are not as fully developed and therefore offer greater potential for growth, albeit with a greater level of risk. If you back out the 18.8% in emerging markets, you quickly realize that 81.2% of the fund is invested in what are generally considered developed markets. Diving in a little more specifically, here are the Top 10 countries represented in the fund. If you add up the numbers, you will see that these countries comprise 73.4% of the total. Of these, China is the only country included in the Vanguard FTSE Emerging Markets ETF (NYSEARCA: VWO ). Let’s now take a look at one last perspective, the Top 10 holdings: To give you some small sense of the sorts of companies that constitute the largest portions of the fund, here are extremely brief synopses of the Top two; Nestle SA ( OTCPK:NSRGY ) and Novartis AG (NYSE: NVS ): Nestle SA – Nestle is the largest food company in the world , measured by revenues. Encompassing baby food, bottled water, coffee & tea, dairy products, frozen food, pet food, snacks and more. The list of brands is made up of legendary names that you will instantly recognize, and Wikipedia states that 29 of these brands each have annual sales of over $1 billion. The company operates in 197 countries, with factories in 86 countries. Novartis AG – Novartis is the largest pharmaceutical company in the world , measured by revenues. According to its latest annual report , Novartis’ products are available in more than 180 countries worldwide. Its pharmaceuticals arm has 135 projects in development, its subsidiary Alcon is the #1 eye care company worldwide, and its subsidiary Sandoz is the #2 global provider of generic medicines. Looked at from any of these vantage points, I submit that VEU is a wonderful core holding for the foreign, or international, component of your portfolio. Costs and Expenses At 0.14%, VEU’s expense ratio is somewhat higher than that of either VTI or BND, the other two ETFs I have featured. And yet, it too is one of the lowest in the industry. Bear in mind, this is an ETF that is dealing with assets all over the world, across different stock exchanges and the like. To that, of course, you have to add your trading commissions. Vanguard offers its own ETFs commission-free, and TD Ameritrade offers a decent selection of commission-free Vanguard ETFs. Suitability As a core holding, VEU is suitable for all portfolios. While I do believe that all investors should hold at least some portion of their portfolio in foreign stocks, I understand that you must do so at a level at which you are comfortable. Alternatives Another ETF worth considering, particularly if your brokerage offers it commission-free, is the iShares Core MCSI Total International Stock ETF (NYSEARCA: IXUS ). It too sports a very competitive 0.14% expense ratio, and covers basically the same range of countries, including emerging markets, as does VEU. The ETF’s size, as well as its average trading volume, is substantially smaller than VEU, but I do not believe this should be any impediment. As a Fidelity client, I use VEU for my core position and IXUS, which I can trade commission-free, for small incremental investments and/or to adjust portfolio weightings. Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks. Disclosure: I am/we are long BND, IXUS, VEU, VTI, VWO. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article. Additional disclosure: I am not a registered investment advisor or broker/dealer. Readers are advised that the material contained herein should be used solely for informational purposes, and to consult with their personal tax or financial advisors as to its applicability to their circumstances. Investing involves risk, including the loss of principal.
X-Raying CEFL (Part 3): Interest Rate Sensitivity

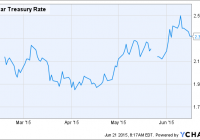
Summary Previous articles in this series investigated the leverage, expense ratio and geographical statistics of CEFL, a 2X leveraged CEF fund-of-funds. This article seeks to analyze the interest rate sensitivity of CEFL by comparing the performance of different classes of CEFs during the interest rate spike of 2015. How sensitive is CEFL to rising interest rates? Introduction This is Part 3 of a series of articles designed to “X-ray” into the holdings of the ETRACS Monthly Pay 2xLeveraged Closed-End Fund ETN (NYSEARCA: CEFL ) to allow investors to better understand the characteristics of the fund. CEFL tracks twice the monthly return of the ISE High Income Index [YLDA], an index that is comprised of high-yielding close-ended funds [CEFs]. The methodology used to construct YLDA has been summarized here . The YieldShares High Income ETF (NYSEARCA: YYY ) tracks the same index as CEFL. In the first article , the equity/debt, leverage and expense ratio of CEFL was analyzed. In the second article , the geographical allocation of CEFL was discussed. In the comment streams of the first two articles, I received a number of comments asking about the interest rate sensitivity of CEFL. This is an especially pertinent question given the mini-“Taper tantrum” that has occurred in early 2015. As the chart below shows, the U.S. 10-year treasury rate has increased from around 1.70% to a peak of 2.50% over short span of less than 6 months. 10 Year Treasury Rate data by YCharts Over the same time period, CEFL has dropped by -3.87% in price, although its total return has been +3.13% after dividends are accounted for. This suggests that CEFL has been holding up quite well despite the recent spike in interest rates. CEFL data by YCharts In this third article, I seek to analyze the debt holdings of CEFL to see how individual classes of CEFs fared during the recent interest rate spike. Methodology CEFL contains 30 CEFs, of which 7 are equity funds, 21 are debt funds and 2 are mixed funds. For this analysis, I only included the 21 debt funds as bonds are more sensitive to fluctuations in interest rates compared to stocks. For each debt CEF, I assigned it a primary classification for its largest type of debt holding (usually 40-100% of the total fund assets). I also assigned the CEF a secondary classification if its second-largest type of debt holding was at least 20% of the total fund assets. The classification types are: [i] corporate bonds [corp], [ii] government bonds [gov], [iii] securitized bonds [sec], which include various agency/commercial mortgage or asset-backed bonds, [iv] senior loans [loan], [v] convertible bonds [CB], and [vi] preferred shares [PF]. Note that this classification does not distinguish between U.S. and foreign bonds. The primary and secondary classifications of the 21 debt funds are shown in the table below. Fund Ticker Assets Primary Secondary DOUBLELINE INCOME SOLUTIO (NYSE: DSL ) 4.38% Corp Sec FIRST TRUST INTERMEDIATE (NYSE: FPF ) 4.28% Pref   EATON VANCE LIMITED DURAT (NYSEMKT: EVV ) 4.26% Loan Sec MFS CHARTER INCOME TRUST (NYSE: MCR ) 4.24% Corp Gov BLACKROCK CORPORATE HIGH (NYSE: HYT ) 4.20% Corp   WESTERN ASSET EMG MKT DBT (NYSE: ESD ) 4.18% Gov Corp PRUDENTIAL GL SH DUR HI Y (NYSE: GHY ) 4.11% Corp Gov PIMCO DYNAMIC CREDIT INCO (NYSE: PCI ) 4.11% Sec Corp MORGAN STANLEY EMERGING M (NYSE: EDD ) 3.88% Gov   ABERDEEN ASIA-PAC INCOME (NYSEMKT: FAX ) 3.43% Gov Corp PRUDENTIAL SHORT DURATION (NYSE: ISD ) 3.15% Corp   MFS MULTIMARKET INC TRUST (NYSE: MMT ) 2.84% Corp   BLACKSTONE/GSO STRATEGIC (NYSE: BGB ) 2.65% Loan Corp ALLIANZGI CONVERTIBLE & I (NYSE: NCV ) 2.42% CB Corp WESTERN ASSET HIGH INC FD (NYSE: HIX ) 2.19% Corp   BLACKROCK MULTI-SECTR INC (NYSE: BIT ) 1.89% Sec Corp WELLS FARGO ADV MULTISECT (NYSEMKT: ERC ) 1.56% Corp Gov ALLIANZGI CONV & INCOME I (NYSE: NCZ ) 1.35% CB Corp WELLS FARGO ADVANTAGE INC (NYSEMKT: EAD ) 1.33% Corp   NUVEEN PFD INC OPP FD (NYSE: JPC ) 1.12% Pref   INVESCO DYNAMIC CREDIT OP (NYSE: VTA ) 0.96% Loan Corp The performance of each class of debt CEF during the current interest rate spike (Feb. 1, 2015 to date) is compared with a benchmark ETF as identified using the correlation tool from InvestSpy . Corporate bonds 9 of the debt CEFs have corporate bonds as their primary holding, while 8 CEFs have corporate bonds as their secondary holding. All 9 debt CEFs that have corporate bonds as their primary holding are most correlated with the iShares iBoxx $ High Yield Corporate Bond ETF (NYSEARCA: HYG ). The following chart illustrates the 1-year correlation coefficients for these 9 funds arranged from highest to lowest correlation. The following chart shows the total return performance of the 9 debt CEFs with corporate bonds as their primary holding during the most recent interest rate spike compared to HYG from Feb. 1, 2015 to date. HYG Total Return Price data by YCharts We can see from the chart above that DSL has had the best total return performance of +4.98%, while GHY had the worst performance of -4.33% since Feb. 1, 2015. The average of the 9 CEFs was +0.28%, while the benchmark index HYG returned +1.14%. This indicates that the 9 debt CEFs with corporate bonds as their primary holding slightly underperformed the benchmark HYG over this time period. Government bonds 3 of the debt CEFs have government bonds as their primary holding, while 3 CEFs have government bonds as their secondary holding. Of the 3 debt CEFs that have government bonds as their primary holding, ESD and EDD are most correlated with the iShares J.P. Morgan USD Emerging Markets Bond ETF (NYSEARCA: EMB ), with 1-year coefficients of 0.51 and 0.60, respectively, while FAX is most correlated with HYG, with a coefficient of 0.29. Note that all three CEFs are actually either emerging market (ESD, EDD) or Asia-Pacific bond funds. The following chart shows the total return performance of the 3 debt CEFs with government bonds as their primary holding during the most recent interest rate spike compared to EMB and HYG from Feb. 1, 2015 to date. ESD Total Return Price data by YCharts We can see from the chart above that ESD has had the best total return performance of +0.67%, while EDD had the worst performance of -12.80% since Feb. 1, 2015. The average of the 3 CEFs was -6.22%, while the benchmark indices EMB and HYG returned +0.23% and +1.14%, respectively. This indicates that the 3 debt CEFs with government bonds as their primary holding significantly underperformed the benchmarks EMB and HYG over this time period. Senior loans 3 of the debt CEFs have senior loans as their primary holding. All 3 debt CEFs that have senior loans as their primary holding are most correlated with HYG. EVV, BGB and VTA have 1-year correlation coefficients to HYG of 0.40, 0.40 and 0.28, respectively. The following chart shows the total return performance of the 3 debt CEFs with senior loans as their primary holding during the most recent interest rate spike compared to HYG from Feb. 1, 2015 to date. The PowerShares Senior Loan Portfolio (NYSEARCA: BKLN ) is included for comparison. EVV Total Return Price data by YCharts We can see from the chart above that VTA has had the best total return performance of +5.35%, while EVV had the worst performance of +1.65% since Feb. 1, 2015. The average of the 3 CEFs was +3.53%, while the benchmarks HYG and BKLN returned +1.14% and +0.66%. This indicates that the 3 debt CEFs with senior loans as their primary holding significantly outperformed the benchmarks HYG and BKLN over this time period. Preferred shares 2 of the debt CEFs have preferred shares as their primary holding. JPC is most correlated with HYG (0.36), whereas FPF is, somewhat strangely, most correlated with the PowerShares Emerging Markets Sovereign Debt Portfolio (NYSEARCA: PCY ) (0.33). Therefore I have replaced PCY with the iShares U.S. Preferred Stock ETF (NYSEARCA: PFF ) in the following chart. JPC Total Return Price data by YCharts We can see from the chart above that JPC has had the best total return performance of +2.47%, followed by FPP at +0.26% since Feb. 1, 2015. The average of the 2 CEFs was +1.37%, while the benchmarks HYG and BKLN returned +1.14% and +0.11%. This indicates that the 2 debt CEFs with preferred shares as their primary holding slightly outperformed the benchmarks HYG and PFF over this time period. Convertible bonds 2 of the debt CEFs have convertible bonds as their primary holding. NCV and NCZ are both most correlated with the SPDR Barclays Convertible Securities ETF (NYSEARCA: CWB ), with 1-year correlation coefficients of 0.40 and 0.34, respectively. The following chart shows the total return performance of the 2 debt CEFs with convertible bonds as their primary holding during the most recent interest rate spike compared to CWB from Feb. 1, 2015 to date. NCV Total Return Price data by YCharts We can see from the chart above that NCV has had the best total return performance of -1.00%, followed by NCZ at -5.89% since Feb. 1, 2015. The average of the 2 CEFs was -3.45%, while the benchmark CWB returned +5.22%. This indicates that the 2 debt CEFs with convertible bonds as their primary holding significantly underperformed the benchmark CWB over this time period. Securitized bonds 2 of the debt CEFs have securitized bonds as their primary holding, while 2 CEFs have securitized bonds as their secondary holding. The 2 debt CEFs that have securitized bonds as their primary holding as both most correlated with HYG, with PCI and BIT having 1-year correlation coefficients of 0.54 and 0.44, respectively. The following chart shows the total return performance of the 2 debt CEFs with securitized bonds as their primary holding during the most recent interest rate spike compared to HYG from Feb. 1, 2015 to date. The iShares MBS ETF (NYSEARCA: MBB ) and the iShares CMBS ETF (NYSEARCA: CMBS ), which hold agency and commercial mortgage-backed bonds, respectively, are shown for comparison. PCI Total Return Price data by YCharts We can see from the chart above that PCI has had the best total return performance of +2.06%, followed by BIT at -0.33% since Feb. 1, 2015. The average of the 2 CEFs was +0.87%, while the benchmarks HYG, MBB and CMBS returned +1.14%, -0.50% and -1.32%, respectively. This indicates that the 2 debt CEFs with securitized bonds as their primary holding slightly outperformed the benchmark HYG over this time period. Discussion What does this all mean for investors? One major finding that resulted from this analysis is that most of the CEF debt classes in CEFL (including corporate bonds, senior loans, preferred shares and convertible bonds)* are most correlated with the high-yield ETF HYG. This bodes well for investors in CEFL who are worried about rising interest rates since high-yield debt is less interest-rate sensitive compared to investment-grade debt. (*Note that BKLN and PFF did not show up in the top-10 ETFs most correlated with the senior loans or preferred shares CEFs, respectively, indicating that InvestSpy might have for some reason excluded these ETFs from its correlation tool.) Indeed, inputting CEFL into the Investspy’s correlation tool indicates that has been the most correlated with HYG, EMB, JNK, PCY and CWB over the past 1-year, as shown in the chart below (but note that the past 1 year includes the final six months of 2014 which are before the rebalancing of CEFL to its present constituents). Encouragingly, all five of these ETFs and CEFL have outperformed the iShares iBoxx $ Investment Grade Corporate Bond ETF (NYSEARCA: LQD ) (-4.75%), the iShares 7-10 Year Treasury Bond ETF (NYSEARCA: IEF ) (-3.46%) and the iShares 20 Year Treasury Bond ETF (NYSEARCA: TLT ) (-12.7%) during the interest rate spike of 2015. This is not surprising because investment-grade debt and treasuries are much more sensitive to interest rates, as mentioned above. The total return performances of these ETFs are shown in the chart below. CEFL Total Return Price data by YCharts In terms of the individual debt classes of CEFL, CEFs with corporate bonds (as their primary holding) averaged +0.28%, government bonds averaged -6.22%, senior loans averaged +3.53%, preferred shares CEFs +1.37%, convertible bonds -3.45%, and securitized bonds +0.87% since Feb. 1st, 2015. The strongest performance of senior loan CEFs (+3.55%) may be rationalized by the fact that these are normally floating-rate instruments that may benefit as interest rates rise, although it should also be noted that the benchmark ETF BKLN was essentially flat over this time period. A quick check on CEFConnect shows that the premium/discount of the three senior loan CEFs (EVV, BGB, VTA) was steady over this time period, suggesting either that the CEF managers were able to outperform the benchmark or that the other components in the CEFs were responsible for the outperformance. Conversely, the weakest performance of the government bond CEFs (-6.22%) may also be understood on the basis that this debt is relatively interest rate-sensitive, although again the benchmark index EMB was actually also flat over this time period. This time, however, the discounts for the three CEFs in question (FAX, ESD, EDD) actually widened by about 2 to 4 percentage points over this time period, indicating that the discount expansion could account for a significant fraction of the underperformance of these CEFs. Moreover, this observation indicates investor pessimism regarding these CEFs, which are actually all emerging market or Asia-Pacific bond funds. The total return performance of the six classes of debt CEFs within CEFL since Feb. 1st, 2015 are summarized in the chart below. Conclusion Based on this analysis of CEF performances during the interest rate spike of 2015, I conclude that CEFL is not very interest rate-sensitive, and investors therefore do not have to unduly worry over the effect of increasing interest rates on CEFL. The main findings supporting this conclusion are: Most of the holdings of CEFL are most-correlated with high-yield debt, which is not very interest rate-sensitive. The five ETFs that are most correlated with CEFL all outperformed investment-grade bonds LQD and treasuries IEF and TLT since Feb. 1, 2015. CEFL itself outperformed LQD, IEF and TLT over the same time period. CEFL contains three senior loan CEFs, which are typically floating rate instruments, and these may provide protection against increasing interest rates. The main limitations of this analysis are: The premium/discount of the individual funds were not studied. Seeking Alpha contributor Lance Brofman has calculated the overall discount of CEFL to be 9.5% on Jun. 1, 2015, an increase compared to 8.6% a month prior, but the overall discount on Feb. 1, 2015 was not determined. The 10-year treasury rate increased from 1.70% to a peak of 2.50% over the past 5 months. Therefore, this analysis may not be valid for interest rate increases that are much greater in magnitude or velocity (although this seems to be an unlikely scenario at the present time). This analysis is only valid until Dec. 31, 2015, when CEFL becomes repopulated with different CEFs due to rebalancing. Finally, as a 2X leveraged fund, the cost of maintaining the leverage of the CEFL (based on 3-month LIBOR) would go up as interest rates rise. While not having an immediate effect on NAV, this effectively increases the total expense ratio of the fund, leading to a drag on NAV over time. I hope this information will be helpful for investors in or considering investing in this fund. Disclosure: I am/we are long CEFL. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.

Whats Wrong With Emerging Markets ETFs?

Summary Major Emerging Markets ETFs (EEM & VWO) are investing in the “legacy economy” and not in the “new economy”. Government owned Chinese banks, Brazilian oil companies and Russian resource companies dominate major ETFs. BABA, BIDU, MELI, YNDX and other US listed EM E-commerce companies are NOT in EEM & VWO. What’s wrong with Emerging Markets ETFs? After years of poor relative returns investors have become disinterested and disenchanted with the leading Emerging Markets ETFs ( EEM , VWO ). While the U.S. stock market has made new highs and posted double digit returns, Emerging Markets haven’t done much, leading many investors to question the value of their Emerging Markets allocations. Adding to the woes are headline risks that are really in the headlines as revolution, war, fraud and corruption have either happened in the recent past or are happening right now. But maybe there is a bigger problem. In spite of all the turmoil and risk, Emerging Markets are growing. In fact they are growing at twice the pace of the U.S. and the rest of the developing world. And some countries and sectors within Emerging Markets are growing at quite spectacular rates. But why then aren’t the indexes and ETFs that track Emerging Markets performing better? A closer look at the indexes reveals some major flaws in the largest Emerging Markets ETFs. SOEs are Not Seeking Alpha Weighing most heavily on the indexes is their enormous allocation to state-owned enterprises (SOEs) which account for nearly 30% of the weight of the largest Emerging Markets ETFs. These companies represent the past of Emerging Markets, but not the future. The largest of these SOEs are Chinese, Brazilian and Russian state owned banks and oil companies. Many adjectives describe SOEs including, monolithic, inefficient, conflicted and corrupt. You don’t need not look far to see the problems with investing in SOEs. Recent news has been filled with reports of the investigation of top Brazilian government officials suspected of plundering state-owned oil giant PetroBras of over $1 billion in kickbacks and bribes. The Chinese government has launched a campaign to return 150 “economic fugitives” living in the U.S. who have fled China after allegedly looting or defrauding state owned businesses. And in Russia, where do you even start? Is South Korea Twice as Big as India? Less widely recognized are some of the other factors that can distort the indexes. Traditional index construction methodology uses market capitalization to determine weightings, an approach that in Emerging Markets tends to overweight countries with large banks and financial companies and small populations. As a result, countries like South Korea and Taiwan end up with about twice the weight of India in the major Emerging Markets despite the fact that India has 25 times the population of Korea and 50 times that of Taiwan. Does that make sense? (click to enlarge) Source: Big Tree Capital LLC (click to enlarge) Source: Big Tree Capital LLC How are 3.4 million Rich People 26% of “the Next Emerging Markets”? Things get even worse in so-called Frontier Markets indexes and ETFs. While often dubbed as “the next Emerging Markets” by the fund companies, Kuwait, with a population of only 3.4 million and per capita GDP on par with the U.S. comprises 26% of the largest Frontier Markets ETF (NYSEARCA: FM ). How much room for growth is there with 3.4 million rich people? Meanwhile, Nigeria, with a population of 173 million gets only a 10% weighting. (click to enlarge) Source: Big Tree Capital LLC (click to enlarge) Source: Big Tree Capital LLC Where the Growth is in Emerging Markets Most Emerging Markets investors know that the real growth opportunity in Emerging Markets is the growth of the consumer class. There are dozens of studies and reports published by investment banks, consulting firms and fund companies describing how billions of humans are moving from subsistence income levels to levels where they begin to consume more and better food, clothing, appliances, cars, etc. It’s a very good story. It’s a big story. In a report titled “Going for Gold in Emerging Markets” McKinsey & Co concludes that the growth of consumption in Emerging Markets is “the biggest growth opportunity in the history of capitalism.” Yet, in the major Emerging Markets ETFs, the consumer sector gets a meager 16% weighting. EEM & VWO are Missing the Best Part Finally and importantly, the major indexes and ETFs are largely missing out on something big that is just starting. As the Emerging Markets consumer wave hits, another wave has formed and is gathering momentum. All over the developing world, consumers are getting internet access via wifi and mobile broadband. At the same time, a new breed of manufacturers is offering smartphones for as low as $40. And prices are going to keep dropping. Consider the case of Xiaomi – a Chinese manufacturer of entry level smartphones. The company – which is less than five years old – will sell about 100 mm smartphones this year, up from 60 million units sold in 2014. In the next 5 years a billion consumers will emerge with a $40 smartphone in their hands. The result of this trend is significant revenue growth and value creation. Estimates are that Ecommerce in Emerging Markets has grown at an average of 41.5% for the past five years. And, while this rate is sure to slow, it still clocked an impressive 39.9% growth in 2014. (click to enlarge) Source: EMQQ Index Yet, Alibaba (NYSE: BABA ), MercadoLibre (NASDAQ: MELI ), Baidu (NASDAQ: BIDU ), JD.com (NASDAQ: JD ), Yandex (NASDAQ: YNDX ), 58.com (NYSE: WUBA ) and most of the 50+ publicly traded Emerging Markets Ecommerce companies benefiting from this growth are not in EEM or VWO because they choose to list on U.S. exchanges. The companies are essentially being “punished” from an indexing perspective for listing on the exchanges that will give investors greater liquidity and transparency than their “home” markets. In short, the major ETFs and indexes are leaving out the future. Investors Should Move On Investors using ETFs to gain exposure to Emerging Markets should re-evaluate their allocations. Using legacy indexes and ETFs that provide exposure to the entire universe of Emerging Markets companies may not be the best way to benefit from the growth of Emerging Markets. Investors should concentrate on identifying the Emerging Markets ETFs that provide them with targeted exposure to sectors and companies that are both growing and seeking to maximize shareholder value. Disclosure: I am/we are long EMQQ, BABA, BIDU, YNDX, WUBA, JD, MELI. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article. Additional disclosure: I have created an Emerging Markets Internet & Ecommerce Index. The index has been licensed as the basis for EMQQ The Emerging Markets Internet & Ecommerce ETF (NYSE:EMQQ). I receive a licensing fee from the ETF.