Tag Archives: investing ideas

China Grabs A Bigger Share Of The Indexes

Traditional international index funds assign a weight to each country based on the size of its stock market. But in the case of China, that’s a bit misleading. Despite having the world’s second-largest economy, China has a relatively small number of publicly traded companies. Moreover, many of those publicly traded companies have been off-limits to foreign investors. As a result, the Vanguard Total World Stock ETF (NYSEARCA: VT ) allocates just 2.5% to China—considerably less that than the share allotted to much smaller economies such as Canada, Switzerland and France. This is about to change: during the coming months and years, index investors will be able to access more of China’s vast economy. Vanguard recently announced that its flagship emerging markets ETF, the Vanguard FTSE Emerging Markets (NYSEARCA: VWO ), will soon be adding China A-shares to its benchmark index. This development will also affect Canadian-listed ETFs that include this fund as an underlying holding. Taking the A-train Let’s look at what this means for indexers. Right now, most foreign investors can buy public companies in mainland China only through share classes denominated in foreign currency and traded on exchanges outside the country, particularly in Hong Kong and the US. These are the shares included in the emerging markets funds that North Americans own today. A-shares, by contrast, are denominated in renminbi and are listed on China’s national stock exchanges in Shanghai and Shenzhen. They are generally available only to Chinese nationals and a small number of highly regulated foreign institutional investors. But this regime is changing as China begins to loosen its control over foreign investment. That has prompted index providers to consider adding A-shares to their popular emerging markets indexes. FTSE (the index provider for many Vanguard funds) has already done so , and MSCI (whose indexes are tracked by iShares and BMO funds) seems likely to do so this year. As the index changes unfold, ETFs tracking these benchmarks will be compelled to add Chinese A-shares as well. The upshot is that China will get an increasingly large share of cap-weighted indexes. It won’t happen overnight: Morningstar estimates the changes will bump up China’s allocation in the FTSE Emerging Markets Index by a modest three percentage points in the near term, from about 29% to 32%. But over time it seems likely that share will grow considerably as additional A-shares become available to foreign investors. This evolution will affect the Canadian-listed Vanguard FTSE Emerging Markets (VEE) , since this fund uses VWO as its underlying holding. It will also have a modest effect on the Vanguard FTSE All-World ex Canada (VXC) , which gets its emerging markets exposure from VWO . It seems likely that emerging markets index funds from other providers will also see similar changes in the future, including the iShares MSCI Emerging Markets (XEM) and BMO MSCI Emerging Markets (ZEM) , which both track the same benchmark. What’s it all mean? So what’s the takeaway message for Couch Potato investors who have some emerging markets in their portfolios? At this point, it’s hard to know what effect the addition of Chinese A-shares will have, but it’s likely to be very small. It should not prompt you to make any changes in your portfolio. Let’s remember that the allocation to Chinese A-shares in a balanced portfolio will be trivially small—Vanguard estimates they will make up 0.55% of VXC , which itself is less than half of a balanced ETF portfolio. Taking a longer view, passive investors should generally applaud any index changes that better represent the global markets. As Forbes puts it, including China’s A-shares in widely used emerging markets indexes is “acknowledging that the Chinese mainland stock market has matured and is ready for serious, long term investors.”
Peru: Recovery And Growth Ahead

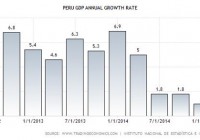
Summary Peru has consistently been one of the best performing countries in Latin America. The country is on track for recovery from decreased GDP growth experienced in 2014 and the beginning of 2015. The currently valuation of the iShares MSCI All Peru Capped ETF, combined with the future potential for growth, makes it a current attractive buy. The mining and banking industries will experience significant growth in the future; around 78% of the fund’s assets are invested in these industries. For those bullish on Latin America and searching for opportunities in this geographical location, Peru may be one of the best options at the moment. The best way to gain access to Peru is through the iShares MSCI All Peru Capped ETF (NYSEARCA: EPU ). In addition to the fund being attractively valued, with a P/E ratio of 12 , it is also trading very close to its 52 week low. Examining economic development in Peru, it is clear that growth is ahead and that the country is on track for recovery in areas that are currently unattractive. According to Peru’s monetary authority, Peru’s GDP will grow by 5.5% in 2015 . This will represent a significant recovery from GDP growth in 2014. Peru currently has a trade deficit of 647 USD million . Low commodity prices in 2014 attributed to Peru’s decrease in export earnings. Inflation has averaged at 3% . Poverty rates have fallen by more than half between 2005 and 2013, and the amount of people living in extreme poverty has fallen from 15.8% to 4.7% . GDP Growth 2012-2015 (click to enlarge) GDP growth has declined significantly since 2014. The sharp decline in GDP growth is attributed to the decline of the fishing and mining industries . A decline in metal prices and poor weather conditions attributed to the poor performance of these industries. Because of this, growth in 2014 was significantly lower than its average growth rate of 6.4%. Recovery of these industries is crucial for Peru to continue on its path as a key player in Latin America. Latin America GDP Growth GDP Growth in Peru has consistently outperformed Latin America, and has only been rivaled by Colombia. Even with slower growth in 2014-2015, Peru demonstrates tremendous potential compared to other countries in Latin America. The relatively poor performance of 2014 presents opportunity for investors who believe that Peru can rebound, and has the potential for higher growth in the future. iShares MSCI All Peru Capped ETF The easiest way to gain access to Peru is through the iShares MSCI All Peru Capped ETF, which provides exposure to a variety of industries in Peru that have the potential for growth. The holdings for this ETF are in the following industries: Basic Materials (Mining): 47.75% Financial Services: 30.1% Utilities: 7.2% The remaining companies are in the following industries: consumer defensive, consumer cyclical, industrials, and energy. It is very evident that the poor performance of the fund is correlated to the recent negative performance of the mining industry, as top holdings in the mining industry have not performed well in the past year. Southern Copper Corp (NYSE: SCCO ) has lost 0.68% in the past year, and Buenaventura Mining Company Inc (NYSE: BVN ) lost 4.93% in the past year. Future recovery of this industry would provide substantial returns for investors. Moreover, the financial services industry is a large component of this ETF, and its future potential for growth is also strong. Recovery in GDP growth seems to be ahead, as the ministry of finance has projected 4.2% economic growth for 2015 . Moreover, the Andean Development Corporation expects Peru to lead Latin America in growth this year, which will result from increased mining and infrastructure projects. Recovery and growth of the mining and banking industries in Peru are both two of the most important factors for a turnaround in this fund’s performance. Mining Industry Overview Peru is one of the most mineralized countries in the world, and currently hosts some of the largest metal mines in the world. Peru is the world’s third largest producer of copper, silver, tin, and zinc, and is also the world’s seventh largest producer of gold. The majority of the world’s largest mining companies have a presence in Peru; this includes Xstrata, Newmont Mining Corporation (NYSE: NEM ), Glencore ( OTCPK:GLNCY ), Gold Fields (NYSE: GFI ), Freeport-McMoRan (NYSE: FCX ), Rio Tinto (NYSE: RIO ), Anglo American ( OTCPK:AAUKY ), and Barrick Gold Corporation (NYSE: ABX ). Copper mining presents the most potential in Peru, as Peru is expected to double its copper output from 1.3 million MT to 2.8 million MT by 2016 . Moreover, out of all the mining investments expected to take place by 2020, $35 billion will be allocated towards copper projects; this represents 62% of the total investment . Five copper mines are expected to begin production before 2016, with a total investment of $13 billion. It is shocking to note that although Peru has large mineral resources, only approximately 0.32% of the country’s total territory was being explored in 2013. Risks in this industry that investors should be aware of and constantly investigate include the government’s response to illegal mining operations and negative local perception of mining operations . Illegal operations identified by the police are not only shut down, but the equipment is also destroyed. Mining operations have also resulted in protests from local citizens, who oppose the operations and seek to protect their farming and water resources. A large number of conflicts have resulted in local citizens being injured or killed. Lack of local cooperation has resulted in the delay of operations of some companies. Most recently, Southern Copper Corp plans to extend its initial 60 day pause so that it can build local support. The full potential of Peru’s mining industry is clearly not being realized, and there is growth ahead. Investors can profit long term by the turnaround in Peru’s economic performance and the development of the mining industry. Infrastructure/Construction The completion of infrastructure projects is another factor that is anticipated to attribute to Peru’s future economic recovery and growth. Credit Suisse projected economic growth of 5.6% in 2016 , which would be attributed to the vast infrastructure projects undertaken. Some of these projects include: Southern Gas Pipeline : This project consists of more than 1,700 kilometers of gas pipeline, designed to transport gas from the Camisea Field to Southern Peru. The Peru government, with the support of a consortium, agreed to invest $5.7 billion to build the capital’s first subway line . Recovery of the construction industry in 2015 may be one pillar of the economy in Peru that attributes to the country’s recovery. The government plans to embark on 22 large-scale projects in 2015 with a total value of $7 billion; some of these projects will be in the construction industry. Although it currently only accounts for 5% of the country’s GDP , its growth is significant, as it has consistently outperformed the country’s annual GDP growth. The construction industry is also expected to rebound for the following reasons : The Work for Taxes Law, which seeks to accelerate the growth of construction projects, by allowing private companies to implement projects chosen by regional and local governments. Peru’s president, Ollanta Humala, plans to pave 85% of the country’s roads by 2016. In 2015, the government expressed its plans to invest $2.8 billion in new hospital infrastructure, and to invest further into schools. Banking The banking industry has the advantage of high potential for expansion, due to the large unbanked population in Peru. This is also combined with the threat of overconcentration of banks in the industry, which attributed to the 1998 financial crisis the country experienced. Performance of the industry in 2014 makes it evident that the economic adversity in 2014 did not negatively impact the banking industry: Total direct loans expanded by 14.8% Total deposits increased by 18.4% Equity increased by 11.2% The industry is still in its infant stages , as only 20% of the population in Peru holds an account at a financial institution. The high growth potential of this industry has consequently encouraged the entrance of major foreign banks. Moreover, a 15-20% growth in the microfinance industry has been projected for 2015; microfinance will not only be beneficial for increasing the socioeconomic status of citizens of Peru, but will also increase their access to banking services. The growth of the microfinance industry will provide a major benefit to the banking industry as a whole, by increasing the banked population. The recovery and future growth of this industry is highly feasible, and the fund’s top holding in this industry is attractive based on its past financial performance. Credicorp Ltd. (NYSE: BAP ), the fund’s top holding in the banking industry, has had a negative return of 9.53% in the past year. However, the company was able to increase its net revenue by 46.1% in 2014 . Conclusion It is reasonable to assume that a rebound of Peru’s economy is highly feasible in the future, and that Peru is one of the most promising countries in Latin America. Recovery and growth for the country is inevitable, specifically in the industries that this fund invests into. Therefore, investing in the iShares MSCI All Peru Capped ETF is a wise endeavor for those having a long term vision for Peru’s economic growth and recovery. Editor’s Note: This article covers one or more stocks trading at less than $1 per share and/or with less than a $100 million market cap. Please be aware of the risks associated with these stocks. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.

RCS’ Drop In Share Price Represents A Good Opportunity

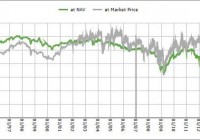
RCS is now trading at NAV, giving investors value. Rates are still low and will continue to stay low, even after initial increases. Bond funds focused on short-term maturities should outperform longer-term bonds. The purpose of this article is to evaluate the PIMCO Strategic Income Fund (NYSE: RCS ) as an investment option. To do so, I will look at recent fund performance, current holdings and allocation, and trends in the market to attempt to determine how well it will do going forward. First, a little about RCS. RCS is a closed-end fund that seeks to generate a level of income that is higher than that generated by high-quality, intermediate-term U.S. debt securities. That is the fund’s stated objective, with capital appreciation as a secondary objective. The fund is currently trading at $8.58/share and pays a monthly dividend of $.08/share, which translates to an annual yield of 11.19%. Recently, RCS, along with most Pimco funds, has been in a serious downtrend. Year-to-date, RCS is down over 9%, and over the past year the fund is down almost 19%, both figures exclude dividend payments. Once dividends are taken in to consideration, RCS’ performance is not quite as poor, but it is still not providing the steady returns bond investors would expect. In comparison, the iShares Barclays Aggregate Bond Fund (NYSEARCA: AGG ) is down about 1.5% year-to-date, and has essentially broken even over the past year, while providing an annualized yield of 2.32%. While RCS has not performed well recently, I will outline a few reasons why RCS will overcome its current headwinds and should improve its performance throughout the rest of the year. First, the drop in RCS has brought the fund down to a reasonable valuation level. The fund now trades at just a slight premium of .23%, which is essentially even with its Net Asset Value (NAV). Many Pimco funds trade at premiums to their NAV, so RCS represents a better value over some of these competing funds. This represents an attractive entry point for RCS, since the fund typically trades at a premium to its NAV, as indicated by the historical chart below: (click to enlarge) As you can see from the chart, RCS has traded at a premium fairly consistently since 2005, well before the financial crisis, so it is not an anomaly that derived out of the recession. To me, this indicates that the selling of RCS has reached its limit, and further downward pressure will be unlikely given its historical trading patterns and high yield to act as a buffer. New investors can use the steep drop in share price to pick up the fund at an attractive valuation. A second reason why I like RCS has to do with its make-up, with the fund sporting an effective maturity average of 3 years , with the vast majority of the bonds maturing in 5 years or less. This compares to other popular funds such as PGP and PHK, which hold average maturity levels of 6 years and 4 years , respectively. This is important because interest rates are set to rise in the near future, so funds with shorter maturity time periods should outperform those with longer maturity periods. This is because the risk increases the further out in the future the maturity date is in a rising rate environment. A rising rate environment is all but a certainty over the next 3-6 months, based on recent Federal Reserve statements and coverage . Therefore, investors want to limit their exposure to longer-term maturities, and focus on bond funds that have shorter durations, such as RCS. A final reason why I like RCS has to do with its high, and reliable, distribution rate. RCS currently sports a yield over 11%, which provides a high income stream for investors in a low rate environment, and will help buffer the fund against further losses. While I just mentioned that interest rates are set to rise, the increases are sure to be modest at first. In fact, Janet Yellen indicated, after the most recent Fed meeting, that interest rates will rise slower than previously anticipated . The current consensus now is that rates will not exceed 2% by the end of 2016, meaning that the U.S. will continue to experience a historically low rate environment for at least another year and a half. This means that investors will continue to be on the hunt for yield, and a mass exodus from bond funds will probably not occur anytime soon because of this. With a yield over 11%, RCS will provide income driven investors a place to continue to earn a high yield while interest rates stay low. Of course, investing in RCS is not without risk. Pimco funds have been in steady downtrends lately, and the selling could continue as investors fret over rising interest rates and over the legacy of Bill Gross’ depature from the company , which continues to plague his former funds. Additionally, interest rates could end up rising sooner, and more aggressively, than anticipated. If this occurs, investors will be able to earn higher returns on safe investments, like US Treasuries, and the appetite for leveraged bond funds will decline somewhat. However, I do not see these scenarios continuing to hurt RCS. For one, investors have been recently reassured that the interest rate increases will be gradual. Also, as stated earlier, RCS’ share price has reached its NAV, providing a nice backdrop against further selling. While many Pimco funds trade at discounts to NAV and that could certainly happen to RCS, the fund has traded at a premium consistently for the past ten years, so the risk is somewhat muted. And, given RCS’ reliable distribution, a further drop in share price will provide investors with a higher yield, helping to make up for the loss in principal. Bottom line: Pimco funds have performed poorly in 2015, and RCS is no exception. These funds have come under pressure due to Bill Gross’ departure, the threat of rising interest rates, and a share price correction towards NAV for many funds that have been trading at large premiums. However, RCS has now reached a level that provides investors with a reasonable valuation and a high yield. With interest rates set to remain low through the end of next year, investors will continue to look for options that provide more income than a 1% savings account or 3% dividend fund. With a reliable monthly distribution, and the risk of further price depreciation muted, I would encourage investors to consider this fund. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.