Tag Archives: investing ideas

Value And Momentum Are Highly Correlated

One of the most popular research papers on momentum is ” Value and Momentum Everywhere ” by Asness, Moskowitz, and Pedersen. In June 2013, this was published in the prestigious Journal of Finance . I have an earlier blog post which discussed that paper. However, one important item slipped by me then. It was a statement by the authors that value and momentum strategies are negatively correlated. They cited a negative monthly correlation coefficient between value and momentum of -0.24. Asness and his crew have brought up this negative correlation in subsequent writings regarding the merits of momentum and value investing.[1] Other writers and speakers have also been expounding this idea of negative correlation between value and momentum strategies. Long/Short Versus Long Only However, some of us, including myself, did not carefully consider the fact that the Asness et al. study dealt only with long/short momentum and value. This is where you are long high book-to-value and high momentum stocks, while simultaneously short low book-to-value and low momentum stocks. As we will see, the correlations between long/short value and momentum are substantially different than the correlations between long-only value and momentum. The vast majority of the investing world uses long-only rather than long/short portfolios. This applies to both value and momentum strategies. In looking at dozens of mutual and exchange traded funds, I am not aware of any value/growth oriented funds (other than those from AQR using muti-assets or multi-factors) that use a balanced long/short approach. With momentum, I know of only a single public fund [the QuantShares U.S. Market Neutral Momentum ETF (NYSEARCA: MOM ) ] that uses a long/short approach, and it is tiny with only $1.23 million in assets. Therefore, correlations between value and momentum using long/short portfolios are largely irrelevant and may be misleading to most investors. We will show the correlations between U.S. value and momentum stocks using long-only portfolios from the Kenneth French Data Library . We will use the value weighted top one- third of book-to-market value stocks and the top one-third of momentum stocks measured over their prior 2-12 month’s performance during the past 87 years. We will use stocks above the median NYSE in market capitalization. These are the ones that are most commonly traded. By using only large and mid-cap stocks, we avoid the problems associated with micro-cap liquidity. Besides looking at separate value and momentum portfolios, we will also examine a portfolio allocated 50/50 to value and momentum with monthly rebalancing. Our benchmark will be all stocks above the median NYSE market capitalization. No transaction costs or other expenses are deducted. Correlations Here are the monthly correlations from February 1927 to June 2015: MOM VALUE 50/50 MKT MOM 1.00 0.81 0.94 0.90 VALUE 1.00 0.96 0.92 50/50 1.00 0.96 MKT 1.00 The correlations of value and momentum to the market index are 0.92 and 0.90, respectively. As expected, these correlations are very high. What may not be expected is that the correlation between long-only value and long-only momentum is also very high at 0.81. This is dramatically different from the Asness et al. -0.24 monthly correlation between idiosyncratic long/short momentum and value. This difference has important implications for what long-only investors might expect if they invest in both value and momentum. Performance Statistics The return of any blended portfolio is a weighted average of the component returns regardless of the correlations. However, the risk exposure of a blended portfolio can differ greatly based on the correlations between the components. If those components have low or negative correlation, then there should be a substantial reduction in portfolio volatility. However, if the component correlations are strongly positive, as they are here with long-only value and momentum, then there may be little reduction in risk by combining them. We see this is the case looking at results from February 1927 to June 2015: MOM VALUE 50/50 MKT ANN RTN 15.70 15.23 15.46 11.73 STD DEV 19.21 24.75 20.95 20.44 SHARPE 0.59 0.44 0.53 0.38 MAX DD -77.4 -89.0 -83.9 -88.0 Results are hypothetical, are NOT an indicator of future results, and do NOT represent returns that any investor actually attained. Please see our Disclaimer page for more information. The momentum portfolio has the highest return and the highest Sharpe ratio. However, a momentum portfolio of individual stocks also has very high turnover and associated high transaction costs that are not accounted for in the data. See Novy-Marx and Velikov (2014) for an up-to-date analysis of these costs and a review of earlier cost studies. High transaction costs is one reason why I prefer to use momentum with indices and sectors. These work very well with momentum while having substantially lower transaction costs. Value shows almost the same return as momentum and also a higher Sharpe ratio than the large/mid-cap market benchmark.We should understand that if value and momentum had a low or negative correlation, then the standard deviation of a 50/50 mix of value with momentum would likely show a lower volatility than either value or momentum individually. That is not the case here. The standard deviation of the blended portfolio is higher than the standard deviation of the momentum portfolio. It is, in fact, almost identical to the volatility of the market portfolio. Drawdown The same is true with respect to maximum drawdown. The market and value portfolios show around the same maximum drawdown of -88 to -89%. This is based on month-end values. Intra-month drawdowns would be higher. I cannot imagine any investor who would be comfortable losing more than 90% of the value of their portfolio. The maximum drawdown of the momentum portfolio is a little better at -77.4%, but the maximum drawdown of the value/momentum blended portfolio is back up to -83.9%. So should there be value and momentum everywhere? We didn’t think so before, and we don’t think so now, at least not for long-only investors. Momentum without value shows the highest return, highest Sharpe ratio, lowest volatility, and lowest maximum drawdown. But its -77.4% maximum drawdown is still uncomfortably high, and high transaction costs may substantially reduce momentum returns from individual stocks. Summary The way to reduce large downside exposure as well as boost expected returns in the long-run is by using dual momentum as explained in my book and throughout this blog. The absolute momentum component of dual momentum boosts the Sharpe ratios of all the above portfolios and cuts their maximum drawdowns almost in half. Perhaps what we can say is, “Dual Momentum Everywhere!” [1] See reports by the AQR posse, ” Fact, Fiction, and Momentum Investing ” and ” Investing with Style “.
How To Find The Best Style Mutual Funds: Q2’15 In Review

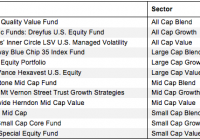
Summary Finding the best mutual funds is an increasingly difficult task in a world with so many to choose from. Performance of a mutual fund’s holdings equals the performance of the fund. Our coverage of mutual funds leverages the diligence we do on each stock by rating mutual funds based on the aggregated ratings of their holdings. Finding the best mutual funds is an increasingly difficult task in a world with so many to choose from. How can you pick with so many choices available? Don’t Trust Mutual Fund Labels There are at least 904 different Large Cap Value mutual funds and at least 6391 mutual funds across twelve styles. Do investors need 500+ choices on average per style category? How different can the mutual funds be? Those 904 Large Cap Value mutual funds are very different. With anywhere from 17 to 1003 holdings, many of these Large Cap Value mutual funds have drastically different portfolios, creating drastically different investment implications. The same is true for the mutual funds in any other style, as each offers a very different mix of good and bad stocks. Large Cap Value ranks first for stock selection. Small Cap Blend ranks last. Details on the Best & Worst mutual funds in each style are here . A Recipe for Paralysis By Analysis We firmly believe mutual funds for a given style should not all be that different. We think the large number of Large Cap Value (or any other) style mutual funds hurts investors more than it helps because too many options can be paralyzing. It is simply not possible for the majority of investors to properly assess the quality of so many mutual funds. Analyzing mutual funds, done with the proper diligence, is far more difficult than analyzing stocks because it means analyzing all the stocks within each mutual fund. As stated above, that can be as many as 1003 stocks, and sometimes even more, for one mutual fund. Any investor worth his salt recognizes that analyzing the holdings of a mutual fund is critical to finding the best mutual fund. Figure 1 shows our top rated mutual fund for each style. Figure 1: The Best Mutual Fund in Each Style Sources: New Constructs, LLC and company filings How To Avoid “The Danger Within” Why do you need to know the holdings of mutual funds before you buy? You need to be sure you do not buy a fund that might blow up. Buying a fund without analyzing its holdings is like buying a stock without analyzing its business and finances. No matter how cheap, if it holds bad stocks, the mutual fund’s performance will be bad. PERFORMANCE OF FUND’S HOLDINGS = PERFORMANCE OF FUND If Only Investors Could Find Funds Rated by Their Holdings The Eaton Vance Hexavest U.S. Equity Fund (MUTF: EHUIX ) is the top-rated Large Cap Value mutual fund and the overall best fund of the 6391 style mutual funds that we cover. The worst mutual fund in Figure 1 is the Royce Special Equity Fund (MUTF: RSEIX ), which gets our Neutral rating. One would think mutual fund providers could do better for this style. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article.

Adrenaline Investing And Public Power Corporation Of Greece

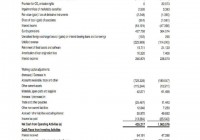
Greek stock market = adrenaline. There are some interesting value plays in this market. Nevertheless, Public Power Corporation does not look like one of them. Some investors have already decided it is time to bet on Greek stocks, some still hesitate, and for some it is unacceptable to even think about it. In one of my previous articles I have presented some thoughts on Greek telecommunication operator OTE. Today, I would like to continue by looking at Public Power Corporation of Greece ( OTC:PUPOF ), a Greek company engaged in the electricity generation, transmission and distribution; it owns lignite mines, conventional thermal and hydroelectric power plants. PPC trades with P/E (TTM) at 15.65. Czech power company CEZ trades with PE at 15.28, Spanish Iberdrola with PE at 17.59, Austrian Verbund at 38.8, Italian Enel at 86.0, German EON is in red and RWE has PE at 11.9. Comparing PPC with median valuation therefore indicates it does not trade with significant discount. Nevertheless, I would not draw strong conclusions from this type of comparison. I believe, it is more helpful to look at the cash flow of the Company: (click to enlarge) Operating cash flow decreased significantly in 2014. While the company earned EUR 1 billion in 2013, it generated only EUR 435 million in 2014. The reason is not a sharp decline in profitability, though. Operating cash flow declined mostly due to sharp increase in receivables, which mostly reflects deteriorating situation in the whole economy. PPC cut CapEx in 2014 but its cash flow after CapEx was still deeply in red. Needless to say, should this become a standard performance in the coming years, it is hard to find any value in the stock. What if the performance returned to a standard set in 2013? The company generated EUR 138 million after CapEx (and interest expenses). This is the cash flow that is available to principal payment and/or to shareholders. Let`s consider an optimistic scenario: This cash flow represents free cash flow to equity and the situation in the Greek economy soon returns back to stability. We can therefore apply risk free rate of 0,8 % (current yield of the German Bunds) and risk premium of only 5,5 % (see this for some discussion on market risk premiums). Based on the data from FT, PPC has quite high beta (1,55). In this scenario, the required rate of return (based on standard CAPM model) would reach 9,32 %. Now, let`s assume the free cash flow to equity will be constant – it will not grow in the future. The present value of this cash flow would then reach EUR 858 million. If the cash flow grew by 2 % annually, its present value would be EUR 1.09 billion. How do the presented estimates compare to the current market cap? Interesting enough, current market cap is at EUR 1.09 billion. My reading of this situation is that the market is extremely optimistic. Current market cap is hard to justify without assuming significant improvement in cash flow generation and a decline of the risk premium. There was some y-o-y improvement in the cash flow in Q1 2015 (and it was mostly due to working capital). But it is hard to extrapolate these results to the whole year. And a significant decrease of the market risk premium is currently only a finance fiction. OTE may be the last significantly undervalued stock in the world as far as its company-specific situation is concerned. I believe the same can hardly be said about PPC. Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.