Tag Archives: function

Considering SCHF For Foreign Exposure? Modern Portfolio Theory Can Use It
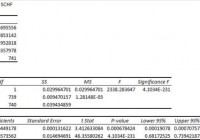
Summary I’m taking a look at SCHF as a candidate for inclusion in my ETF portfolio. The risk level is relatively high for just holding SCHF, but the correlation to the S&P 500 fixes that. The ETF has a solid dividend yield and diversified holdings. I’m not assessing any tax impacts. Investors should check their own situation for tax exposure. Investors should be seeking to improve their risk adjusted returns. I’m a big fan of using ETFs to achieve the risk adjusted returns relative to the portfolios that a normal investor can generate for themselves after trading costs. I’m working on building a new portfolio and I’m going to be analyzing several of the ETFs that I am considering for my personal portfolio. One of the funds that I’m considering is the Schwab International Equity ETF (NYSEARCA: SCHF ). I’ll be performing a substantial portion of my analysis along the lines of modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. What does SCHF do? SCHF attempts to track the total return of FTSE developed ex-US Index. The ETF falls under the category of “Foreign Large Blend.” Funds within this category generally invest most of their assets in developed markets. Some will include a small exposure to emerging markets, but different investment managers have different definitions of which markets are “emerging” and which ones are “developed.” Does SCHF provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. Therefore, I start my diversification analysis by seeing how it works with SPY. I start with an ANOVA table: (click to enlarge) The correlation is about 76%, which is low enough that I’m expecting to see significant diversification benefits. Standard deviation of daily returns (dividend adjusted, measured since January 2012) The standard deviation isn’t going to make a strong case for investing in SCHF. For the period I’ve chosen, the standard deviation of daily returns was 0.8955%. For SPY, it was 0.7300% over the same period. Clearly, SPY appears to be the safer of the two investments. Mixing it with SPY I also run comparisons on the standard deviation of daily returns for the portfolio assuming that the portfolio is combined with the S&P 500. For research, I assume daily rebalancing because it dramatically simplifies the math. With a 50/50 weighting in a portfolio holding only SPY and SCHF, the standard deviation of daily returns across the entire portfolio is 0.7865%. The risk level on the portfolio drops relative to only holding SPY because of the diversification benefits that come from the 76% correlation. If the position in SPY is raised to 80% while SCHF is used at 20%, the standard deviation of daily returns drops down to 0.7453%. In practice, I think the best way to use SCHF will be a position smaller than 20% and used in a more diversified portfolio. The low correlation makes a very strong case for using SCHF in a small position to enhance diversification. Currently, I’m thinking my exposure to developed markets should be around 5%. At 5%, the standard deviation of the portfolio would be 0.7329%. This is hardly higher than simply holding SPY and indicates that most of the additional risk from the higher standard deviation has been effectively diversified away. Why I use standard deviation of daily returns I don’t believe historical returns have predictive power for future returns, but I do believe historical values for standard deviations of returns relative to other ETFs have some predictive power on future risks and correlations. Yield and Taxes The distribution yield is 2.26%. The SEC 30-day yield is 2.49%. Those yields aren’t bad and make this ETF look attractive as part of a dividend portfolio. However, the ETF invests in foreign securities and I’m not a CPA or CFP. Investors concerned about tax consequences should seek advice from someone knowledgeable about their tax situation. Expense Ratio The ETF is posting .08% for an expense ratio, which is very low. Market to NAV The ETF is trading at a .45% premium to NAV currently. In my opinion, a .45% premium to NAV is a problem for new investors. I think the ETF is significantly less attractive when it trades above NAV. A .10% premium isn’t too bad in my opinion, but .45% bothers me. It’s not terrible, but I’d be cautious about that. Largest Holdings The diversification within the ETF is excellent, as shown by the following chart: (click to enlarge) I don’t love having my portfolio invested in U.S. Dollars (my checking account gives me that exposure), but I can understand the ETF needing to have some cash. With no company over 1.5%, that diversification is great. I have not performed individual research on the holdings, but with no exposure over 1.5%, I don’t think there is a viable case for returns on time in researching the individual holdings. Investing in the ETF is largely relying on modern portfolio theory. The argument for the investment is the respectably low correlation of the portfolio to the major U.S. index funds. Making an investment requires a belief that markets are at least somewhat efficient so that the companies within the portfolio will be reasonably priced. Conclusion I’m currently screening a large volume of ETFs for my own portfolio. I’ll do a little more digging on SCHF later and post what I find. The portfolio I’m building is through Schwab, so I’m able to trade SCHF with no commissions. I have a strong preference for researching ETFs that are free to trade in my account. I think SCHF will merit a fairly small position within that ETF portfolio. The low correlation and the low expense ratio are the driving factors for me. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis. The analyst holds a diversified portfolio including mutual funds or index funds which may include a small long exposure to the stock.
One Of The Best ETFs I’ve Found So Far: SCHD

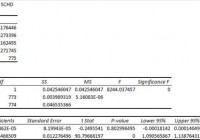
Summary I’m taking a look at SCHD as a candidate for inclusion in my ETF portfolio. The risk level, measured in standard deviation of daily returns is great. The ETF looks even better if combined with other major funds such as SPY. Investors should be seeking to improve their risk adjusted returns. I’m a big fan of using ETFs to achieve the risk adjusted returns relative to the portfolios that a normal investor can generate for themselves after trading costs. I’m working on building a new portfolio and I’m going to be analyzing several of the ETFs that I am considering for my personal portfolio. One of the funds that I’m considering is the Schwab U.S. Dividend Equity ETF (NYSEARCA: SCHD ). I’ll be performing a substantial portion of my analysis along the lines of modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. What does SCHD do? SCHD invests in large dividend companies. It has shined in my first look at the fund. I was originally planning a 10 to 15% position for a dividend ETF, but now I’m contemplating raising that position up as high as 20 to 25%. At this point, the portfolio is still in the planning and funding stage. Does SCHD provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. Therefore, I start my diversification analysis by seeing how it works with SPY. I start with an ANOVA table: (click to enlarge) At first look it may seem like the correlation of 91.42% would mitigate the diversification benefits of using SCHD with a major fund like SPY, but 91% still offers some meaningful benefits as long as the ETF can stand on its own strengths. In my opinion, SCHD passes that test and is a very viable candidate. Standard deviation of daily returns (dividend adjusted, measured since late 2011) This is the strongest area for the ETF. The returns are remarkably stable relative to most equity investments. Generally speaking, standard deviation of daily returns is the realm of SPY. Most ETFs look fairly poor when compared to just holding the S&P 500. The only reason those other equity ETFs can be useful under modern portfolio theory is diversification benefits when used as a fairly small percent of the portfolio. For the period I selected for comparison, the standard deviation on daily returns for SPY is 0.7754%. For SCHD the standard deviation of daily returns is 0.6651%. Mixing it with SPY I also run comparison on the standard deviation of daily returns for the portfolio assuming that the portfolio is combined with the S&P 500. For research, I assume daily rebalancing because it dramatically simplifies the math. With a 50/50 weighting in a portfolio holding only SPY and SCHD, the standard deviation of daily returns across the entire portfolio is 0.7124%. That is a very attractive risk position for a portfolio that only contains two ETFs. Why I use standard deviation of daily returns I don’t believe historical returns have predictive power for future returns, but I do believe historical values for standard deviations of returns relative to other ETFs have some predictive power on future risks and correlations. Yield The distribution yield is 2.52%. The SEC 30 day yield is 2.84%. For a dividend investor that wanted to minimize trading costs, that is a fairly strong yield on an ETF with less systematic risk than SPY. Expense Ratio The ETF is posting .07% for an expense ratio, which is very low. Market to NAV The ETF is trading at a .05% premium to NAV currently, but that is fairly close. A twentieth of one percent is not exposing an investor to a large risk in that regard. This value can change suddenly, so investors should check before submitting a trade. Largest Holdings The biggest holdings are around 4 to 5% of the portfolio. I prepared the following chart to break it down: (click to enlarge) I’m fairly happy with the construction of the top of the portfolio. At present, I’m not very optimistic on Verizon (NYSE: VZ ) or AT&T (NYSE: T ) because I think the industry risk is still being priced into the companies after Sprint (NYSE: S ) became much more aggressive. However, in the longer term (5 to 20 years) I think it makes sense to include them in the fund. Conclusion I’m currently screening a large volume of ETFs for my own portfolio. I’ll do a little more digging on SCHD later and post what I find. The portfolio I’m building is through Schwab, so I’m able to trade SCHD with no commissions. I have a strong preference for researching ETFs that are free to trade in my account. I’m expecting that SCHD will end up with a significant position in my portfolio.

Gary Gordon Positions For 2015: Tactical Asset Allocations For ETF Investors

This is the third piece in Seeking Alpha’s Positioning for 2015 series. This year we have once again asked experts on a range of different asset classes and investing strategies to offer their vision for the coming year and beyond. As always, the focus is on an overall approach to portfolio construction. Gary A. Gordon, MS, CFP® is the president of Pacific Park Financial, Inc. , a Registered Investment Adviser with the SEC. He has more than 24 years of experience as a personal coach in “money matters,” including risk assessment, small business development and portfolio management. Gary is often asked to consult as an educator. He has taught financial concepts in Mexico, Singapore, Hong Kong, Taiwan and the United States. As a Certified Financial Planner™ (CFP®), Gary has distinguished himself as a reputable and trusted investor advocate. He writes commentary for ETF Expert, Seeking Alpha and TheStreet. Gary’s participation on local and national radio has spanned more than a decade, and he currently hosts the ETF Expert Show. Seeking Alpha’s Carolyn Pairitz recently spoke with Gary to find out how he goes about selecting specific ETFs and plans to use them to position clients in 2015. Carolyn Pairitz (CP): How would your clients describe your investing style/philosophy? Gary Gordon (GG): My clients would recite my mantra… There are four possible investing outcomes (i.e., big gain, small gain, small loss, big loss) and three of them are good. Successful investing is about controlling the investing outcome so that you ensure a big gain, small gain or small loss, and take action to avoid the big loss. The humongous loss is the only thing that can destroy a lifetime of wealth-building. By way of example, I may own rental property in California where I live, perhaps for its capital appreciation potential as well as its annual cash flow. And along the way, I may experience price gains and dips, good renters and bad. But the one thing that my financial well-being would not be able to tolerate is an earthquake that decimates the property. It follows that, I may not enjoy paying the earthquake insurance premium each year, but I understand the criticality of doing so. The exact same insurance principles go for investing in market-based securities. Stop-limit loss orders, technical trendlines, put options, non-correlated assets, hedges – no technique or asset type will eliminate downside risk completely nor appear particularly worthwhile in extremely bullish uptrends. Yet the tactical asset allocation decision-making to insure against the only thing that can kill a portfolio – the big loss – keeps my clients on track to achieve their financial freedom goals. CP: Which global issue is most likely to adversely affect U.S. markets in 2015? GG: Ironically enough, I have the same answer for 2015 that I provided in 2014’s interview: Deflation. Europe and Japan are both still struggling to beat deflationary pressures back; their 2014 efforts to stimulate their respective economies with asset purchases and negligible/non-existent or even negative overnight lending rates have pummeled their currencies more than anything else. Indeed, the U.S. stock bull got knocked for a loop in October because of deflationary recession scares around the globe. So what did the U.S. Fed do? One of its committee members publically questioned whether or not the institution should even end QE3. Only then did U.S. large cap stocks rapidly recover from what might have been far worse than an intra-day 9.8% correction. For better or worse, our market continues to rely on central bank manipulation. The Fed will be exceedingly “patient” in 2015, and may even decide by late 2015 to talk about ways to be accommodative yet again. They may have no choice. Consider the fact that, while Russia’s direct impact on the U.S. economy is small, the country matters a whole lot to Europe’s well-being. And Europe is reeling even without Russian woes. In essence, if world markets determine that the European Central Bank (ECB) is not aggressive enough with its stimulus, a region-wide recession would certainly drag on U.S. equities. CP: Have any ETFs that have launched this year caught your eye? GG: I like the work that Meb Faber does in the value space. The Cambria Global Value ETF (NYSEARCA: GVAL ) is remarkably intriguing in theory, though I do not buy assets based solely on low P/Es or low P/S ratios. Russia started the year as the least expensive global equity market, and it only got cheaper. And then there’s the fact that I lived in Asia on and off for roughly 4 ½ years, so the Deutsche X-trackers Harvest CSI 300 China A-Shares ETF (NYSEARCA: ASHR ), which technically launched in 2013, has also been intriguing. Gaining access to stocks listed in China, the world’s second largest economy, is something that everyone should be thinking about. CP: What do you hope to see from the ETF industry in 2015? Any product filings you are particularly excited to see launch? GG: I anticipate interest in an exchange-traded vehicle that tracks the index that I created with FTSE-Russell, the FTSE Custom Multi-Asset Stock Hedge Index. Obviously, I hope to see it launch because it would be beneficial to me personally, but I am equally hopeful for those who want an alternative to shorting, leverage, inverse funds or T-bills. Let’s be real for a moment. The U.S. economy cannot continue to accelerate if the world continues to decelerate. Investors cannot ignore the mountain of stock overvaluation evidence indefinitely, no matter how many rabbits the world’s central banks pick out of their collective hats. And periods of amplified exuberance always find themselves, later or sooner, at a place of heart-pounding panic. An exchange-traded vehicle for the FTSE Custom Multi-Asset Stock Hedge Index should reduce the anxiety associated with stock downturns. CP: Could you please describe this stock hedge index in more detail? What was your process for developing it? GG: My colleague and I started from a place where we investigated the currencies, commodities, foreign debt and U.S. debt (basically, all non-equity investments), that have a history of exceptionally low correlations to stocks. And then, in combination, demonstrate as close to the holy grail of zero correlation as possible. We looked at performance as well as fund flow movement in times of moderate to severe stock stress. Historically speaking, currencies like the dollar, the franc and the yen – all for very different reasons – have served as admirable hedges. Gold, more or less, had been the commodity of choice. Meanwhile, Japanese government bonds, German bunds and a fairly wide range of longer-maturity U.S. bonds worked remarkably well too. To be clear, owning a fund that tracks this index, or choosing multiple assets to emulate it, is not meant for benchmarking a “bear fund.” Bear funds look to profit from short positions or the stock market falling. The FTSE Custom Multi-Asset Stock Hedge Index is designed to hedge against stock ownership and the risks associated with it. Similarly, owning a single asset like T-bill cash or a U.S. Treasury bond ETF alone does not offer the benefit of diversification across multiple asset avenues. Only now, is multi-asset stock hedging even available in an index. And while it is most likely to perform well when stocks are not… this isn’t a prerequisite. For example, the FTSE Custom Multi-Asset Stock Hedge Index (through 12/15/14) was up 6.5%, even in a year when large-cap U.S. stocks have performed well. CP: Going into 2015, which asset classes are you overweight? Which are you underweight? GG: Remember, we use tactical asset allocation and we are not static buy-n-holders. We are currently overweight U.S. mega-caps through funds like the iShares 100 ETF (NYSEARCA: OEF ) and the Vanguard Mega Cap Growth ETF (NYSEARCA: MGK ), as well as U.S. minimum volatility through iShares USA Minimum Volatility ETF (NYSEARCA: USMV ). And yes, I believe “low vol” is an asset class, though “low vol” by sector, not by the market at large. Otherwise, you own a whole of utilities and non-cyclicals, rather than a fairly well-distributed mix across the economic segments. I have also been picking through the energy rubbish bin. On the debt side of the equation, much like 2014, we currently own bond assets that have relative value when compared to foreign debt. There is plenty of value in owning the Vanguard Long Term Bond ETF (NYSEARCA: BLV ) and/or the Vanguard Extended Duration Treasury ETF (NYSEARCA: EDV ). People may think that is nuts, but those are the same folks who completely missed the 2014 boat. So let me toot my own horn on this one, I was one of the very few who said rates would go down, the yield curve would flatten, and that these funds would be big time winners. We also own muni debt via the SPDR Barclays Municipal Bond ETF (NYSEARCA: TFI ) as well as closed-end funds like the Blackrock MuniAssets Fund (NYSE: MUA ). I have been underweight small caps, foreign, emerging since July of 2014. And while I own held-to-maturity high yield bond investments in the Guggenheim Series, in general, widening credit spreads have made me steer clear of high yield bonds. CP: What advice would you give to a ‘do-it-yourself’ investor in the present investing environment? GG: Be mindful of where things stand. We are talking about the fourth longest bull market since 1897. The other three? They did not make it past eight years. Either we will break records with this bull market, or more likely, we will see a bear market in 2015 or 2016. The problem is not participating in stocks during periods of amplified exuberance and overlooked overvaluation – that’s how money was made in the ’90s and in the mid-2000s. So you should definitely participate. The problem is failing to take action to minimize downside risks – that’s how investors got creamed in 2000-2002 and 2008-2009. Whether someone does it for you or whether you do it yourself, you must have a plan to avoid the bulk of an upcoming disaster. Disclosure: Gary Gordon, MS, CFP is the president of Pacific Park Financial, Inc., a Registered Investment Adviser with the SEC. Gary Gordon, Pacific Park Financial, Inc, and/or its clients may hold positions in the ETFs, mutual funds, and/or any investment asset mentioned above. The commentary does not constitute individualized investment advice. The opinions offered herein are not personalized recommendations to buy, sell or hold securities. At times, issuers of exchange-traded products compensate Pacific Park Financial, Inc. or its subsidiaries for advertising at the ETF Expert web site. ETF Expert content is created independently of any advertising relationships.