Tag Archives: author

ACIM Appears To Have Incredibly Low Risk, But That’s Inaccurate
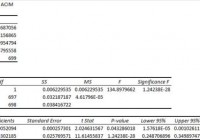
Summary I’m taking a look at ACIM as a candidate for inclusion in my ETF portfolio. The correlation appears to be very low, but the low liquidity caused days with no trades. The same liquidity issues might have improved the standard deviation of returns. The premium to NAV makes it look like a potential short candidate. I’m not assessing any tax impacts. Investors should check their own situation for tax exposure. Investors should be seeking to improve their risk adjusted returns. I’m a big fan of using ETFs to achieve the risk adjusted returns relative to the portfolios that a normal investor can generate for themselves after trading costs. I’m working on building a new portfolio and I’m going to be analyzing several of the ETFs that I am considering for my personal portfolio. One of the funds that I’m considering is the SPDR® MSCI ACWI IMI ETF (NYSEARCA: ACIM ). I’ll be performing a substantial portion of my analysis along the lines of modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. What does ACIM do? ACIM attempts to track the total return of the MSCI ACWI IMI Index. At least 80% of funds are invested in companies that are part of the index, or in ADRs (American Depositary Receipts). ACIM falls under the category of “World Stock”. Does ACIM provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. Therefore, I start my diversification analysis by seeing how it works with SPY. I start with an ANOVA table: (click to enlarge) The correlation is an absurdly low 40%. If an investor stopped here, they would be dramatically misinformed about the risks of ACIM. The correlation is very low as a statistical measure, but the metric is being substantially enhanced by a lack of liquidity in the stock which caused several days to report no change in the price of securities. Standard deviation of daily returns (dividend adjusted, measured since March 2012) The standard deviation is excellent for the international exposure. For ACIM it is .9981%. For SPY, it is 0.7419% for the same period. SPY usually beats other ETFs in this regard, so having a lower standard deviation is excellent. Frequent readers should be aware that I have measured returns from March 2012 instead of my normal starting point of January 2012. I can’t measure values until the ETF is trading and Yahoo is tracking the dividend adjusted close values. Unfortunately, the standard deviation may appear substantially smaller than it should because several days (especially in 2012) reported no change in price. When no sales are reported, the price is not changed and it looks like a low standard deviation of returns. Investors should be aware that there is substantial liquidity risk. The average volume for the last 10 days is only 6,837. Mixing it with SPY I also run comparisons on the standard deviation of daily returns for the portfolio assuming that the portfolio is combined with the S&P 500. For research, I assume daily rebalancing because it dramatically simplifies the math. With a 50/50 weighting in a portfolio holding only SPY and ACIM, the standard deviation of daily returns across the entire portfolio is 0.7320%. If an investor wanted to use ACIM as a supplement to their portfolio, the standard deviation across the portfolio with 95% in SPY and 5% in ACIM would have been .7263%. However, due to the very low correlation, a position of 80% SPY combined with 20% ACIM results in a standard deviation for the portfolio of only .6982%. Investors hoping to capitalize on this low standard deviation of returns would need to have a relatively low need for liquidity since the price stability only works if no large sell orders are being introduced. Why I use standard deviation of daily returns I don’t believe historical returns have predictive power for future returns, but I do believe historical values for standard deviations of returns relative to other ETFs have some predictive power on future risks and correlations. Yield & Taxes The distribution yield is 1.84%. The yield is almost high enough for a retiring investor, in my opinion. Generally, I want to see yields over 2% when considering an ETF for retirement planning. This is close enough that I could still consider it from the perspective of a retiree, but only if the retiree was certain they did not have liquidity needs. I’m not a CPA or CFP, so I’m not assessing any tax impacts. Expense Ratio The ETF is posting .25% for an expense ratio. I want diversification, I want stability, and I don’t want to pay for them. The expense ratio on this fund is higher than I want to pay, but isn’t unbearable for the incredible diversification. Market to NAV The ETF is at a 1.85% premium to NAV currently. Premiums or discounts to NAV can change very quickly so investors should check prior to putting in an order. I wouldn’t want to pay a premium greater than .1% when investing in an ETF. There might be some situations where I would pay .2%, but you won’t see me agreeing to pay that premium. Not happening. If I took a position in this ETF it would be with a carefully monitored limit buy order that adjusted for the premium. If sell orders dropped it to my price, great, if not, I’d rather avoid the ETF entirely than pay that premium. Largest Holdings ACIM has great diversification when you look at the percent in each asset, but the top of the portfolio still has a huge tilt towards the U.S. economy. (click to enlarge) These aren’t bad stocks to hold, but I can get them by holding any of several major ETFs that hold major U.S. companies. The appeal of a world portfolio is having substantial exposure to other markets to help balance out the geographic risks of a U.S. based portfolio. This collection of top holdings supports my belief that the correlation is understated because favorable impacts from days where reported closing price did not change. If ACIM drops to trade at a discount to NAV, I may become very interested in it. Otherwise, regardless of the statistics, I’m not interested in paying a premium for an ETF that holds several of the same companies I can acquire without the premium. Conclusion I’m currently screening a large volume of ETFs for my own portfolio. The portfolio I’m building is through Schwab, so I’m able to trade ACIM with no commissions. I have a strong preference for researching ETFs that are free to trade in my account, so most of my research will be on ETFs that fall under the “ETF OneSource” program. I think the statistics for the ETF are misleading and premium to NAV looks like a poor bet for future returns. When this ETF trades near NAV, it may have some value to investors. I may take a deeper look at it in the future, but for now I think the low liquidity and premium NAV present a real challenge to including it in my portfolio. Due to low liquidity and the potential need to execute a trade over multiple days to create or sell a reasonable position, I would not consider this ETF at all from any account that was required to pay trading commissions on the ETF. If I can short ETFs that are overpriced (without commission), it might become appealing to initiate shorts on the ETF when it is trading over book value if I can own substantially the same securities through other ETFs without paying a premium to acquire them. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis. The analyst holds a diversified portfolio including mutual funds or index funds which may include a small long exposure to the stock.
UNG Is Down For December — Will Cold Weather Pull It Back Up?

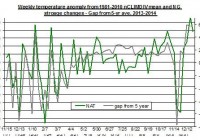
Summary The extraction from storage is projected to be lower than normal again this week. The temperatures are projected to come down in the next two weeks, but this isn’t expected to bring back up UNG. Contango is likely to keep UNG below natural gas prices. The price of The United States Natural Gas ETF (NYSEARCA: UNG ) took another fall in the past week to its lowest level in recent months. The ETF did bounce back earlier this week, but is still down for the month by nearly 24%. The ongoing low oil prices may have contributed to weakness of UNG, but the main issue will remain in changes in weather expectations . The level of underground storage is also likely to play a role in the progress of UNG. This was the case last week. This week’s extraction is likely to also be lower than normal for the season. As I pointed out in the past , the changes in the weather are likely to play a significant role in the changes in U.S. storage levels. Last week’s lower-than-expected withdrawal may have contributed to the drop in UNG on the day of the publication. I say this with caution because the linear correlation between the changes in UNG and storage tends to be low. Nonetheless, there are occasions when the market seems to react to this news, as seems to be the case last week. Looking forward, the storage is expected to show another lower than normal extraction due to last week’s higher than normal average temperature, as presented in the chart below. Source of data: EIA and national climate data center The chart shows the progress of the deviation in the national weather from normal and the weekly changes in natural gas storage with respect to the 5 year average (The data only refer to 2012/2013 and 2014 winter time). Moreover, the linear correlation between the two data sets is a strong and positive linear correlation of 0.62. Last week, the deviation from normal temperatures was, on average, 4.9. So all things being equal, we are likely to see another lower than normal extraction. Keep in mind that even if natural gas prices were to recover, the ongoing Contango in the future markets is likely to result in UNG underperforming natural gas for the near term. Cold weather ahead For the next two weeks, however, temperatures are projected to fall below average temperature throughout the Northeast and Midwest. Nonetheless, on a national level, the heating degrees for this week are expected to be slightly below normal and last year’s levels. This could suggest the demand for heating purposes in the residential/commercial sectors, while may rise in the coming days, won’t necessarily increase more than normal for this time of the year. The recent withdrawal from storage was 49 Bcf, which was well below the 5-year average and last year’s extraction of 138 Bcf and 177 Bcf, respectively. The table below summarizes the changes in storage in the past few weeks and the comparison to last year and the 5-year average levels. Source of data EIA Following the recent extraction the underground natural gas storage is at 3,246 Bcf. This is nearly 5% higher than last year’s storage level and only 5% below the 5-year average. Over the next couple of weeks we are likely to see another lower than normal extraction from storage, which could fuel another fall in the price of UNG or at the very least keep it from recovering. But if temperatures start coming down to below normal levels, UNG may change course and start to rally.

My New Years Resolution: Balance My Risky Portfolio

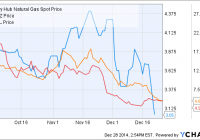
Summary As a young investor my portfolio is filled with risk. In 2015 I will be looking to limit my exposure to big risks. My portfolio was weighted heavily in oil and gas, which did not make for a pretty 2014. Thomas Jefferson once said “With great risk comes great reward.” This certainly is not always the case and my portfolio did most definitely did not agree with this statement in 2014. Since I’m quite young I can afford to have a large amount of risky plays in my portfolio which led to an interesting and ultimately dismal 2014. In 2015 I plan to, as best I can, de-risk my holdings, while still incorporating the right amount of risk for my age. A Few Current Positions For starters, in addition to covering the oil and gas sector heavily, my portfolio has been weighted toward the industry more than any other. You can imagine what this weight has done since the summer. One of my holdings in the industry is small cap Bakken producer Emerald Oil (NYSEMKT: EOX ). The company has operationally and financially improved dramatically since I first added shares but still remains an extremely risky play, especially with the current oil environment. I have averaged down on the name as the company has greatly scaled back its operations in this environment which should enable it to survive the downturn. On a different note, one of my other oil and gas names is a far less risky play. Gran Tierra Energy (NYSEMKT: GTE ) is a Canadian company with operations mainly in Colombia and Peru. The reason I say this is a significantly less risky play is the fact that at the end of Q3 the company continued to have no debt and $360M in cash. Its revised 2015 capex plan only calls for $310M. So while oil is at these depressed levels, Gran Tierra might just be in one of the best positions to ride it out. Along with that the company has several other catalysts. The company should announce soon, or with Q4/FY results, how the initial drilling in Peru is coming along. This will result in significant additions to the company’s reserves and ultimately will add a lot to its overall value. My only main concern with Gran Tierra while I have held it has been the ongoing conflict in Colombia. The FARC rebel group targets lots of infrastructure, including pipelines and rail lines which have in the past disrupted operations. This concern however has been quelled for the time being as the FARC announced a unilateral ceasefire that started December 20th. In 2015 I plan to maintain my current position in energy as I do not need to add more weight to my portfolio and to exit underwater positions would not make sense. Another risky portion of my portfolio includes a sizeable position in J.C. Penney (NYSE: JCP ). I’ve been playing the turnaround for some time now, and in the time I have held it the company has improved its quarterly results greatly. While I do believe in the turnaround working to some extent, depending on Q4 results, I may opt to close this position. Safer plays have become far more attractive than the troubled retailer, and I believe I’m ready to add more practical holdings. A position that I will most definitely be holding onto is Sirius XM (NASDAQ: SIRI ). I have held this position longer than any other, and it was in fact one of the first things I bought when I first began investing a few years ago. The company continues to perform well and I for one am a fan of the buybacks the company has been doing. Earlier in the year I was pleased that the deal with Liberty fell through because I see far greater upside without a buyout for a company with little comparable competition. One last higher risk name I also own is Synta Pharmaceuticals (NASDAQ: SNTA ). It is a small biotech that is engaged in many trials of various drugs, in particular its leading candidate, Ganetespib, which fights cancer. While obviously this further adds diversification to my holdings, Synta is only in trial stages of its drugs, and expects itself to have cash just through Q4 of 2015. This is worrisome because if the results from the trials in 2015 are poor it could see the shares free fall. Don’t get me wrong, I still believe in all of my current holdings. I’m just worried about how balanced I am between safer more reliable plays and high risk plays. In 2014 the market was quite good and that can be seen from the various indexes being up nicely. I’m sure you’ve heard the famous Warren Buffett quote a million times before but here it is once more: “Be fearful when others are greedy and greedy when others are fearful.” Now I can’t tell you where the market will go in 2015 and I’m not saying be fearful or greedy. I’m just highlighting the uncertainty and what my plans are for 2015. Positions I’m Considering When looking at my holdings going into 2015 I see one major problem that I want to fix: no companies I own pay dividends. I did for some time own Bank of America (NYSE: BAC ), but sold it part way through the year (a position in hindsight I wished I kept). My new strategy in 2015 will most definitely include a few and maybe many strong dividend payers. The first of which I am considering would be AT&T (NYSE: T ). With a 5.5% yield it is very enticing. The company continues to deliver some dividend growth announcing yet another increase a couple of weeks ago. I see the acquisition of DIRECTV (NASDAQ: DTV ), which is still pending, as a strong catalyst for further growth going forward. Another mega cap I’m considering is Pfizer (NYSE: PFE ). The company sports a 3.5% yield and also just announced that it was increasing its dividend yet again. In late October the company announced that it would buyback another $11 billion worth of its shares. A couple of other dividend paying names that I am considering adding include Flowers Foods (NYSE: FLO ), Ford (NYSE: F ), and Middlesex Water (NASDAQ: MSEX ). Some Risky Additions in 2015? Although I want to balance my holdings to safer plays that does not mean I won’t add some further risk to it. Over the past two weeks natural gas has been hammered and I see a possible very enticing risk vs. reward opportunity playing natural gas at these levels. This could turn out especially rewarding if we see bitter weather in late January or February. Henry Hub Natural Gas Spot Price data by YCharts Another position I may consider would be one in Twitter (NYSE: TWTR ). In 2015 the company is expected to become consistently profitable after many quarters of losses. The shares are trading 46% down from its 52 week high and the last time the shares were trading around this level they went on a 50% run. A short term catalyst for the shares may be the rumors that current CEO Dick Costolo may be canned. Costolo has lost investor confidence and replacing him could lead to a nice pop in the shares. Conclusion Being so young I can afford to have lots of risk and make mistakes (and learn from them). In 2015 I want to be more cautious and reasonable. Since beginning investing my holdings have always overwhelmingly been dominated by high risk names. To start 2015 I have saved enough to change this and will not only be adding more reliable and safe names, but will also be getting rid of some of the current risky names I hold. In particular I am going to add extremely financially sound companies that also pay dividends which should reward even if 2015 turns sour for the markets. Editor’s Note: This article covers one or more stocks trading at less than $1 per share and/or with less than a $100 million market cap. Please be aware of the risks associated with these stocks. Additional disclosure: Always do your own research before investing. Keep in mind that everyone, especially by age group, has different investment goals and aims. Most of my investments remain long term but I also dabble in short term trading occasionally. I may initiate long positions in T, PFE, UGAZ, GASL, F, FLO, MSEX, TWTR.