Tag Archives: author

SCHX: It’s Like SPY With Lower Expense Ratios
Summary I’m taking a look at SCHX as a candidate for inclusion in my ETF portfolio. SCHX looks incredible in my initial review. The ETF has slightly better diversification than SPY, but similar overall risk. I expect SCHX to be a core part of my new portfolio. I’m not assessing any tax impacts. Investors should check their own situation for tax exposure. Investors should be seeking to improve their risk-adjusted returns. I’m a big fan of using ETFs to achieve the risk adjusted returns relative to the portfolios that a normal investor can generate for themselves after trading costs. I’m working on building a new portfolio and I’m going to be analyzing several of the ETFs that I am considering for my personal portfolio. One of the funds that I’m considering is the Schwab U.S. Large-Cap ETF (NYSEARCA: SCHX ). I’ll be performing a substantial portion of my analysis along the lines of modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. What does SCHX do? SCHX attempts to track the total return of the Dow Jones U.S. Large-Cap Total Stock Market Index. At least 90% of funds are invested in companies that are part of the index. SCHX falls under the category of “Large Blend”. Does SCHX provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. Therefore, I start my diversification analysis by seeing how it works with SPY. I start with an ANOVA table: (click to enlarge) The correlation is over 99%. In short, no benefits should be expected from combining the ETF with SPY. That’s fine; the holdings are largely the same as SPY. SCHX is a replacement ETF for SPY, not a complementary holding. Standard deviation of daily returns (dividend adjusted, measured since January 2012) The standard deviation is higher. For SCHX it is .7303%. For SPY, it is 0.7300% over the same period. SPY usually beats other ETFs in this regard, and the difference between the two is largely meaningless. Because the two funds have extremely high correlation and almost identical risk profiles, the most important part of the comparison will probably be the expense ratios. Allocation I believe a fund like SPY or SCHX should be a core holding in most portfolios. Therefore, I think a reasonable level of exposure ranges from 10% to 35%. The largest exposure I would want to consider would be around 50%. In my opinion, by the time exposure levels get that high, there are other investments that can be mixed in to lower the total risk of the portfolio without hurting the expected returns. Why I use standard deviation of daily returns I don’t believe historical returns have predictive power for future returns, but I do believe historical values for standard deviations of returns relative to other ETFs have some predictive power on future risks and correlations. Under standard deviation of daily returns, the S&P 500 is remarkably efficient in long-term growth relative to volatility. Yield & Taxes The distribution yield is 1.70%. The SEC yield is 1.78%. Based on the yields, I think the ETF is solid as a part of a portfolio for retirees. If I were retiring, I would want to lower my position in SPY or SCHX in favor of putting more of the portfolio into slightly higher yielding value companies. However, I still think an exposure around 10% would be both reasonable and prudent in many scenarios. It’s difficult to build a portfolio near the efficient frontier, in my opinion, without including an ETF that tracks large U.S. companies. Because I have a long ways to go to reach retirement, I want an exposure in the 15 to 30% range. I’m not a CPA or CFP, so I’m not assessing any tax impacts. Expense Ratio The ETF is posting .04% for an expense ratio. I want diversification, I want stability, and I don’t want to pay for them. The .04% expense ratio makes me happy as an investor. SPY appears to have around .09% for an expense ratio. The ratio for SPY is actually closer to .094%, but it is regularly rounded down when screening. Market to NAV The ETF is at a .06% premium to NAV currently. It is trading pretty close to NAV, but in the interest of risk-adjusted returns I really like to know that I’m buying it right on or just below NAV. Premiums or discounts to NAV can change very quickly so investors should check prior to putting in an order. Largest Holdings The portfolio has solid diversification. SPY is holding a very similar portfolio but with a slightly larger allocation to the top companies, such as 3.55% in Apple (NASDAQ: AAPL ). However, the additional diversification for SCHX can be partially set off by some of the companies near the top being less volatile or by the ETF having less trading volume. (click to enlarge) Conclusion I’m currently screening a large volume of ETFs for my own portfolio. The portfolio I’m building is through Schwab, so I’m able to trade SCHX with no commissions. I have a strong preference for researching ETFs that are free to trade in my account, so most of my research will be on ETFs that fall under the “ETF OneSource” program. SCHX is a very strong contender to be a core holding in the new portfolio. I wanted a replacement for SPY that I would be able to trade without commissions. Of course, I also wanted to see a lower expense ratio, and SCHX delivered that. When I transfer money into this new portfolio (probably in February), I expect that SCHX will be allocated 15 to 30% of my portfolio value. I am not compensated by Schwab in any way for writing about ETFs that fall under their program. I select several ETFs under their program because I am doing research for my own investing and want to avoid trading fees. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis. The analyst holds a diversified portfolio including mutual funds or index funds which may include a small long exposure to the stock.
SPDR S&P MidCap 400 ETF: MDY’s 2014 And Fourth-Quarter Performance And Seasonality

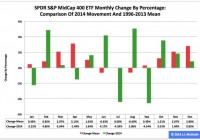
Summary The SPDR S&P MidCap 400 ETF ranked No. 2 in 2014 among the three most popular exchange traded funds based on the S&P 1500’s constituent indexes. Most recently, the ETF’s adjusted closing daily share price last month expanded to $263.97 from $261.79, an increase of $2.18, or 0.83 percent. Seasonality analysis shows the fund’s price accelerates in the fourth quarter of an average year, but decelerated in Q4 of last year. The SPDR S&P MidCap 400 Trust ETF (NYSEARCA: MDY ) ranked second by return during 2014 among the three most popular ETFs based on the S&P 1500’s constituent indexes, as it behaved worse than the SPDR S&P 500 Trust ETF (NYSEARCA: SPY ) and better than the iShares Core S&P Small-Cap ETF (NYSEARCA: IJR ). Measured by adjusted closing daily share prices, MDY climbed to $263.97 from $241.29, a hike of $22.68, or 9.40 percent. Accordingly, the middle-capitalization ETF underperformed the large-cap SPY by -4.06 percentage points and overperformed the small-cap IJR by 3.55 percentage points. Both seasonality and U.S Federal Reserve policy appear likely to be headwinds for MDY over the coming quarter. The Fed announced the end of asset purchases under its third formal quantitative easing program on October 29, 2014, and may announce the beginning of its next round of federal funds rate increases on April 29, 2015. The Fed’s conclusion of purchases under its first two formal QE programs this century is associated with bear markets in MDY , with the ETF slipping -21.16 percent in 2010 and -28.13 percent in 2011. Figure 1: MDY Monthly Change, 2014 Vs. 1996-2013 Mean (click to enlarge) Source: This J.J.’s Risky Business chart is based on analyses of adjusted closing monthly share prices at Yahoo Finance . MDY behaved a little worse in 2014 than it did during its initial 18 full years of existence, based on the monthly means calculated by employing data associated with that historical time frame (Figure 1). The same data set shows the average year’s weakest quarter was the third, with a relatively small negative return, and its strongest quarter was the fourth, with an absolutely large positive return. The ETF ran true to form overall in Q4 last year, but its share price decelerated rather than accelerated into 2015. Figure 2: MDY Monthly Change, 2014 Vs. 1996-2013 Median (click to enlarge) Source: This J.J.’s Risky Business chart is based on analyses of adjusted closing monthly share prices at Yahoo Finance. MDY performed much worse in 2014 than it did over its initial 18 full years of existence, based on the monthly medians calculated by using data associated with that historical time frame (Figure 2). The same data set shows the average year’s weakest quarter was the third, with a relatively small negative return, and its strongest quarter was the fourth, with an absolutely large positive return. Meanwhile, the latest figure generated by my proprietary U.S. Economic Index methodology and other multivariate analyses continue to indicate the metric may have hit either a long- or a short-term high level in August. As a result, I suspect American economic performance could soon join seasonality and Fed policy as a headwind for the equity market in general and for MDY in particular. Disclaimer: The opinions expressed herein by the author do not constitute an investment recommendation, and they are unsuitable for employment in the making of investment decisions. The opinions expressed herein address only certain aspects of potential investment in any securities and cannot substitute for comprehensive investment analysis. The opinions expressed herein are based on an incomplete set of information, illustrative in nature, and limited in scope. In addition, the opinions expressed herein reflect the author’s best judgment as of the date of publication, and they are subject to change without notice.

Investing Is Not Gambling, Part 2

Summary Recap on Part 1: top short idea (AYA CN) has paid off. Part 2 introduces more ways to play the responsible investing theme. See below for blended strategy and a more conservative fixed-income strategy in a world of record-setting equity markets. Recap on Part 1 Socially responsible investing is becoming a mainstream phenomenon. Just this week, CNBC caught wind of it and featured the slumping of sin stocks, As a recap of Investing is Not Gambling, Part 1 , AYA CN was featured as the most overvalued gambling stock in the note. Since Part 1 was published, AYA stock has underperformed the SPTSX index: AYA slumped 20+% while the index finished the year essentially flat. Source: Bloomberg In this article, Part 2, I will introduce more ways to play the social responsibility theme. More ways to play this strategy I. Equity-Fixed Income Blended Strategy A Bloomberg screen returns over 130 mutual funds that either exclude or restrict gambling related investments. Strategies of these funds range from equities to bonds, and from balanced to international. To be clear, the exclusion/restriction is not a simple black-and-white rule. If you read the prospectuses (which you should), sophisticated fund managers conduct in-depth analysis . If the overall social impact and financial returns outweigh the profit contribution from gambling products, the security may be retained in the portfolio. For example, if an innovative machine manufacturer derives 5% of its profit from slot machines and the rest from carbon control devices, its securities may well be included. If you are leery about excessive exposure to equities (at near-record level one has sufficient reasons to think so), you should look for blended strategy among the 130 or so funds. When selecting funds, investors should pay attention to their different benchmarks. The highest returning fund may not be the best investment just because it has the most aggressive strategy (i.e. higher allocation to equities). With that in mind, I have laid out funds with blended strategy and grouped them by benchmarks. They are then ranked by equity exposure. As shown in the chart below, PWMAX , PWMCX , and PWMIX all are compared against a benchmark with only 24% equity exposure and, not surprisingly, have the lowest returns. The equity weight then goes up to 42% for PMPAX, PWPCX, and PWPIX; it rises to 55% for PGPAX and PMMIIX; and it finally reaches 60% for CBAIX, CSGCX, and WSBFX. Next, comparing fund returns against their respective benchmark, one will get a real picture of each fund’s alpha. It turns out, PWMIX has the highest alpha and the third lowest management fees. For investors with a higher risk appetite, PGPAX and PMIIX offer a good compromise between aggressiveness and alpha. Chart: fund returns Source: Bloomberg II. Fixed Income Focus Strategy Again, if you are bearish on the equity market in 2015, excluding funds with equity exposure, you can still choose from 50-odd funds. Following a similar selection process as above, investors will see that Praxis Genesis Conservative Strategy Fund (MUTF: MCONX ) offers outstanding risk-adjusted returns with a management fee of only 0.05%. Last but not the least, for the purists out there, MCONX strictly excludes any security related to the gambling industry. One thing I did not explore so far is project-based investments, such as the Social Impact Bonds pilot program in the UK. Institutional investors such as high-net worth individuals and foundations are invited to either guarantee first loss or lend capital into the program. Such projects are usually off limit to retail investors. However, I am all ears if you know of projects accessible to all.