Tag Archives: author

PPL Corp. To Reward Investors In 2015
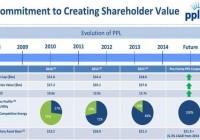
Summary A low treasury yield environment and efforts to reduce competitive energy operations will support PPL’s performance. Efforts to reduce competitive energy operations will positively affect bottom-line numbers and cash flows. PPL is likely to give full-year 2015 earnings guidance during its Q4 2014 earnings call. Utility stocks’ high dividend yields make them attractive investment options for dividend-seeking investors. The utility sector, including PPL Corp. (NYSE: PPL ), performed better than the S&P 500 in 2014. The outperformance of the utility sector was mainly due to the low treasury yield environment. In 2015, I believe PPL will deliver a healthy financial performance due to the ongoing low treasury yield environment and efforts made by the company to lower its competitive energy operations, which will bode well for its EPS. The company has been aggressively working to sell and reduce competitive energy operations, as the competitive energy operations remain challenging. Also, the company offers a healthy dividend yield of 4.3%, supported by its cash flows, which makes it a good investment option for dividend-seeking investors. All Set for 2015 In 2014, the utility sector performed better than the S&P 500. The better performance can be mainly attributed to the low treasury yield environment. In 2015, the utility sector will continue to deliver a healthy performance due to the low yield environment and efforts undertaken by utility companies, including PPL, to reduce their competitive energy operations. The following table shows the performance of the S&P 500, the utility sector ETF (NYSEARCA: XLU ) and PPL. S&P 500 XLU PPL 2014 Performance 12% 25% 22% Source: Bloomberg.com. Due to the weak commodity prices and capacity revenues, competitive energy operations of U.S. utility companies have remained challenging in recent years. In the current environment, utility companies are choosing to reduce their competitive energy operations and making efforts to grow regulated operations. PPL has also been expanding its regulated operations and reducing competitive energy operations, which will positively affect its EPS. The company opted to spin off its competitive energy business operations. The spin-off is expected to be completed in the first half of 2015. The spin-off will allow PPL to focus and expand its regulated business operations. The company is anticipating cost savings of $75 million from the transaction. Also, PPL has finalized a deal to sell its Montana hydro assets to NorthWestern Energy for $0.9 billion . PPL is expected to use cash from the sale to invest in the expansion of its regulated operations. Separately, PPL is taking measures to expand its regulated transmission operations. The company has announced its plans to build a transmission line, and is expected to make capital expenditures of approximately $5 billion over the life of the project. The company has planned to start building the line in 2016-17, and it should be in service by 2023-25. The capital expenditure PPL is planning to make will positively affect its top- and bottom-line growth in the long term. The company will have 100% exposure to regulated business operations in the coming years, which will positively affect its financial performance. The chart below shows that the company has been making consistent and aggressive efforts to reduce its competitive energy operations, and PPL’s regulatory rate base is expected to grow by 6.3% on average from 2014-18. (click to enlarge) Source: Company reports. As the company is expanding its regulated business and is in the planning phase, it will give its 2015 EPS guidance range in the Q4 2015 earnings call next month. Also, the company is likely to update its long-term EPS guidance, which I believe will be in a range of 4%-6%. Along with the earnings growth potential, PPL offers a safe dividend yield of 4.3% , backed by its cash flows. Its attractive dividend yield makes it a good investment for dividend-seeking investors. The company has consistently increased dividends over the years. In the coming years, dividends offered by the company will grow as an increase in its regulated operations will portend well for its bottom-line numbers and cash flows. The following chart shows the dividend per share, dividend payout ratio and dividend coverage ratio for PPL from 2012-2014. (Note * Dividend coverage ratio = operating cash flow/annual dividends, and 2014 figures below are based on estimates). Dividend Per Share ($) Dividend Payout Ratio Dividend Coverage* 2012 $1.44 60% 3.3x 2013 $1.47 60% 3.25x 2014* $1.49 64% 3.2x Source: Company reports and calculations. Conclusion PPL is set to deliver a healthy performance in 2015. The low treasury yield environment and efforts to reduce competitive energy operations will support PPL’s performance in 2015. The company’s efforts to reduce competitive energy operations will positively affect its bottom-line numbers and cash flows. Also, the company is likely to give its full-year 2015 earnings guidance during the Q4 2014 earnings call, which will improve earnings visibility and bode well for the stock price. Also, the stock offers a safe dividend yield of 4.3%. Due to the aforementioned factors, I am bullish on PPL.
Recap: The Best And The Worst In Alternative Investment ETFs

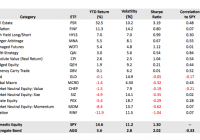
John Bogle, founder of the Vanguard fund family, has cautioned investors for many years about playing cute with their investment portfolios. “Don’t look for a needle in the haystack,” says Saint Jack, “just buy the haystack.” With that, Bogle inveighs against stock-picking and advocates the use of index funds. Why try to beat the market, in his view, since you can’t do it consistently? Not surprisingly, many investment advisors rail against Bogle’s notion. Some, particularly those running endowments and foundations, are duty bound to seek equity-like returns without the concentrated risk of stock investments. Which brings us to alternative investments. Mixing “alts” into a portfolio can, in the best of circumstances, enhance returns and diversify risk. This year, though, alts have had an especially tough row to hoe. Domestic equities, measured by the performance of S&P 500 SPDR ETF (NYSEARCA: SPY ) , gained 15 percent in 2014 with an annualized volatility of 11 percent. As stand-alone investments, only one alt category outperformed the domestic stock market. (click to enlarge) Alts, of course, aren’t meant to be stand-alones; they’re destined, for most investors, to be portfolio adjuncts. Real estate was the standout of the year, offering a one-two combination punch of outsized gain and low volatility. The PowerShares Active US Real Estate ETF (NYSEARCA: PSR ) more than doubled SPY’s return with a smaller standard deviation. All this with a middling correlation to the broad equity market. If you were shopping for negative correlation to equities this year, the shelves were rather bare. Only two ETFs – the SPDR Gold Shares Trust (NYSEARCA: GLD ) and the QuantShares US Market Neutral Value ETF (NYSEARCA: CHEP ) – cranked out negative coefficients against SPY. And the price for this? Negative returns, though arguably you could say GLD had a breakeven year. If you base your diversification success on the Sharpe ratio – a gauge of risk-adjusted returns – this year’s runner-up alt bets were managed futures and absolute value, epitomized by the WisdomTree Managed Futures Strategy ETF (NYSEARCA: WDTI ) and the HedgeIQ Real Return ETF , respectively. The derby for 2015’s best and worst kicks off today. Stay tuned for ongoing updates.

WDIV Could Be Fun If Prices Deviate From NAV With Poor Liquidity

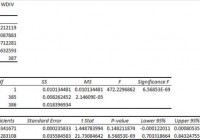
Summary I’m taking a look at WDIV as a candidate for inclusion in my ETF portfolio. Poor liquidity ruins the reliability of statistics and creates significant spreads during trading hours. The correlation to SPY looks low, but I can’t trust it because of the liquidity issues. If an investor is using a tax advantaged account that doesn’t pay commissions on trading the ETF, it could be interesting to play the spreads and deviations from NAV. I’m not assessing any tax impacts. Investors should check their own situation for tax exposure. Investors should be seeking to improve their risk adjusted returns. I’m a big fan of using ETFs to achieve risk adjusted returns relative to the portfolios that normal investors can generate for themselves after trading costs. I’m working on building a new portfolio and will be analyzing several of the ETFs that I am considering for my personal portfolio. One of the funds that I’m considering is the SPDR S&P Global Dividend ETF (NYSEARCA: WDIV ). I’ll be performing a substantial portion of my analysis along the lines of modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. What does WDIV do? WDIV attempts to track the total return (before fees and expenses) of an unnamed index that tracks the stocks of global companies with strong dividends. At least 80% of the assets are invested in those companies, or ADRs that represent those companies. WDIV falls under the category of “World Stock”. Does WDIV provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use the SPDR S&P 500 Trust ETF (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. Therefore, I start my diversification analysis by seeing how it works with SPY. I start with an ANOVA table: (click to enlarge) The correlation is excellent at 74%. I want to see low correlations on my international investments. Extremely low levels of correlation are wonderful for establishing a more stable portfolio. I consider anything under 50% to be extremely low. However, for equity securities an extremely low correlation is frequently only found when there are substantial issues with trading volumes that may distort the statistics. Standard deviation of daily returns (dividend adjusted, measured since Jun e 2013) The standard deviation is very attractive. For WDIV, it is 0.6626%. For SPY, it is 0.6904% for the same period. SPY usually beats other ETFs in this regard, so a lower volatility level is very impressive. Because the ETF has fairly low correlation for equity investments and a low standard deviation of returns, it should do fairly well under modern portfolio theory. Liquidity looks fine Average trading volume is an issue. The average volume is running between 6,500 and 7,000 shares per day. Very low average trading volumes can result in statistics that are substantially less reliable. I will continue with my process for analyzing the ETF, but this is a red flag investors should know about. Within the time period I was looking at, there were only a few days where the change in dividend adjusted close was equal to 0.00%. When we see that the closing price did not change, it is possible that no shares were trading hands that day. If the bid and ask were moving but no shares traded hands, then a change of 0.00% understates the actual volatility and may weaken or strengthen the correlation. Therefore, investors should take the statistics with a grain of salt because they may be slightly more favorable to WDIV than they should be. Mixing it with SPY I also ran comparisons on the standard deviation of daily returns for the portfolio, assuming that the portfolio is combined with the S&P 500. For research, I assumed daily rebalancing because it dramatically simplifies the math. With a 50/50 weighting in a portfolio holding only SPY and WDIV, the standard deviation of daily returns across the entire portfolio is 0.6314%. With 80% in SPY and 20% in WDIV, the standard deviation of the portfolio would have been 0.6567%. If an investor wanted to use WDIV as a supplement to their portfolio, the standard deviation across the portfolio with 95% in SPY and 5% in WDIV would have been 0.6808%. Why I use standard deviation of daily returns I don’t believe historical returns have predictive power for future returns, but I do believe historical values for standard deviations of returns relative to other ETFs have some predictive power on future risks and correlations. Yield & Taxes The distribution yield is 4.19% and the SEC yield is 3.74%. Those are very strong yield figures for an ETF. This ETF could be worth considering for retiring investors. I like to see strong yields for retiring portfolios because I don’t want to touch the principal. By investing in ETFs I’m removing some of the human emotions, such as panic. Higher yields imply lower growth rates (without reinvestment) over the long term, but that is an acceptable trade off in my opinion. I’m not a CPA or CFP, so I’m not assessing any tax impacts. Expense Ratio The ETF is posting an expense ratio of 0.40%. I want diversification, I want stability, and I don’t want to pay for them. I view expense ratios as a very important part of the long-term return picture because I want to hold the ETF for a time period measured in decades. An expense ratio of this level is enough to concern me, but world ETFs are prone to higher expense ratios. Market to NAV The ETF is at a 0.31% premium to NAV (Net Asset Value) currently. Premiums or discounts to NAV can change very quickly so investors should check prior to putting in an order. Generally, I don’t trust deviations from NAV, and I will have a strong resistance to paying a premium to NAV to enter into a position. This ETF has relatively poor liquidity, so investors should also watch out for a large bid/ask spread. At the time of my writing, the spread was 0.25%. I’m not big on crossing that spread, so I’d be one of the people that would use a limit order and wait for the seller to come to me. Due to the fairly low trading volumes and the possibility that the order would be partially filled, I’d either have to set the order to only accept complete fills or only do the trade in accounts that trade the ETF without commissions. For comparison, the spread on SPY right now is less than 0.01%. Largest Holdings The diversification is pretty good, but not incredible. For the expense ratio, I would want more. However, the fund is supposed to be investing in high dividend yielding securities, so the investment universe for the fund may be more limited. (click to enlarge) Conclusion I’m currently screening a large volume of ETFs for my own portfolio. The portfolio I’m building is through Schwab, so I’m able to trade WDIV with no commissions. I have a strong preference for researching ETFs that are free to trade in my account, so most of my research will be on ETFs that fall under the “ETF OneSource” program. The correlation and standard deviation were great, but the potential for statistics to be misleading because of poor trading volumes leaves me concerned that the numbers may not be reliable enough. When I combine risk that the data is flawed, the moderately high expense ratios, and the bid-ask spread, I’m not really blown away by this ETF. It could be an interesting ETF to put on a watch list for the trading price to deviate from NAV and then step into a short-term position through a tax advantaged account that was not paying commissions, but I don’t think I will want to use it as my primary “international exposure” ETF. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis. The analyst holds a diversified portfolio including mutual funds or index funds which may include a small long exposure to the stock.