Tag Archives: author
Junior Gold Miners Outperforming Other Asset Classes In 2015

Precious Metals and Junior Miners May Be Bottoming. Gold is breaking above critical 200 day moving average. Positive Trend Change in Gold? Oil and Copper Collapsing unable to deter gold rally. Stick to high quality gold mining assets in stable mining jurisdictions. For weeks I have been predicting that precious metals and the junior gold miners would bottom and outperform in January. Now gold (NYSEARCA: GLD ) is breathtakingly breaking above the key 200 day moving average and breaking four month highs as the World looks to gold as a safe haven. The intermediate to long term trend may be turning positive for gold and silver (NYSEARCA: SLV ) and unfortunately the amateur investor has already panicked out or may be covering their shorts. (click to enlarge) This breakout in gold could end the lower high pattern or downtrend. Sentiment is changing from negative to positive. Already for weeks , I highlighted the positive momentum in the junior gold miners (NYSEARCA: GDXJ ) despite the new low in December. This divergence usually signals an interim bottom and turning point. A few weeks ago precious metals and the shares were hitting new lows. The amateur investor panicked out. I told my subscribers to hang on and buy more at the bottom. Now the Junior Gold Miners are up over 14% since the beginning of the year outperforming the S&P500 (NYSEARCA: SPY ) and US dollar (NYSEARCA: UUP ). Despite oil and copper (NYSEARCA: JJC ) collapsing along with equities, precious metals and mining stocks (NYSEARCA: GDX ) appear to be bottoming and showing great relative strength. Right now, gold as a safe haven may be where the action is greatest. The US dollar may peak as investors realize that the US economy is still far from recovered. The oil and copper collapse is giving a loud shout to investors that the global economy is nowhere near recovery and looks more like the 2008 Financial Armageddon. One of the few things that can maintain its purchasing power in this sort of market is gold. Believe it or not another yellow metal which has held up well despite the 50% correction in oil is uranium. I told my subscribers at the end of 2014 that smart investors should be defensive against the overbought equities with inverse S&P500 ETFs such as Proshares Short S&P 500 (NYSEARCA: SH ) or a short financial fund (NYSEARCA: SEF ) and go long gold and junior gold miners in this sort of chaotic environment. The banks are sitting on major energy losses, while the S&P500 is made up largely of energy stocks and companies who profit off of emerging economies. It is way overbought and we could witness a powerful crash in equities that mirror the oil crash. I believe mining assets with real potential could come back into favor. I am accumulating hoping that within the next decade we could see a major run higher in this sector. Eventually, the trillions of debt will be paid back with devalued US dollars. Rising interest rates and inflation could pick up in 2015 especially in the US benefiting our beaten down wealth in the earth sector. Real gold mining assets in stable jurisdictions will go up in value. It is only a matter of time and patience. I like the junior gold miners especially the explorers now in Nevada and Quebec. Governments can print another trillion dollars by pressing a button at the printing press. This can’t be done in the gold exploration business. It takes years and a lot of divine blessing to find a million ounces of gold. Investors may now be able to believe this as gold breaks above the 200 day moving average. Now that you’ve read this, are you Bullish or Bearish on ? Bullish Bearish Sentiment on ( ) Thanks for sharing your thoughts. Why are you ? Submit & View Results Skip to results » Share this article with a colleague
DGRW Is A Solid ETF In Every Metric, But Still Faces An Uphill Battle
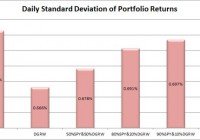
Summary I’m taking a look at DGRW as a candidate for inclusion in my ETF portfolio. The risk level on the ETF looks good with heavy trading volume. The yield is lower than I would expect for an ETF focused on dividend growth. The exposure to oil companies might be a bit much when I’m also planning a portion of my portfolio for natural resources. I’m not assessing any tax impacts. Investors should check their own situation for tax exposure. How to read this article : If you’re new to my ETF articles, just keep reading. If you have read this intro to my ETF articles before, skip down to the line of asterisks. This section introduces my methodology. By describing my method initially, investors can rapidly process each ETF analysis to gather the most relevant information in a matter of minutes. My goal is to provide investors with immediate access to the data that I feel is most useful in making an investment decision. Some of the information I provide is readily available elsewhere, and some requires running significant analysis that, to my knowledge, is not available for free anywhere else on the internet. My conclusions are also not available anywhere else. What I believe investors should know My analysis relies heavily on Modern Portfolio Theory. Therefore, I will be focused on the statistical implications of including a fund in a portfolio. Since the potential combinations within a portfolio are practically infinite, I begin by eliminating ETFs that appear to be weak relative to the other options. It would be ideal to be able to run simulations across literally billions of combinations, but it is completely impractical. To find ETFs that are worth further consideration I start with statistical analysis. Rather than put readers to sleep, I’ll present the data in charts that only take seconds to process. I include an ANOVA table for readers that want the deeper statistical analysis, but readers that are not able to read the ANOVA table will still be able to understand my entire analysis. I believe there are two methods for investing. Either you should know more than the other people performing analysis so you can make better decisions, or use extensive diversification and math to outperform most investors. Under CAPM (Capital Asset Pricing Model), it is assumed every investor would hold the same optimal portfolio and combine it with the risk free asset to reach their preferred spot on the risk and return curve. Do you know anyone that is holding the exact same portfolio you are? I don’t know of anyone else with exactly my exposure, though I do believe there are some investors that are holding nothing but SPY . In general, I believe most investors hold a portfolio that has dramatically more risk than required to reach their expected (under economics, disregarding their personal expectations) level of returns. In my opinion, every rational investor should be seeking the optimal combination of risk and reward. For any given level of expected reward, there is no economically justifiable reason to take on more risk than is required. However, risk and return can be difficult to explain. Defining “Risk” I believe the best ways to define risk come from statistics. I want to know the standard deviation of the returns on a portfolio. Those returns could be measured daily, weekly, monthly, or annually. Due to limited sample sizes because some of the ETFs are relatively new, I usually begin by using the daily standard deviation. If the ETF performs well enough to stay on my list, the next levels of analysis will become more complex. Ultimately, we probably shouldn’t be concerned about volatility in our portfolio value if the value always bounced back the following day. However, I believe that the vast majority of the time the movement today tells us nothing about the movement tomorrow. While returns don’t dictate future returns, volatility over the previous couple years is a good indicator of volatility in the future unless there is a fundamental change in the market. Defining “Returns” I see return as the increase over time in the value known as “dividend adjusted close”. This value is provided by Yahoo. I won’t focus much on historical returns because I think they are largely useless. I care about the volatility of the returns, but not the actual returns. Predicting returns for a future period by looking at the previous period is akin to placing a poker bet based on the cards you held in the previous round. Defining “Risk Adjusted Returns” Based on my definitions of risk and return, my goal is to maximize returns relative to the amount of risk I experienced. It is easiest to explain with an example: Assume the risk free rate is 2%. Assume SPY is the default portfolio. Then the risk level on SPY is equal to one “unit” of risk. If SPY returns 6%, then the return was 4% for one unit of risk. If a portfolio has 50% of the risk level on SPY and returns 4%, then the portfolios generated 2% in returns for half of one unit of risk. Those two portfolios would be equal in providing risk adjusted returns. Most investors are fueled by greed and focused very heavily on generating returns without sufficient respect for the level of risk. I don’t want to compete directly in that game, so I focus on reducing the risk. If I can eliminate a substantial portion of the risk, then my returns on a risk adjusted basis should be substantially better. Belief about yields I believe a portfolio with a stronger yield is superior to one with a weaker yield if the expected total return and risk is the same. I like strong yields on portfolios because it protects investors from human error. One of the greatest risks to an otherwise intelligent investor is being caught up in the mood of the market and selling low or buying high. When an investor has to manually manage their portfolio, they are putting themselves in the dangerous situation of responding to sensationalistic stories. I believe this is especially true for retiring investors that need money to live on. By having a strong yield on the portfolio it is possible for investors to live off the income as needed without selling any security. This makes it much easier to stick to an intelligently designed plan rather than allowing emotions to dictate poor choices. In the recent crash, investors that sold at the bottom suffered dramatic losses and missed out on substantial gains. Investors that were simply taking the yield on their portfolio were just fine. Investors with automatic rebalancing and an intelligent asset allocation plan were in place to make some attractive gains. Personal situation I have a few retirement accounts already, but I decided to open a new solo 401K so I could put more of my earnings into tax advantaged accounts. After some research, I selected Charles Schwab as my brokerage on the recommendation of another analyst. Under the Schwab plan “ETF OneSource” I am able to trade qualifying ETFs with no commissions. I want to rebalance my portfolio frequently, so I have a strong preference for ETFs that qualify for this plan. Schwab is not providing me with any compensation in any manner for my articles. I have absolutely no other relationship with the brokerage firm. Because this is a new retirement account, I will probably begin with a balance between $9,000 and $11,000. I intend to invest very heavily in ETFs. My other accounts are with different brokerages and invested in different funds. Views on expense ratios Some analysts are heavily opposed to focusing on expense ratios. I don’t think investors should make decisions simply on the expense ratio, but the economic research I have covered supports the premise that overall higher expense ratios within a given category do not result in higher returns and may correlate to lower returns. The required level of statistical proof is fairly significant to determine if the higher ratios are actually causing lower returns. I believe the underlying assets, and thus Net Asset Value, should drive the price of the ETF. However, attempting to predict the price movements of every stock within an ETF would be a very difficult and time consuming job. By the time we want to compare several ETFs, one full time analyst would be unable to adequately cover every company. On the other hand, the expense ratio is the only thing I believe investors can truly be certain of prior to buying the ETF. Taxes I am not a CPA or CFP. I will not be assessing tax impacts. Investors needing help with tax considerations should consult a qualified professional that can assist them with their individual situation. The rest of this article By disclosing my views and process at the top of the article, I will be able to rapidly present data, analysis, and my opinion without having to explain the rationale behind how I reached each decision. The rest of the report begins below: ******** (NASDAQ: DGRW ) WisdomTree U.S. Dividend Growth Fund Tracking Index: WisdomTree U.S. Dividend Growth Index Allocation of Assets: 80% Invested in components of the index or other securities that are considered to be almost identical Morningstar Category: Large Blend Time period starts: June 2013 Time period ends: December 2014 Portfolio Std. Deviation Chart: (click to enlarge) (click to enlarge) Returns over the sample period: (click to enlarge) Correlation: 96.34 Liquidity: 498,146 average shares/day Days with no change in dividend adjusted close: 10 Yield: 1.77% Expense Ratio: .28% Discount or Premium to NAV: .23% premium Holdings: (click to enlarge) Further Consideration: Yes. I am planning to allocate a portion of my portfolio to focus on dividend growth stocks because I want them to be over-weighted in my portfolio. Conclusion: DGRW doesn’t offer much in the way of diversification with a correlation that is over 96% and 10 days with no change in dividend adjusted close. There were only 2 days where SPY reported no change in dividend adjusted close during the same period. DGRW having 10 days rather than 2 may simply be a rounding error because DGRW trades around $31 to $32 and SPY is trading at over $200. A one cent movement in DGRW is similar to a six cent movement in SPY. The liquidity based on shares/day combined with the relatively low standard deviation results in an ETF that should fit nicely into portfolios that are requiring some liquidity. However, the distribution yield of 1.77% (lower than SPY’s 1.87%) is interesting for an ETF that suggests dividends are a primary focus. The expense ratio isn’t too bad and wouldn’t be enough to scare off, though I would prefer to buy closer to NAV since I expect to rebalance frequently which makes spreads and premiums or discounts more important to my strategy. With this much liquidity I would expect spreads to remain fairly small whenever the market is open and I would expect the premiums to disappear fairly fast. My biggest concern on this ETF would probably be the concentration of holdings. I don’t mind having a large position in Exxon Mobil, but I may be creating that position through an ETF that focuses on exposure to natural resources. Since I intend to include sections for a replacement for SPY and an allocation to an ETF that focuses on dividends, there will naturally be some significant exposure coming from three ETFs, but I’d like to keep the company specific risk as low as possible so that no company can compose more than 2 to 3% of my portfolio. Since the yield on the ETF is relatively low and it substantially overlaps with other positions I intend to create, I think it will face a slightly uphill battle despite being attractive ETF. As shown from the ending Portfolio Value, the high correlation also has a very similar total return. That isn’t always the case when using daily standard deviation, but it has been the case for DGRW. Comments I’m testing a new layout for my ETF articles. It is intended to optimize the articles for my followers. Let me know what you think of the new layout in the comments section. I’m always looking for feedback and trying to find ways to improve my writing for my readers.