Tag Archives: investing ideas

F.U.D. And Dividend Shock Absorbers

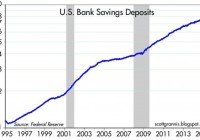
As the existential question remains open on whether Greece will remain a functioning entity within the eurozone, investor anxiety and manic behavior continues to be the norm. Rampant fear seems very counterintuitive for a stock market that has more than tripled in value from early 2009 with the S&P 500 index only sitting -3% below all-time record highs. Common sense would dictate that euphoric investor appetites have contributed to years of new record highs in the U.S. stock market, but that isn’t the case now. Rather, the enormous appreciation experienced in recent years can be better explained by the trillions of dollars directed towards buoyant share buybacks and mergers. With a bull market still briskly running into its sixth year, where can we find the evidence for all this anxiety? Well, if you don’t believe all the nail biting concerns you hear from friends, family members, and co-workers about a Grexit (Greek exit from the euro), Chinese stock market bubble, Puerto Rico collapse, and/or impending Fed rate hike, then here are a few confirming data points. For starters, let’s take a look at the record $8 trillion of cash being stuffed under the mattress at near 0% rates in savings deposits ( see chart below ). The unbelievable 15% annual growth rate in cash hoarding since the turn of the century is even scarier once you consider the massive value destruction from the eroding impact of inflation and the colossal opportunity costs lost from gains and yields in alternative investments . (click to enlarge) Next, you can witness the irrational risk averse behavior of investors piling into low ( and negative ) yielding bonds. Case in point are the 10-year yields in developing countries like Germany, Japan, and the U.S. ( see chart below ). (click to enlarge) The 25-year downward trend in rates is a very scary development for yield-hungry investors. The picture doesn’t look much prettier once you realize the compensation for holding a 30-year bond (currently +3.2%) is only +0.8% more than holding the same Treasury bond for 10 years (now +2.4%). Yes, it is true that sluggish global growth and tame inflation is keeping a lid on interest rates, but these trends highlight once again that F.U.D. (fear, uncertainty, and doubt) has more to do with the perceived flight to safety and high bond prices (low bond yields). In addition, the -$57 billion in outflows out of U.S. equity funds this year is further evidence that F.U.D. is out in full force. As I’ve noted on repeated occasions, when the tide turns on a sustained multi-year basis and investors dive head first into stocks, this will be proof that the bull market is long in the tooth and conservatism should be the default posture. There are always plenty of scary headlines that tempt investors to bail out of their investments. Today those alarming headlines span from Greece and China to Puerto Rico and the Federal Reserve. When the winds of fear, uncertainty, and doubt are fiercely swirling, it’s important to remember that any investment strategy should be constructed in a diversified manner that meshes with your time horizon and risk tolerance. Consistent with maintaining a diversified portfolio, owning reliable dividend paying stocks is an important component of investment strategy, especially during volatile periods like we are experiencing currently. Sure, I still love to own high octane, non-dividend growth stocks in my personal and client portfolios, but owning stocks with a healthy stream of dividends serve as shock absorbers in bumpy markets with periodic surprise potholes. As I’ve note before, bond issuers don’t call up investors and raise periodic coupon payments out of the kindness of their hearts, but stock issuers can and do raise dividends (see chart below). Most people don’t realize it, but over the last 100 years, dividends have accounted for approximately 40% of stocks’ total return as measured by the S&P 500. (click to enlarge) Source: BuyUpside.com Markets will continue to move up and down on the news du jour, but dividends overall remain fairly steady. In the worst financial crisis in a generation, dividends dipped temporarily, but as I explain in a previous article ( The Gift that Keeps on Giving ), dividends have been on a fairly consistent 6% growth trajectory over the last two decades. With corporate dividend payout ratios well below long term historical averages of 50%, companies still have plenty of room to maintain (and grow) dividends – even if the economy and corporate profits slow. Don’t succumb to all the F.U.D., and if you feel yourself beginning to fall into that trap, re-evaluate your portfolio to make sure your diversified portfolio has some shock absorbers in the form of dividend paying stocks. That way your portfolio can handle those unexpected financial potholes that repeatedly pop up. DISCLOSURE: Sidoxia Capital Management (SCM) and some of its clients hold positions in certain exchange traded funds (ETFs) and SPY, but at the time of publishing, SCM had no direct position in any other security referenced in this article. No information accessed through the Investing Caffeine (IC) website constitutes investment, financial, legal, tax or other advice nor is to be relied on in making an investment or other decision. Please read disclosure language on IC Contact page .

Evaluating Opportunity In The Eurozone When Greece Is (Yet Again) The Word

Summary With the eurozone accounting for 17% of the world’s GDP, I believe globally minded investors clearly need to contemplate a strategic allocation to this region. I believe a volatility-managed solution may be a sensible approach for investors to gain exposure to this critical region. In addition, I believe the divergent monetary policy between the ECB and the Fed emphasizes the need for investors to consider a currency hedge to mitigate foreign exchange risk. A currency-hedged low volatility approach could help investors pursue the region’s upside potential while managing risk By John G. Feyerer, Vice President, Director of Equity ETF Product Strategy, Invesco PowerShares Capital Management LLC The never-ending Greek tragedy continues to take twists and turns as the news surrounding Greece’s fate in the European Economic and Monetary Union (EMU) seems to change minute to minute. This saga has and will likely continue to result in greater volatility in equity markets, yet could also provide potential buying opportunities for European stocks as the dust settles. As pundits opine on the likelihood of various outcomes from the current crisis, I believe investors should step back and evaluate the longer-term opportunity to invest in the eurozone. Eurozone economic indicators point to continued expansion… With the eurozone accounting for 17% of the world’s GDP 1 , I believe globally minded investors clearly need to contemplate a strategic allocation to this region. Trends in the major economic indicators point to continued expansion, which should bode well for equity performance in Europe. Business activity in the 19-member bloc expanded at its fastest pace in four years in June, as measured by the Markit Composite Purchasing Managers’ Index (PMI), which tracks manufacturing and service sector equities The indicator rose to 54.2 (from 53.6 in May), representing continued solid footing above the 50 mark that divides expansion and contraction. 2 PMI data from Europe’s two biggest economies – Germany and France – also painted a bright outlook for the eurozone economy. The survey also indicated that employment and new orders had risen at the strongest rates in four years over the second quarter, although growth slowed in both cases in the month of June as concern over the re-emergence of the Greek debt crisis surfaced yet again. … While technicals are still supportive Eurozone stock prices, as measured by the Euro Stoxx 50 Index, maintained levels of support across the previous highs established in June 2014 and November 2014 – between 3,275 and 3,375, as seen below. In addition, the chart illustrates that the Euro Stoxx 50 Index is still firmly in the uptrend established in September 2011, while still 25% off the market highs established prior to the global financial crisis. European stocks are in an uptrend, but still off of market highs Euro Stoxx 50 Index high, low and closing values from Aug. 1, 2003, to July 6, 2015 Source: Bloomberg L.P. as of July 6, 2015. Past Performance is not a guarantee of future results. Investments cannot be made directly into an index. Additional tailwind courtesy of the weak euro? The 17% drop 3 in the value of the euro relative to the US dollar since June 30, 2014, coupled with the tremendous run-up in European equities earlier this year, begs the question: Where do eurozone equities go from here? Historically, the year-over-year change in the EUR/USD exchange rate has led the direction of the Euro Stoxx 50 Index by approximately one year. Therefore, euro weakness in the past portends continued upside for eurozone equities, in my view. The chart below illustrates the strong correlation between movements in the EUR/USD exchange rate and the region’s subsequent one-year stock market performance. As described above, the strong PMI levels should augur strong earnings growth, which would support continued appreciation of equities within the eurozone. Correlations have historically been strong between movements in the EUR/USD exchange rate and the region’s subsequent one-year stock market performance Euro Stoxx 50 Index year over year vs. EUR/USD exchange rate plus one year. Note that we’ve inverted the exchange rate line to more clearly illustrate the trends in movement. In reality, downward movements in the exchange rate have tended to precede upward movements in stocks, and vice versa. Source: Bloomberg L.P. as of June 30, 2015. Past Performance is not a guarantee of future results. Investments cannot be made directly into an index. Projections shown are based on the past trends shown in this graphic and are the opinion of the author. There is no guarantee that the projections shown will come to pass. Elevated eurozone valuations highlight potential risk While economic indicators, stock market technicals and the tailwind from the weak euro point to potential continued upside in the eurozone, an analysis of equity valuations underscores the potential risks. Using the Euro Stoxx 50 Index, the chart below illustrates the degree to which valuations are being stretched. Regardless of the metric used (and many were reviewed), the nearly 100% run-up in the eurozone since the September 2011 low has resulted in valuations that despite recent volatility related to the referendum in Greece, are approaching, or have surpassed, decade-long highs. Eurozone equity valuations are approaching or have surpassed decade-long highs Euro Stoxx 50 Index estimated price-earnings (P/E) and price to cash flow Source: Bloomberg L.P. as of June 30, 2015. Past performance is not a guarantee of future results. In addition, since the launch of the EMU’s 60 billion euro a month quantitative easing (QE) program in March 2015, it is instructive to look at the relationship between the Euro Stoxx 50 Index earnings yield relative to the German government 10-year yield to understand the current relative valuation between stocks and bonds in the region. This is shown in the chart below. The current reading reveals that, unlike in the US, eurozone stocks do not appear at this point to be inexpensive relative to bonds, given that the yield spread is near the middle of the range observed since 2005. QE has helped depress German bond yields, but hasn’t thus far resulted in a material difference between the historical relationship between earnings yield and the 10-year German government bond yield. This is due to the fact that stock prices have rallied sharply in recent years, as investors have looked to take advantage of the favorable economic outlook. Eurozone stocks do not appear inexpensive relative to bonds Euro Stoxx 50 Index estimated earnings yield relative to German government 10-year bond yields Source: Bloomberg L.P. as of June 30, 2015. Past performance is not a guarantee of future results. Investments cannot be made directly into an index. Managing volatility amidst eurozone opportunity and uncertainty Given the potential upside of equity exposure to the eurozone (for reasons outlined above), the risk associated with the rise in valuation levels and the ongoing uncertainty associated with a potential Greek exit from the eurozone (or “Grexit”), I believe a volatility-managed solution may be a sensible approach for investors to gain exposure to this critical region. In addition, I believe the divergent monetary policy between the European Central Bank and the Federal Reserve highlights the downside risk to the value of the euro and emphasizes the need for investors to consider a currency hedge to mitigate the foreign exchange risk. A currency-hedged low volatility approach provides investors the opportunity to participate in the upside in the face of stretching valuations and exchange rate risk, as well as a downside risk mitigation smart beta strategy. PowerShares Europe Currency Hedged Low Volatility Portfolio PowerShares has introduced the first ETF offering a currency-hedged low volatility approach to Europe – the PowerShares Europe Currency Hedged Low Volatility Portfolio (NYSEARCA: FXEU ). FXEU provides exposure to the S&P Eurozone Low Volatility USD Hedged Index, which is composed of the 80 least volatile stocks in the S&P Eurozone BMI. Index holdings are currency hedged to the US dollar using rolling one-month forward contracts that are adjusted monthly. The ETF and index constituents are reconstituted quarterly. Constituents are weighted relative to the inverse of the trailing 12-month realized volatility, with the least volatile stocks receiving the highest weights. Learn more about FXEU 1 Source: WorldBank, as of December 2013 – report printed December 2014 2 Source: Markit Economics press release July 3, 2015 3 Source: Bloomberg L.P. as of June 30, 2015 Important information Markit Composite Purchasing Managers’ Index (PMI), a commonly cited indictor of the manufacturing sectors’ economic health, is calculated by the Institute of Supply Management. Price-earnings (P/E) ratio, also called multiple, measures a stock’s valuation by dividing its share price by its earnings per share. Price-to-cash-flow ratio is a stock’s capitalization divided by its cash for the fiscal year. Yield spread is the difference between yields on differing debt instruments, calculated by deducting the yield of one instrument from another. Earnings refer to the amount of profit a company produces during a specific period, typically usually a calendar quarter or year. Valuation is how the market measures the worth of a company or investment. S&P Eurozone BMI is a comprehensive benchmark that includes large, mid, and small caps from developed and emerging Eurozone countries. It is a regional subindex of the S&P Global BMI. The Euro Stoxx 50 Index measures the performance of blue-chip eurozone equities. Valuation is how the market measures the worth of a company or investment. There are risks involved with investing in ETFs, including possible loss of money. Shares are not actively managed and are subject to risks similar to those of stocks, including those regarding short selling and margin maintenance requirements. Ordinary brokerage commissions apply. The Fund’s return may not match the return of the Underlying Index. The Fund is subject to certain other risks. Please see the current prospectus for more information regarding the risk associated with an investment in the Fund. The risks of investing in securities of foreign issuers, including emerging market issuers, can include fluctuations in foreign currencies, political and economic instability, and foreign taxation issues. The Fund may invest in foreign markets and because foreign exchanges may be open on days when the Fund does not price its shares, the value of the non-US securities in the Fund’s portfolio my change on days when you will not be able to purchase or sell your shares. The dollar value of foreign investments will be affected by changes in the exchange rates between the dollar and the currencies in which those investments are traded. Investments focused in a particular industry or sector are subject to greater risk, and are more greatly impacted by market volatility, than more diversified investments. Derivatives may be more volatile and less liquid than traditional investments and are subject to market, interest rate, credit, leverage, counterparty and management risks. An investment in a derivative could lose more than the cash amount invested. Currency hedging can reduce or eliminate losses or gains and can also be subject to imperfect matching between the derivative and its reference asset. There is no assurance the Fund’s hedging strategy will be effective. Some foreign currency forward contracts are less liquid, which may result in the Fund being unable to structure its hedging transactions as intended and may be unable to obtain sufficient liquidity in an underlying currency. As a result, the Fund’s hedging transactions may not successfully reduce the currency risk included in the Fund’s portfolio. The Fund’s investments in futures contracts will cause it to be deemed to be a commodity pool, subjecting it to regulation under the Commodity Exchange Act and Commodity Futures Trading Commission (CFTC) rules. The Adviser, a registered Commodity Pool Operator (CPO), and the Fund will be operated in accordance with CFTC rules. Registration as a CPO subjects the registrant to additional laws, regulations and enforcement policies; all of which could increase compliance costs, affect the operations and financial performance of funds whose adviser is registered as a CPO. Registration as a commodity pool may have negative effects on the ability of the Fund to engage in its planned investment program. Many countries in the European Union are susceptible to high economic risks associated with high levels of debt, notably due to investments in sovereign debts of European countries such as Greece, Italy and Spain. The Fund may hold illiquid securities that it may be unable to sell at the preferred time or price and could lose its entire investment in such securities. The Fund is non-diversified and may experience greater volatility than a more diversified investment. There is no assurance that the Fund will provide low volatility. The information provided is for educational purposes only and does not constitute a recommendation of the suitability of any investment strategy for a particular investor. Invesco does not provide tax advice. The tax information contained herein is general and is not exhaustive by nature. Federal and state tax laws are complex and constantly changing. Investors should always consult their own legal or tax professional for information concerning their individual situation. The opinions expressed are those of the authors, are based on current market conditions and are subject to change without notice. These opinions may differ from those of other Invesco investment professionals. Before investing, investors should carefully read the prospectus/summary prospectus and carefully consider the investment objectives, risks, charges and expenses. For this and more complete information about the Funds call 800 983 0903 or visit invescopowershares.com for prospectus/summary prospectus. NOT FDIC INSURED MAY LOSE VALUE NO BANK GUARANTEE All data provided by Invesco unless otherwise noted. Invesco Distributors, Inc. is the US distributor for Invesco Ltd.’s retail products and collective trust funds. Invesco Advisers, Inc. and other affiliated investment advisers mentioned provide investment advisory services and do not sell securities. Invesco Unit Investment Trusts are distributed by the sponsor, Invesco Capital Markets, Inc., and broker-dealers including Invesco Distributors, Inc. PowerShares® is a registered trademark of Invesco PowerShares Capital Management LLC (Invesco PowerShares). Each entity is an indirect, wholly owned subsidiary of Invesco Ltd. ©2015 Invesco Ltd. All rights reserved. Evaluating opportunity in the eurozone when Greece is (yet again) the word by Invesco Blog.
Northwest Natural Gas: A Solid Dividend Record Doesn’t Overcome Poor Growth Prospects

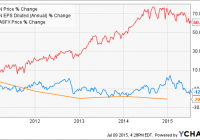
Summary Northwest Natural Gas offers a favorable dividend yield and very strong dividend increase record to yield-seeking investors. The company’s growth prospects are less attractive, however, due to its poor earnings history, high dividend payout ratio, and relatively low capex plans. The presence of warm weather conditions later in the year could make it difficult for the company to achieve management’s EPS guidance for FY 2015 and FY 2016. Its shares are overvalued and do not provide potential investors with a sufficient buffer to offset its poor prospects for earnings and dividend growth. Potential investors should look elsewhere. The share price of Oregon-based public natural gas utility Northwest Natural Gas (NYSE: NWN ) recently approached a 5-year low (see figure) as investors turned bearish on dividend stocks and the company reported disappointing results for Q4 2014 and Q1 2015. Its shares have vastly underperformed the gas utilities sector as its earnings have steadily fallen since FY 2011, excluding a modest increase in FY 2013. While management’s guidance is for its non-adjusted earnings to continue this downward trend, analysts are forecasting back-to-back increases on an adjusted basis for FY 2015 and FY 2016. This article evaluates Northwest Natural Gas as a potential long investment in light of the current operating environment and these forecasts. NWN data by YCharts Northwest Gas at a glance Headquartered in Portland, Oregon, Northwest Natural Gas provides natural gas and related services to more than 700,000 customers in the western half of that state and southwest Washington. It is Oregon’s largest natural gas utility with 14,000 miles of mains and service lines. While its regulated natural gas utility operations represent its primary business segment, the company also owns 31 Bcf of underground natural gas storage capacity and 2 Bcf of LNG storage capacity, the latter of which could be expanded by an additional 10 Bcf in coming years. Its natural gas operations provide the vast majority of its revenue and earnings, however, reaching 98% in recent quarters. The natural gas operations have also benefited from the presence of a moderately favorable regulatory scheme in Oregon that provides weather normalization and decoupling mechanisms to minimize the impact of extreme weather periods on earnings. Finally, the natural gas operations have also benefited from moderate customer growth, with the total number increasing by 4% over the last five years, due to natural gas having only a 60% market share of the heating market in the company’s service area. Northwest Gas has been a stalwart provider of dividends (see figure), with the company stating that its Q4 2014 dividend increase represented its 59th consecutive annual hike. The company’s forward yield of 4.22% is higher than the gas utility sector median , although this has come at the cost of a dividend payout ratio of 0.85 in the most recent fiscal year, well above the sector average. While many utilities are actively working to increase their payout ratios, the presence of such high ratios over a sustained period indicates that Northwest Natural Gas sees few opportunities for substantial future capex, rate base, and ultimately earnings growth. Further evidence of a lack of growth opportunities is provided by the fact that the company’s annual diluted EPS peaked in FY 2010 and has steadily declined in every subsequent year but one. Dividend growth has slowed to a crawl recently as well, with the most recent increase to $0.465 on a quarterly basis representing a mere 1.1% change over the previous quarter and 7% increase over the previous five years (by contrast, peer Southwest Gas (NYSE: SWX ) recently increased its dividend by 11% ). NWN Dividend (Annual) data by YCharts Q1 earnings report Northwest Natural Gas reported underwhelming results for Q1 in May due to a combination of an unfavorable regulatory decision and warm winter weather. Its revenue fell by 10.8% YoY from $293.4 million to $261.7 million, missing the analyst consensus by $42.2 million. The decline was primarily the result of a 19% YoY decline to the company’s natural gas sales and transportation volumes, which was in turn due to an average Q1 temperature that was 22% warmer than the previous year and 20% warmer than the long-term average. The consolidated revenue number was also negatively impacted by last year’s steep fall in the price of natural gas, which coincided with the expiration of the company’s storage segment’s long-term, high-priced storage contracts. These were ultimately replaced with short-term contracts containing lower prices, pushing the segment’s revenue down by $2.5 million YoY from $7.8 million. Northwest Natural Gas Financials (non-adjusted) Q1 2015 Q4 2014 Q3 2014 Q2 2014 Q1 2014 Revenue ($MM) 261.7 240.3 87.2 133.2 293.4 Gross income ($MM) 136.0 120.5 55.0 74.9 138.2 Net income ($MM) 28.5 28.5 (8.7) 1.1 37.9 Diluted EPS ($) 1.04 1.04 (0.32) 0.04 1.40 EBITDA ($MM) 73.1 79.7 14.9 33.0 94.6 Source: Morningstar (2015). Consolidated operating income fell from $75 million to $53 million YoY. While the impact of the fall in consolidated revenue on gross margin was mostly offset by a 1.3% increase to the number of customers over the trailing twelve month period, the fall in operating income was primarily due to an increase to O&M expenses of $18.7 million. This increase was the result of a regulatory decision to disallow the recovery of $15 million of environmental costs, resulting in a $9 million after-tax charge to the company. The operating income result was boosted to the tune of $21.8 million by the aforementioned weather normalization mechanism, however, offsetting much of the negative impact of the quarter’s warm weather. Net income came in at $28.5 million, down from $37.9 million the previous year. Adjusted for the regulatory disallowance, however, net income came in at $37.6 million. Non-adjusted diluted EPS fell to $1.04 from $1.40 the previous year, while adjusted diluted EPS was $1.37. While only a slight decline YoY, the adjusted result still missed the consensus estimate by $0.14. The natural gas utility segment’s EPS increased by $0.04 YoY while the storage segment’s EPS fell by $0.06 over the same period. Most disappointing to investors was the continued decline of the company’s ROE,which fell to 6.3% TTM. In addition to being well below its FY 2009 level of 9.1%, the trailing result is also substantially lower than the company’s allowed ROEs of 9.5% and 10.1% in Oregon and Washington, respectively. The company’s operating cash flow fell substantially in Q1 from $220.1 million in the previous year to $118.2 million. This was attributed to the receipt in Q1 2014 of a $91 million environmental insurance recovery payment, however. While the cash reserve fell to $5.2 million from $17.9 million YoY, management stated during the Q1 earnings call that the company ended Q1 with strong liquidity, as evidenced in part by the fact that it had only $621.7 million in long-term debt and a current ratio of 0.79, up slightly YoY. Outlook Management affirmed during the Q1 earnings call its FY 2015 EPS guidance range of $1.77-$1.97 on a non-adjusted basis and $2.10-$2.30 on an adjusted basis (the annual adjustment being the same as the Q1 adjustment resulting from the regulatory disallowance). This guidance range assumes that customer growth will maintain its recent pace and that weather conditions during the rest of the year will be the same as the long-term average. Investors should be aware of the sensitivity of both of these assumptions to conditions that are outside of the company’s control, however, given their importance to its earnings. Having recently completed comprehensive safety upgrades and with little in the way of short-term capacity expansion planned, Northwest Natural Gas expects to achieve total capex in FY 2015 of $145 million, down from FY 2012 and FY 2013. Investment in storage capacity and pipeline expansions to meet possible industrial demand growth for natural gas is, in addition to not being certain, still several years out. Earnings growth in the next two years will therefore depend on the service area’s weather and economic conditions. In terms of weather, the El Niño event has finally appeared after going missing last year and federal scientists now believe that it could be one of the strongest such events on record. Great news for drought-plagued California could be bad news for Northwest Natural Gas, as El Niño events are historically associated with warm winter weather in the Pacific Northwest as the polar jet stream is pushed north. An earlier NOAA analysis found that Q1 and Q4 temperatures in Oregon and Washington were much warmer than normal during past events, suggesting that higher temperatures will be present in the company’s service area during the coming winter. While Oregon’s weather-normalization mechanism will mitigate the negative impact of these temperatures on the company’s earnings in the event that they are present, they are unlikely to completely offset them. On the plus side, the economies of Oregon and Washington have greatly improved in recent years after lagging behind the U.S. average. The unemployment rate in both states was higher than the U.S. average from 2010 until 2015, at which point the rates in both states fell below the national average (see figure). Likewise, GDP growth in both states recently moved above the national average (see second figure). Both developments are positive for Northwest Natural Gas since households with steady incomes consume more natural gas and are less likely to miss payments. They also indicate that housing construction will increase, resulting in more potential natural gas customers. Oregon Unemployment Rate data by YCharts Oregon Change in GDP data by YCharts These economic advantages are supported by the presence of much lower natural gas prices in 2015 to date than in the same period of the previous year. Electricity for heat has a substantial presence in Oregon and Washington and part of Northwest’s customer growth strategy is to convince residential consumers to convert to natural gas heating. This process is made easier when natural gas is expensive compared to electricity, as has been the case over the last several months (see figure). Oregon citygate natural gas prices at the time of writing are down 47% from their level a year ago, whereas Oregon’s electric retail rate is 16% higher over the same period. Cheap natural gas hurts the earnings from the company’s storage operations, to be sure, but at least this impact is offset by favorable customer growth conditions. Oregon Electric Utility Retail Price data by YCharts Valuation The consensus analyst estimates for FY 2015 and FY 2016 diluted adjusted EPS have fallen over the last 90 days in response to a recent increase to Oregon’s unemployment rate. The FY 2015 estimate has decreased from $2.24 to $2.19, while the FY 2016 estimate has decreased from $2.31 to $2.26. Based on the company’s share price of $43.37 at the time of writing, its trailing P/E ratio on non-adjusted and adjusted bases is 24.1x and 20.4, respectively. Its forward ratios for FY 2015 and FY 2016 are 19.8x and 19.2x, respectively. All of these are high relative to both the sector trailing average of 17.3x as well as the company’s own historical ranges (see figure). In fact, the upward trend of the company’s P/E ratios is incongruous with its declining earnings over the same period; unlike most of its peers, which have seen their shares’ P/E ratios follow their prices higher, the increasing P/E trend of Northwest’s share has been the result of earnings shrinkage rather than a strong share price. NWN PE Ratio (NYSE: TTM ) data by YCharts Conclusion Natural gas utility and storage company Northwest Natural Gas has been moving in the wrong direction in recent years, reporting steadily lower earnings and achieving ROEs that are well below the results allowed by its regulators. Its main attraction as a potential long investment is its extremely impressive track record of (admittedly small in recent years) dividend growth and decent forward yield. Furthermore, both the company’s management and analysts expect it to break its declining earnings streak and report consecutive annual earnings increases on an adjusted basis for the first time in several years in FY 2015 and FY 2016. I am not convinced that these attributes result in a compelling long argument, however, for two reasons. The first is that the earnings growth estimates are predicated on continued customer growth and average temperatures over the next six quarters. While the former is possible, a recent increase in Oregon’s unemployment rate aside, all indications are that Q4 and Q1 in the company’s service area will be substantially warmer than normal, negatively impacting its earnings in those quarters. Furthermore, the company’s share valuations have been pushed to an overvalued level due to its falling earnings in recent years, preventing potential investors from acquiring a buffer against El Niño negative earnings impacts. Between minimal capex growth, unfavorable weather conditions, and overvalued shares, I do not consider Northwest Natural Gas to be an attractive long investment at this time. Yield-seekers may wish to consider it, but I recommend that they instead consider those utilities with superior growth prospects such as IDACORP (NYSE: IDA ), Alliant Energy (NYSE: LNT ), or DTE Energy (NYSE: DTE ).