Tag Archives: income

PKW Shouldn’t Be Able To Outperform SPY Reliably, But It Did
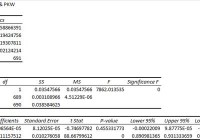
Summary I’m taking a look at PKW as a candidate for inclusion in my ETF portfolio. The risk level is reasonable and the correlation is high. The performance is surprisingly good. The liquidity is solid, so I expect the statistics to be reliable. Despite the higher expense ratio, the ETF has stacked up very well to SPY over the last several years. Investors should be seeking to improve their risk adjusted returns. I’m a big fan of using ETFs to achieve the risk adjusted returns relative to the portfolios that a normal investor can generate for themselves after trading costs. I’m working on building a new portfolio and I’m going to be analyzing several of the ETFs that I am considering for my personal portfolio. One of the funds that I’m considering is the PowerShares Buyback Achievers Portfolio (NYSEARCA: PKW ). I’ll be performing a substantial portion of my analysis along the lines of modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. What does PKW do? PKW attempts to track the total return (before fees and expenses) of NASDAQ Buyback Achievers® Index. At least 90% of the assets are invested in funds included in this index. PKW falls under the category of “Large Blend”. Does PKW provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. Therefore, I start my diversification analysis by seeing how it works with SPY. I start with an ANOVA table: (click to enlarge) The correlation is just under 96%. That’s a very high level of correlation and relatively unattractive for investors hoping for diversification benefits. As an investor using modern portfolio theory, I would prefer to see lower levels of correlation. Of course, the low value correlation wouldn’t mean much if the values were being distorted by poor liquidity. The average volume of nearly 500,000 shares per day suggests that liquidity shouldn’t be a concern. That’s a good sign for investors wanting verification of the statistics or wanting to know that they can exit the position with less concern about it deviating from NAV. Standard deviation of daily returns (dividend adjusted, measured since November 2013) The standard deviation is fairly reasonable. For PKW, it is .787%. For SPY, it is 0.748% for the same period. The ETF is definitely showing a little more volatility than SPY when we compare returns on a daily basis. Mixing it with SPY I frequently run comparisons on the standard deviation of daily returns for the portfolio, assuming that the portfolio is combined with the S&P 500. However, for PKW, I don’t think that adds much value. The correlation being nearly 96% really destroys the benefits of diversification. Why I use standard deviation of daily returns I don’t believe historical returns have predictive power for future returns, but I do believe historical values for standard deviations of returns relative to other ETFs have some predictive power on future risks and correlations. Yield and Taxes The distribution yield is 1.06%. I like to see strong yields for retiring portfolios, because I don’t want to touch the principal. By investing in ETFs I’m removing some of the human emotions, such as panic. Higher yields imply lower growth rates (without reinvestment) over the long term, but that is an acceptable trade off in my opinion. This ETF doesn’t have a high yield, but I am far enough away from retirement to be willing to work with the weaker yields. Expense Ratio The ETF is posting an expense ratio of .68%. That’s high compared to most of the ETFs that are appealing to me, but the expense ratio may reflect the premium being charged for the trading methodology the ETF is using to determine the positions within the ETF. Market to NAV The ETF is at a .06% discount to NAV currently. Premiums or discounts to NAV can change very quickly, so investors should check prior to putting in an order. Generally speaking, that discount to NAV isn’t big enough to be a big deal. However, even a small discount to NAV is fairly attractive when we are talking about a high quality ETF. Largest Holdings The diversification in the holdings isn’t going to be a strong selling point. (click to enlarge) Conclusion PKW was one of the most difficult ETFs to make a decision about. The ETF posts a very high correlation to SPY and a high expense ratio. Some screeners don’t have a portfolio turnover ratio for the ETF, but the prospectus states that in the last fiscal year the turnover ratio was 92%. I expect that kind of turnover to require some costs, but I generally don’t want to pay higher turnover ratios because my use of ETFs involves relying on markets to be reasonably efficient. If the markets are thoroughly efficient, then creating a proprietary trading system to select which positions to enter and which ones to end should not result in any reliable excess returns. However, history is providing some support for the methodology PKW is using. I was suspicious about their outperformance of SPY in the test period, so I extended my sample to a five-year period and looked at the returns on a time line. The result is that PKW outperformed SPY meaningfully over that five-year period. Looking at the lines, it isn’t a single period where PKW outperformed either. The fund’s performance has been strong and steady, which makes it appear more repeatable. I wanted to eliminate the ETF for the high expense ratio and relative weakness in diversification, but I can’t do it. Maybe it is just chance that eventually an ETF had to deliver this kind of strong performance over an extended period, but I won’t toss out an ETF that makes a fairly impressive case for itself without digging deeper. Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis. The analyst holds a diversified portfolio including mutual funds or index funds which may include a small long exposure to the stock.
How Cash Can Boost Long-Term Returns

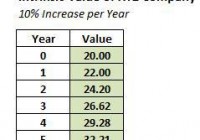
Summary Liquidity management is one of the most critical aspects of investment. Cash earns a 0% nominal return, but allows investors to take advantage of higher-return opportunities that may emerge. By holding more cash, one is betting that the purchasing power will increase at a future point. Moderation is key with holding cash; it’s rarely advisable to go to 100% cash or 0% cash. I’d recommend a cash position in the 20% – 40% range for most investors right now due to higher than average risks in the market. Buying stocks at depressed prices (i.e. with a large “margin of safety”) is the best way to generate superior returns over time. Cash, on the other hand, generates a 0% return. Absent a highly unlikely episode of hyper-deflation, you cannot become wealthy holding cash. In spite of this, I’d recommend holding 20% – 40% of your portfolio in cash right now. The reason for this is that there is value to liquidity, particularly in an inflated market environment. By holding cash, what you are actually doing is betting that the future value of your money in the market will be worth more than the present value. How can cash help you generate better returns? The key is to understand intrinsic value and the mathematics of investing. Intrinsic Value Price is what you pay for an asset. Intrinsic value is the fundamental worth of an asset. Therefore, an asset could be priced at $20,000, but have an intrinsic value of $30,000. In that instance, you are getting a bargain, because you are paying 33% less than the intrinsic value. In reality, it’s impossible to know the exact intrinsic value of a stock. None of us can see the future. Yet, we can come up with reasonable estimates of intrinsic value through a fundamental analysis of a company. That said, in order to explain why holding cash can be beneficial, we’ll first need to assume we can read the future. In this scenario, let’s say we know with absolute certainty that the intrinsic value of XYZ Company’s stock is $20. Now, we’re going to be able to live in five different alternate realities. In the first scenario, XYZ Company’s stock is selling at the depressed price of $5. In the second scenario, the stock sells at a still somewhat depressed price of $10. The third scenario will allow us to purchase the stock for $20; which is precisely the intrinsic value. In the fourth scenario the stock will sell at an inflated price of $25, and in the fifth scenario, it will sell at an even more inflated price of $30. Now, we’ll say that in each of our five alternate realities, we will purchase the stock and hold it for five years. We also know for a fact that the intrinsic value will grow 10% per year. You can see how the intrinsic value grows in the chart below. With that, let’s take a look at what happens. The Power of Compounding Now that we’ve created the set-up, you can see the return figures for all five scenarios below for a five-year holding period. It immediately becomes clear how dramatic the difference is between purchasing XYZ’s stock at a depressed price versus an inflated price. The “inflated price” only yields a 1.4% annual return, while the “depressed price” yields an astronomical 45.1% annual return! To put this further in perspective, if you started with $10,000 and generated a 45.1% annual return for the indefinite future, you would have $100,000 in a little over 6 years. On the other hand, if you generated a 1.4% for the foreseeable future, it would take you 166 years for you to turn that $10,000 into $100,000. That’s not a misprint! That’s the power of compounding. This is also the reason why an investor that generates a 17% annual return over 10 years is significantly better than one generating a 15% annual return. It may seem like a very small difference, but over a long-term timeframe, it really adds up. An investor making 15% annually on a $10,000 initial investment for 25 years would have $329,000 at the end of that timeframe. An investor generating a 17% annual return, on the other hand, would have $507,000; roughly 54% more. Why Cash is Valuable Given this math, it starts to become clearer why holding cash can sometimes led to higher long-term returns. Let’s say that XYZ’s stock was selling at the inflated price of $30, but you could see the future, and knew it could fall back down to $15 in 3 years. For simplicity’s sake, we’ll still assume that you plan to sell off at the end of Year #5 at the intrinsic value of $32.21. What would be your best option? (1) Buying the stock immediately and earning the 1.4% return for 5 years, (2) Holding cash for 3 years and then buying in at the semi-depressed price of $15 The answer is that option #2 is much more profitable. After five years, you’ll only generate a total return of 7.2% in Scenario #1, but you’ll achieve a 114.7% return in Scenario #2, in spite of the fact that you made a 0% return the first three years. This example showcases why the relationship between price and value are so important. It also shows why value investing works so well. What may seem like small differences in price can drive very large differences in return. Hold Some Cash Given the inflated market environment we are currently seeing, I believe it’s prudent to hold 20% – 40% of one’s portfolio right now. It’s true that you’ll likely underperform in the short-term (e.g. 1-3 years) as a result of this strategy. However, in the long-term, it makes more sense to take the 0% return now (on a part of your portfolio), and then use the liquidity to strike later when the returns become much more attractive. Of course, this should not dissuade you from taking advantage of bargains as you see them become available. And while I believe the broad market is overpriced, on a micro level, there will always be bargains out there. Yet, even if you can find a lot of bargains, I’d still recommend holding a good clip of cash, because even better bargains could become available the next time we find ourselves in a recession or a falling market environment. How much cash you hold in your portfolio depends upon your preferences and personal situation. If you’re in a situation where you can’t afford to lose much right now (i.e. you might need your cash for other purposes), I would recommend playing things fairly conservatively and holding a very large cash position. Even if you’re not worried about pulling out cash, I do think a minimum 10% cash position is prudent; and frankly, I wouldn’t dip below 20%. Conclusions Holding cash and generating a 0% return may seem like a poor option on the face of it, but once you understand the math behind returns, it makes a lot sense. By holding cash now, you’re hoping that you can generate higher returns in a future environment with lower prices. It’s never wise to go 100% cash, because at that point, you’re merely speculating. In an environment where stock prices seem inflated and there are few bargains out there, it makes sense to hold an elevated cash position in the range of 20% – 40% of your portfolio. On the other hand, in a depressed stock environment (such as the one we saw in late 2008 and early 2009), you should try to be as fully invested as possible, holding no more than 5% cash. Right now, I view us as being in an inflated environment and holding a 20% – 40% cash position is a prudent strategy. Your returns will lag in the short-term, but if there’s a market correction, you’ll more than make up for it in the long-term. This article appears in the February 2015 edition of Jake Huneycutt’s Contrarian Value Newsletter Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it. The author has no business relationship with any company whose stock is mentioned in this article.

5 Ways To Play Rising Rates With Hedged And Inverse ETFs

The recent U.S. labor market data yet again corroborated the sturdy U.S. economic growth. While weak wage growth has been bothering the investing world for quite some time, a better than expected average hourly earnings data finally wiped out investors’ fears. In this backdrop, most have started speculating a sooner than expected hike in the Fed interest rates, which have been at a rock-bottom level for long. Yields on 10-year Treasury notes crossed the 2% mark on February 10 for the first time after January 8, 2015. Fixed-income investing had enjoyed a great show in 2014 and so far in 2015, especially in the longer part of the yield curve. However, the prospect of rising rates and risks to capital gains of the bond holdings have left investors jittery about the safety of their portfolios and brought rate rise worries back on the table. Given the situation, many investors are definitely pulling their money out of the bond market. At a time like this when investors are extremely cautious about rising rate risks and stock market volatility, investments in U.S. bonds with significant protection against potential rising rates can be good bets. Some opportunistic investors could capitalize on this backdrop in the form of inverse ETFs too (read: Two Interest Rate Hedged ETF Launches from iShares ). iShares Interest Rate Hedged High Yield Bond ETF (NYSEARCA: HYGH ) This fund holds in its basket iShares iBoxx $ High Yield Corporate Bond ETF (NYSEARCA: HYG ) while taking short positions in U.S. Treasury futures to diminish rising rate concerns. HYGH has a weighted average maturity of 4.60 years while its effective duration stays ultra-low at 0.32 years. HYGH is high yield in nature as evident from its 30-day SEC yield of 5.47%. HYGH charges 0.55% of expense ratio. The fund has added about 2% in the last five trading sessions (as of February 10, 2015) (see all the junk bond ETFs here). ProShares High Yield Interest Rate Hedged ETF (BATS: HYHG ) HYHG is another ETF, which has an interest rate hedge built into its strategy as it takes a short position in U.S. Treasury futures. Like HYGH, it also has a pretty high yield (and a modest expense ratio of just 50 basis points) of 5.9% in 30-Day SEC terms, indicating that this could be a safer bond and yield play for investors anxious about the possibility of rising rates. This $125.4 million ETF was up 1.9% in the last five trading sessions (as of February 10, 2015) (read: 5 Dividend ETFs to Buy for Income in 2015 ). ProShares Investment Grade-Interest Rate Hedged ETF (BATS: IGHG ) This investment grade fund too offers interest-hedge benefit to investors. The fund looks to track the Citi Corporate Investment Grade (Treasury Rate-Hedged) Index, which comprises long positions in USD-denominated investment grade corporate bonds issued by both U.S. & foreign domiciled companies while adopting short positions in US Treasury notes or bonds of approximate equivalent duration to the investment grade bonds. The index seeks to achieve an overall effective duration of zero. Its 30-Day SEC yield stands at 3.32% (as of February 10, 2015) while it charges 30 bps in annual fees. The fund was up 1.1% in the last five trading sessions (as of February 10, 2015). Barclays Inverse US Treasury Aggregate ETN (NASDAQ: TAPR ) The note provides investors a unique strategy to hedge against or benefit from the rising U.S. dollar interest rates by tracking the Barclays Inverse US Treasury Futures Aggregate Index. This benchmark employs a strategy, which follows the sum of the returns of the periodically rebalanced short positions in equal face values of each of the 2-year, 5-year, 10-year, long-bond and ultra-long U.S. Treasury futures contracts (read: Interest Rate Speculation: A Boon for TAPR ETF ). If the price of each Treasury futures contract increases or decreases by 1% of its face value, the value of the index would decrease or increase by 5% over the same period. The fund charges 43 bps in annual fees and trades in light volume of under 5,000 shares per day on average, ensuring additional cost in the form of a wide bid/ask spread. The fund has added about 16.6% in the last five trading sessions. iPath US Treasury 5-year Bear ETN (NASDAQ: DFVS ) The fund looks to track inverse movements in the yields from buying 5-year U.S. T-Notes. To do this, its underlying index tracks the returns of an investment in a weighted “short” position in relation to 5-year Treasury contracts. This $4.8 million ETF was up about 8.9% in the last five trading sessions. The fund charges 75 bps in fees. Bottom Line As a caveat, investors should note that these inverse products are suitable only for short-term traders as these are rebalanced on a daily basis (see: all the Inverse Bond ETFs here). Still, for ETF investors who are bearish on the bond market in the near term, any of the above products could make an interesting choice.