Tag Archives: function

How Do You Find Value Investment Ideas?

It’s easy to drown while trying to drink from the fire hose of information that is the stock market. After 25+ years of value investing successes and failures, I’ve come up with my 11 favorite shortcuts to finding promising companies. Did I miss any shortcuts? How do you find value investment ideas? I’ve got the fire roaring, eggnog in hand, enjoying some downtime during the hectic holiday season. The New Year is approaching, which inevitably has me looking back over the investment year that was. There were some successes and, as always, there were some failures. I still flinch while thinking about my ill-timed “deworsification” into the Russian stock market. One question I always try to answer is, “How exactly did I find my best ideas?” Value investing is for investors with a long-term outlook and simply looking back over the last year is not going to be very informative. The sample size is too small and not enough time has elapsed to let investment themes play out. So instead of just looking at the past year, I decided to go back a little further. During my investment career, I have spent a substantial amount of time searching for excellent value ideas. But finding that one gem in the ocean of possible alternatives can be overwhelming. It’s easy to drown while trying to drink from the fire hose of information that is the stock market. So over time, I have unearthed many useful tools that have helped me to discover great ideas. Some of these shortcuts started off extremely useful and continue to be powerful, but some simply didn’t pan out or lost their efficacy. I went back over the last 25+ years of my investing career and tried to recall how I first stumbled across each successful investment idea. I then narrowed this list down to the top 11 ways to find new ideas that I have found most useful. The list progresses from least to most valuable. Traditional Media – I wasn’t sure if I should include media on this list as it can really be more of the delivery mechanism for the other criteria below, but I have been spurred to look closely at a company because of information I’ve gathered through various media outlets, including newspapers, television and business websites. I tend to find investable concepts more than individual stock picks using traditional media, and there is a ton of noise, but there’s a lot of good information out there if you look hard enough. Removal From an Index – Obviously, when a stock is dropped from an index, there is forced selling by index funds that hold the name. However, the index sponsors also try to game the system. Companies that are added to an index tend to be sexy and on an upward trajectory, while companies that are dropped from an index tend to be stodgy and are often out of favor. The oversold cast-offs can be an attractive place to discover value investments. New CEOs – This really depends on the specific situation. If a company’s CEO is retiring after being named Time Magazine’s “Person of the Year”, when the company’s stock price is at an all-time high, it’s not going to attract my attention. If a CEO is pushed out by the board after failing miserably, now we’re talking! A new CEO can make a huge difference in the right situation. Companies that tend to benefit the most from a change at the top tend to have a smaller market cap, a manageable debt load and strong free cash flow. Biggest Percentage Losers – I check the biggest losers list every day. Most of these stocks deserve the sell-off, but every so often a great idea can be salvaged from this discard pile. When bad news comes out, many investors sell first and ask questions later, if ever. I’ve worked as an equity analyst and I have seen this first hand. The thought of going into a client meeting with a dog that dropped 40% makes investment professionals cringe. Stocks that drop dramatically often sail right past true value. 52 Week Lows – This is another list that I check every day. What’s on the list? Why? It’s a fantastic way to spot industry trends as well as to find individual companies that have been left for dead. It’s a fantastic list to use to find bargains, but just because a stock is at a 52-week low, it doesn’t mean it’s undervalued. Exiting Bankruptcy – Companies that are overlooked with a checkered past can often lead to very attractive gains. Bondholders often receive equity when a company emerges from bankruptcy and many times they sell it quickly, depressing the company’s share price. Organizations that are exiting bankruptcy often have smaller debt loads and have shed unattractive businesses during their reorganization, yet are still covered in the taint of failure. If you feel your nose wrinkling as your face contorts into a look of disgust upon hearing the name of a company that imploded into bankruptcy, but is now emerging, you may be on to a great investment idea. Insider Buying – A sizeable open market purchase by an individual with intimate knowledge of a business can be a fantastic buy signal. However, there can be a lot of noise. Ignore small, insignificant purchases and stock acquired through options. Pay more attention to open-market purchases by company management with a good track record of buying and selling stock, especially when there is size to their trades. Gurus – Do you have a team of 20 well-paid, remarkably intelligent and highly-trained analysts at your disposal? No? Neither do I, but many successful value managers have this and much more. So why not utilize their resources? I don’t tend to get too excited when I see that 40 hedge fund managers own Apple, but when a highly-respected value manager purchases 5% of a $100 million company, then I tend to take notice. Always pay attention to the type of manager you follow as some trade frequently and utilizing their public filings is not advisable. However, there is an extended list of value managers with long-term time horizons and superior track records that trade infrequently. Untraditional Media – I would include blogs and newsletters in this category, including Seeking Alpha. Ideas from untraditional media can be hit or miss, but I’ve cultivated a small group of analysts/investors that I genuinely trust and rely on. Unlike many of the other resources I use to find investment ideas, I can assume that the ideas presented by this trusted group will be well-thought-out and worth a second look. I’m always searching for smart investors that share the same value investing methodology as myself. Sentiment – As a value investor, I want to see high negative sentiment. The more hated and despised a company is, then the more interested I become. When everyone is negative, the slightest positive news can start to move a stock upward. I have always viewed traditional academic value screens as a measure of sentiment. The reason most companies are trading in the bottom decile of book value is that they are hated. Some of my favorite valuation screens include price/book, price/sales and EV/EBITDA. If these metrics are depressed, you likely have a company with very poor sentiment. Spin-offs – I know. I’m sure many of you are cringing, wondering why you should sit through another narrative on why spin-offs are so great. I agree…but they still work. I won’t go through all of the reasons that spin-offs tend to outperform as the information is freely available across the internet. If the information is so freely available, shouldn’t the strategy stop working? Yes, it should. But when going back through my investing career, I have used the strategy to consistently find huge winners. I imagine that spin-offs will lose their ability to outperform eventually, but I don’t believe we are at that point just yet. Index funds still dump spin-offs that are not in their index and individuals still dump the 25 share position that has magically appeared on their brokerage statement. Although investors need to be more selective when investing in spin-offs today, especially when many savvy investors are familiar with the strategy, there are still excellent opportunities available. Hopefully I’ve been able to outline a strategy or two that readers will find helpful. Undoubtedly, there are many more strategies that successful investors use to uncover great value ideas that I have missed. I’d love to hear from the Seeking Alpha community. How do you find value investment ideas?
Clean Energy Fuels: Weighing The Pros Against The Cons

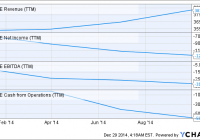
Summary Except for revenue, Clean Energy Fuels saw a decline in other key metrics in 2014. Clean Energy is burning through cash as it invests in infrastructure to tap the natural gas fueling market. Since natural gas-powered vehicles are expected to grow over 20 times in the next six years, it is important for Clean Energy to invest in infrastructure. Clean Energy, however, needs to make a quick turnaround in order to arrest a rapidly rising debt/equity ratio and a declining profit margin. It can be easily concluded that 2014 has been a year to forget for Clean Energy Fuels (NASDAQ: CLNE ), with the stock having depreciated almost 60%. This doesn’t come across as a surprise, because the company’s revenue growth hasn’t led to an improvement in its profitability. In addition, the company is burning through cash. The following chart will give us a bird’s eye view of Clean Energy Fuels’ problematic 2014. CLNE Revenue (NYSE: TTM ) data by YCharts But, the decline in Clean Energy’s net income, EBITDA, and cash from operations isn’t surprising at all as the company operates in an industry that’s making gains at a fast pace. According to Navigant Research , the global market for natural gas vehicles (NGVs) will reach 35 million units by the end of the decade, an impressive increase over 1.5 million units this year. Now, Clean Energy provides fueling infrastructure for these trucks. Considering the rapid pace at which the usage of NGVs is expected to grow in the future, Clean Energy needs to build up its infrastructure. This is the reason why the company’s financial performance has not been up to the mark this year, as it has aggressively invested in its infrastructure. But, the good thing is that it has positioned itself nicely for growth in the future. In fact, in 2015, its loss is expected to drop to $0.83 per share from the expected 2014 loss of $1.07 per share, translating into an improvement of 22.4%. Additionally, its revenue is slated to improve 15%. Moreover, for the next five years, Clean Energy’s bottom line is expected to continue improving at an annual rate of 25%. Factors Driving the Bullish Case The question is: Can Clean Energy actually achieve the expected growth rates? I think it can. The company recently closed two key strategic transactions with Mansfield and NG Advantage , and both these will allow it to tap key growth markets. NG Advantage has a robust compression infrastructure in place. As a result, it can provide cheaper natural gas for the facilities and vehicles of Clean Energy’s customers. Mansfield Energy, meanwhile, is a key behind-the-gate fuel provider in the U.S. It has partnerships with more than 900 petroleum hauling carriers countrywide. Through this venture, Clean Energy will operate closely with Mansfield’s haulers for transitioning their fleets to natural gas. Now, the addressable market opportunity that this joint venture has opened up is worth 3 billion gallons of diesel a year. In comparison, Clean Energy delivered 159 million gallons of natural gas in fiscal 2013. Hence, there is a big market that Clean Energy can tap as a result of the Mansfield deal. Apart from these partnerships, Clean Energy is also spending on the growth of its organic infrastructure. So far this year, Clean Energy has closed 49 station projects, and it has another 28 station projects under development. Driven by these infrastructure improvements, Clean Energy has been able to increase its customer count on the back of improved capacity. For instance, Clean Energy has signed a deal with Dillon Transport, and plans to open three truck-friendly public CNG stations to maintain Dillon’s expanding fleet of 200 natural gas trucks. Once fully deployed, these are expected to use 2.5 million gallons of fuel per year. The Bearish Case However, not everything is rosy about Clean Energy, as the following chart shows: CLNE Profit Margin ( TTM ) data by YCharts Clean Energy’s profit margin has been declining at a very fast pace, while its debt is rising at the same time. Presently, the company has total cash of $248 million, while its debt stands at $619 million. Also, as mentioned earlier in the article, it is burning through cash. The company’s operating cash flow is a negative $58 million in the past one year, while levered free cash flow is also negative at $121 million. Thus, if Clean Energy is unable to make a quick turnaround, its position might deteriorate further. This is a risk that investors need to be aware of. Conclusion As I mentioned in my bullish case, Clean Energy’s bottom line is expected to improve at an impressive pace. Given the prospects in the natural gas fueling market and Clean Energy’s own investments, there is a good probability that the company will be able to make a comeback in the future.

How I Earned 17% Compound Annual Return For 6 Years

Summary Using a carefully crafted portfolio of 18 stocks, I have beat the S&P 500 for the past six years. My portfolio consists of Consumer Stocks, Utilities and Railroads. I buy stocks in small increments on pullbacks to reduce risk and increase profit. Using a carefully crafted portfolio of 18 stocks, I have achieved 17.17% compound annual return since Jan. 1, 2009. I have been investing money for 21 years, and achieved my best years from 2009 to 2014. This article will discuss why I purchased these stocks and my outlook for 2015. My strategy is first and foremost not to lose money. Cash is king. Much of the gains in recent years were from decisions that I made five and 10 years ago. I invested in consumer, utility and railroad stocks that have durability, decent profit margins and a solid future. Over the years, I tended to sell the losers and buy more of the winners. Own the best and sell the rest. Nearly all my gains were from stocks. I only added bonds to the portfolio in early 2014. My brokerage accounts at Charles Schwab have achieved 17.17% compound annual returns from Jan. 1, 2009, to Dec. 24, 2014, compared with 14.41% compound annual return for the S&P 500 over the same time period. If you look at the this chart on my personal blog, you will see my portfolio risk and return are better than a typical aggressive portfolio. Schwab says the risk or standard deviation for an Aggressive Portfolio is 15.40 and the return 15.07. My risk was lower at 11.79, and my 17.17% return was 2.1% better than an Aggressive Portfolio. Below are the securities in our largest brokerage account, which was up 17% in 2014. Name Purchase Price Price on Dec. 28, 2014 % of Portfolio My % Return YTD Return to 12/28/14 Berkshire Hathaway (NYSE: BRK.B ) 117.43 151.35 12.63 28.88% 27.66 Boston Beer Co. (NYSE: SAM ) 218.67 295.74 10.86 35.25 22.31 Canadian National Railway (NYSE: CNI ) 57.32 68.69 1.15 19.84 20.47 Church & Dwight (NYSE: CHD ) 62.14 80.18 6.96 29.03 20.97 Coca Cola (NYSE: KO ) 28.31 42.96 2.72 51.77 3.99 Colgate-Palmolive (NYSE: CL ) 63.90 70.88 0.3 10.93 8.69 ConAgra Foods (NYSE: CAG ) 23.80 36.86 0.26 54.86 9.38 Dominion Resources (NYSE: D ) 58.17 79.28 4.23 36.29 22.56 DuPont (NYSE: DD ) 45.51 75.13 0.21 65.08 15.64 Hershey (NYSE: HSY ) 97.91 106.41 1.78 8.69 9.44 JM Smucker (NYSE: SJM ) 83.77 103.39 0.86 23.41 -0.22 Johnson & Johnson (NYSE: JNJ ) 66.45 105.06 1.31 58.11 14.71 McDonalds (NYSE: MCD ) 75.50 94.78 0.24 25.54 -2.32 Norfolk Southern (NYSE: NSC ) 94.62 111.54 0.28 17.88 20.16 PepsiCo (NYSE: PEP ) 78.70 97.05 2.27 23.32 17.01 Reynolds American (NYSE: RAI ) 37.28 65.71 0.38 76.27 31.45 Union Pacific (NYSE: UNP ) 78.71 120.39 32.14 52.96 43.32 Westar Energy (NYSE: WR ) 36.10 41.87 0.7 15.98 30.15 Burlington Northern Santa Fe 3.05% Due 03/15/22 0.97 100.6348 4.2 3.35 + 3.05% coupon =6.4% N/A Burlington Northern Santa Fe 3.05% Due 09/01/22 0.99 99.9219 4.17 1.90+3.05% coupon = 4.95% N/A Union Pacific 2.75% Due 04/15/23 0.95 98.6744 4.12 4.27+2.75% coupon=7% N/A Union Pacific 2.95% Due 01/15/23 0.96 100.3483 4.19 4.32+2.95% Coupon = 7.27% N/A Cash 1.00 1.00 4.04 You can see that 16.67% of the portfolio is invested in railroad bonds. I bought my Investment Grade bonds on Feb. 3, 2014. U.S. interest rates actually fell in 2014, so my bonds appreciated. My total return on my bonds in 2014 — appreciation plus coupon — was 6.4%. Going forward, I believe my bonds will lose value, because I expect interest rates to rise in 2015. However, I am prepared for these bonds to lose up to 10%, even 20% of market value. I like the income. I plan to hold the bonds to term, so I will not lose anything. From the chart, you can see that my largest holding is Union Pacific ( UNP ) at 32.14% of my portfolio. There is some risk involved with owning so much stock in one company, but the outlook for Union Pacific, and railroads in general, is outstanding. Until that changes, I plan to hold my railroad stocks. When I was a reporter working for a local newspaper, a banker used to come up to me at public meetings and ask me to bring my car loans to him. I would always tell him that I have no car loans, my cars are paid off. One day, he came up to me at a black tie event where he interrupted me while I was talking with some friends. Like an aggressive car salesman, the banker said, “Hey Mike we just dropped our interest rates on home loans. Why don’t you bring your home loan to my bank?” I became incensed. I said, “Mr. Banker my house is paid off. I don’t have any debt. I would be happy to lend you some money if you need it.” He sheepishly walked away and never came up to me again asking for my business. The above story illustrates a point. Bankers are eager to lend money. Many people accept the easy credit and never get out of debt. They don’t benefit from America’s pro-capitalist system that favors ownership of property and businesses. If you want to get ahead in life, stop working for bankers. Make them work for you. Pay off your debts, put your money in the bank and earn interest. Become a capitalist. Own property that appreciates in value. Buy stock in companies that are going to benefit from consumers’ daily spending habits. I own several consumer stocks. My favorite is Church & Dwight ( CHD ), a consumer household products company that owns Arm & Hammer Baking Soda and Trojan condoms — stuff people need regardless of the economy. I also own Colgate-Palmolive ( CL ) , seller of pet food and toothpaste, and Reynolds American ( RAI ), a tobacco company with a history of increasing dividends. I own no biotech stocks. In 2008, I lost about 7% of my investment in Dendreon ( OTCPK:DNDNQ ) after holding it for about four months. I sold it. I also lost money on a pain management company. After these mistakes, I vowed to stay away from biotech and most health care stocks. I own Johnson & Johnson ( JNJ ) because it is so diversified, owning a lot of personal care products as well as medical supplies. I own no mutual funds in our brokerage account. I don’t want to give money to mutual fund managers, who take 1% or even 2% management fees. Cut out the management fees, and there is more money available to invest and compound over time. We own some Vanguard 500 Index Fund (MUTF: VFINX ) in an individual retirement account. Money managers have a tough time trying to beat the Index, so why not just own the index? I buy stock in increments on pullbacks to reduce risk and increase profitability. This really paid off in buying stock in Boston Beer ( SAM ), another great consumer stock. I bought SAM shares in the first nine months of 2014 at an average price of $218; the stock recently hit $288 per share, a 32% gain. My stocks and bonds provide steady income. I do not participate in dividend reinvestment plans. Cash dividends go into my accounts, where they sit in a money market fund until I can find the next deal. I have some regrets. I bought Apple (NASDAQ: AAPL ) at $14 per share in 2000 when it had $12 per share in cash. I sold it at $18 per share when iTunes was introduced. That was a huge mistake. Part of the reason I sold it was to get out of tech and stay focused on my consumer stocks, utilities and railroad stocks. Money managers can find much to criticize with my account. I have too much exposure to railroads. However, I have written about railroads for 20 years. I understand their business models. I believe there is a renaissance taking place in rail today. Railroads are four times more efficient than trucking, especially over long distances. In 2014, railroads experienced their best year since 2007. Conclusion My portfolio is not for everybody. I can handle the risk associated with my overweight positions. I expect 2015 to be a tough year to make money. If low oil prices drag down other asset classes, we could see a bear market. However, consumers are loving the 30% gas price cut. The extra money saved at the pump will likely not sit idly in their bank accounts. I expect consumers to spend more money in 2015 than they did in 2014. The U.S. economy is growing, and this bodes well for the stock market. I am prepared for a 10%, or even 20% correction. If that happens, I will not sell stocks, I will look for opportunities to buy quality assets on the cheap. Editor’s Note: This article covers one or more stocks trading at less than $1 per share and/or with less than a $100 million market cap. Please be aware of the risks associated with these stocks.