Tag Archives: function

The 5 Funds – Q4 2014 Portfolio Review
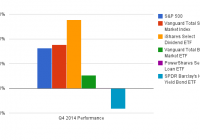
Summary Reviews the performance of The 5 Funds Portfolios. The Vanguard REIT Index was the top performing ETF in the portfolios last quarter. Junk Bonds and International ETFs were the worst performers. Each quarter I plan to update my 3 portfolios: The Aggressive 5, The Moderate 5, and The Conservative 5 and show the performance from the previous quarter, as well as since inception. I’ll also give an update on why I’m making some of the changes and my quick market update. Hopefully this will be helpful for people either following my portfolios or creating their own ETF portfolio. The Conservative 5 Name Symbol Type Allocation Change Vanguard Total Stock Market Index ETF (NYSEARCA: VTI ) Large Cap Blend 25% +5% 1 iShares Select Dividend ETF (NYSEARCA: DVY ) Mid-Cap Value 16% +1% 3 Vanguard Total Bond Market ETF (NYSEARCA: BND ) Intermediate Term Bond Fund 35% None PowerShares Senior Loan ETF (NYSEARCA: BKLN ) Short Term Bond Fund 0% -10% 2 SPDR Barclay’s High Yield Bond ETF (NYSEARCA: JNK ) High Yield Bond Fund 9% -1% 3 iShares Floating Rate Bond (NYSEARCA: FLOT ) Short Term Bond Fund 10% +10% 1 Cash Cash 5% -5% 2 Updated 1/4/2015 Add Allocation Reduce Allocation Investment Drift (No New Trades Required) Conservative 5 Performance* Conservative 5 SPY (S&P 500) Last Month -0.6% -0.3% QTD 2.0% 4.9% YTD – – Since Inception (10/1/2014) 2.0% 4.9% Std Dev. compared to SPY .31 1.0 As of 12/31/2014 Performance by ETF January 2015 Update The biggest update to the Conservative 5 Portfolio ​is the removal of PowerShares Senior Loan ETF and replacing it with the iShares Floating Rate Bond. The reason for the change is that I’m concerned with the amount of volatility in BKLN. As we saw, it took a few large dips in the 4th quarter of 2014. BKLN consists of a lot of lower quality bonds which is the reason for the volatility, FLOT is a more conservative, less volatile ETF which allows us to increase our position in VTI without adding much additional volatility to the portfolio. We continue to favor equities over bonds in 2015 and feel as rates rise and bonds are hurt, the equity market should outperform. We have also reduced the cash position in the account to 5% and moved that money over to Vanguard Total Stock Market Index. This move will add slightly more risk to the portfolio, but the overall risk of the portfolio should not be increasing significantly. The Moderate 5 Name Symbol Type Allocation Change Vanguard Total Stock Market Index ETF VTI Large Cap Blend 60% +5% 1 Vanguard FTSE Developed Markets ETF (NYSEARCA: VEA ) Large Cap International 5% -5% 2 Vanguard FTSE Emerging Markets ETF (NYSEARCA: VWO ) Emerging Markets 0% -5% 2 Vanguard Total Bond Market ETF BND Intermediate Bond 20% None Vanguard REIT ETF (NYSEARCA: VNQ ) REIT 5% None PowerShares QQQ ETF (NASDAQ: QQQ ) Large Cap Growth 5% +5% 1 Cash Cash 5% None Updated 1/4/2015 Add Allocation Reduce Allocation Investment Drift (No New Trades Required) Moderate 5 Performance* Moderate 5 SPY (S&P 500) Last Month -1.1% -0.3% QTD 3.3% 4.90 YTD – – Since Inception 3.3% 4.9% Std. Dev compared to SPY .63 1.0 ​ As of 12/31/2014 Performance by ETF January 2015 Update We made 2 fairly large updates to The Moderate 5 portfolio during this reallocation, both of which focused on reducing our international exposure and increasing U.S. exposure. We have seen emerging markets really struggle lately because of the rising dollar and many EM countries, like Russia, are oil exporters, so the lower oil prices have weighed on their economy. We have replaced our Emerging Markets ETF with QQQ, which is a technology themed U.S. growth ETF. We believe that the tech sector will continue to grow in 2015 and this should be a good compliment to the Vanguard Total Stock Market ETF already in the portfolio. We also reduced the Vanguard FTSE Developed Markets ETF because we are still concerned with international exposure and would prefer to have that money in the U.S. for now. That being said, we are keeping a close eye on Europe and Japan as we think both could do well this year. Don’t be surprised if we add back to our international position later in the year as Europe, Japan, and even China have promised to keep interest rates low and money pumping into these economies as the U.S. looks to rise rates as QE is now completed. The Aggressive 5 Name Symbol Type Allocation Change Vanguard Total Stock Market Index ETF VTI Large Cap Blend 66% +1% 3 Vanguard FTSE Developed Markets ETF VEA Large Cap International 9% -1% 3 Vanguard FTSE Emerging Markets ETF VWO Emerging Markets 0% -5% 2 PowerShares QQQ ETF QQQ Large Cap Growth 10% None Vanguard REIT ETF VNQ REIT 5% None iShares Russell 2000 (NYSEARCA: IWM ) Small Cap Blend 5% +5% 1 Cash Cash 5% None Updated 1/4/2015 Add Allocation Reduce Allocation Investment Drift (No New Trades Required) Aggressive 5 Performance* Aggressive 5 SPY (S&P 500) Last Month -1.3% -0.3% QTD 4.2% 4.9% YTD – – Since Inception (10/1/2014) 4.2% 4.9% Std. Dev compared to SPY .92 1.0 Performance by ETF January 2015 Update Only 1 large change this quarter to The Aggressive 5 Portfolio which focuses on reducing our international exposure and increasing U.S. exposure. We have seen emerging markets really struggle lately because of the rising dollar and many EM countries, like Russia, are oil exporters, so the lower oil prices have weighed on their economy. We have replaced our Emerging Markets ETF with iShares Russell 2000 Index. We saw small cap companies struggle in 2014 and think that they could rebound in 2015 now that their valuations are more attractive than where they were a year ago. We believe 2015 will be a good year for the market and typically small company stocks outperform the S&P 500 in that type of environment. We didn’t make a change to the Vanguard FTSE Developed Markets ETF, but the allocation percentage dipped by 1% because of their under performance over the past quarter. As discussed above, we are keeping a close eye on Europe, Japan, and even China, as we think these economies could do well this year. *Performance is measure by Morningstar and assumes no trade commissions. Assumes trades were placed on 10/1/14 at the closing price on that day.

3 New Nontraditional Bond Funds Hit The Market

By DailyAlts Staff As fixed-income investors face asymmetrical interest-rate risk and other headwinds in 2015, nontraditional bond funds are looking more and more attractive. Such funds are often referred to as “go anywhere” funds, since they’re allowed to “go anywhere” in pursuit of their investment objectives. Three such funds were launched in the final month of 2014, as outlined below: Counterpoint Tactical Income As a new entrant into the liquid alternatives field, Counterpoint Mutual Funds launched its first mutual fund last month, the Counterpoint Tactical Income Fund. The fund has a focus on investing in high yield securities (including bonds, bank loans, floating rate bonds and debt and municipal high yield debt), but doing so when the firm’s algorithms identify trends that point to a risk-on environment. In risk-off environments, as identified by the firm’s trend-following algorithm, the fund will be allocated to less risky assets such as U.S. Treasuries and cash. The fund also has the ability to invest in derivatives to hedge against credit and interest rate exposure. The fund will pursue its tactical-income strategy by investing in mutual funds, closed-end funds, and ETFs, but also has the ability to invest directly in individual securities directly. In addition, the fund is permitted to use up to 33 1/3% leverage to pursue its objective of income and capital preservation. The fund is managed by the firm’s two founders, Michael Krause and John Koudsi, and carries a relatively high management fee of 1.25%. The fund is available in three share classes: A (MUTF: CPATX ), C (MUTF: CPCTX ), and I (MUTF: CPITX ); with respective net-expense ratios of 2.60%, 3.35%, and 2.35%. This compares to an average expense ratio of 1.30% for Morningstar’s Nontraditional Bond category. The minimum investment for A- and C-class shares is $5,000; while the minimum required for I-class shares is $100,000. For more information, download a pdf copy of the fund’s prospectus . Transamerica Unconstrained The Transamerica Unconstrained Bond Fund (ticker: TUNAX ) was launched on December 5, and like other Transamerica funds, this fund’s investment management is outsourced to an external sub-advisor. In this case, the fund’s sub-advisor is PineBridge Investments , which also manages the Transamerica Inflation Opportunities Fund (ticker: TIOAX ). The fund’s objective is to maximize returns through a combination of interest income and capital appreciation. PineBridge pursues this objective by employing an “unconstrained” style, taking long and short positions in debt instruments across sectors, geographies, capitalizations, and credit grades. PineBridge’s investment decisions are based on macroeconomic analysis that determines asset allocations, as well as specific investments within those allocations. The fund’s duration is expected to generally stay in the range of -3 years to +10 years. The fund is available in A- (TUNAX), C- (MUTF: TUNBX ), and I-class (MUTF: TUNIX ) shares, with a management fee of 0.64% and a relatively low net-expense ratios of 1.14%, 1.89%, and 0.89%, respectively. The minimum investment for A- and C-class shares is $1,000; while the minimum for I-class shares is $1 million. For more information, read the fund’s prospectus . Sentinel Unconstrained Finally, the Sentinel Unconstrained Bond Fund launched on December 23. The fund has the latitude to invest in U.S. and non-U.S. fixed income securities of any credit quality, can use shorting and derivatives and will maintain its duration in the range of -5 years to +10 years. The fund can also hold up to 20% in equity securities. Jason Doiron, portfolio manager and Head of Investments with Sentinel, will be the fund’s portfolio manager. The fund’s shares are available in A- (MUTF: SUBAX ), C- (MUTF: SUBCX ), and I-class (MUTF: SUBIX ) shares; with a 0.75% management fee and respective net-expense ratios of 1.56%, 3.56%, and 1.14%. Like the Transamerica Unconstrained Bond Fund, the minimum investment for A- and C-class shares is $1,000; while the minimum for the institutional I-class shares is $1 million. For more information, read the fund’s prospectus .

Lipper Closed-End Funds Summary: December 2014

By Tom Roseen In December the U.S. market took investors on a wild ride. Toward month-end the Dow Jones Industrial Average and the S&P 500 Index posted their thirty-eighth and fifty-second record closes for the year, respectively. A strong nonfarm payroll report at the beginning of the month pushed up U.S. equity markets, and the Dow flirted with the 18,000 mark for the first time. However, concerns about the health of the global economy the following week fueled one of the largest one-week drops in two and half years and sent the VIX to its highest level since October 17. Investors shrugged off a better-than-expected consumer sentiment report and focused on volatility in oil prices and the possibility of the global economy succumbing to deflation. Despite a Federal Reserve-fueled Santa Claus rally toward month-end, U.S. stocks finished the good year on a down note, with the Dow witnessing a triple-digit loss on the last trading day of the month. Both equity and fixed income CEFs posted negative NAV-based returns (-1.43% and -0.24% on average, respectively) for the first month in three, while market-based returns were also in the red for both equity CEFs (-2.51%) and fixed income CEFs (-0.02%). Treasury yields declined at all maturities ten-years or greater in December, with the twenty-year yield declining the most, 15 bps to 2.47% at month-end. The rising dollar and slowing growth overseas made U.S. Treasuries more attractive to foreign investors. The Treasury yield curve rose in most of the lower-dated maturities, with the three-year rising the most-22 bps to 1.10%-by month-end. The one-month yield witnessed a small decline, dropping 1 bp to 0.03%. For December the dollar once again gained against the euro (+2.69%), the pound (+0.32%), and the yen (+0.88%). Commodities prices were mixed, with near-month gold prices rising 0.73% to close the month at $1,184.10/ounce. Meanwhile, front-month crude oil prices plunged a whopping 19.60% to close the month at $53.27/barrel. That equated to a quarterly decline of 40.41% and a one-year decline of 45.87%. For the month 47% of all CEFs posted NAV-basis returns in the black, with 33% of equity CEFs and 58% of fixed income CEFs chalking up returns in the plus column. The slide in oil prices and concerns over Greece’s inability to elect a favored presidential candidate, rekindling fears of another European crisis, weighed on Lipper’s World Equity CEFs macro-classification (-2.43%), pushing it to the bottom of the equity CEF universe. On the equity side (for the fourth consecutive month) mixed-asset CEFs (-0.73%) mitigated losses better than the other macro-groups, followed by domestic equity CEFs (-1.15%). Once again, the municipal bond CEFs group (+1.13%) was the only fixed income macro-classification posting a return on the plus-side for the month, with all of its classifications experiencing returns in the black. The muni CEFs group was followed by domestic taxable bond CEFs (-1.47%) and world bond CEFs (-4.17%). For December the median discount of all CEFs widened just 19 bps to 9.28%-deeper than the 12-month moving average discount (8.55%). Equity CEFs’ median discount widened 115 bps to 9.46%, while fixed income CEFs’ median discount narrowed 53 bps to 9.13%. To read the complete Month in Closed-End Funds: December 2014 FundMarket Insight Report, which includes the month’s closed-end fund corporate events, please click here .