Tag Archives: management

Stocks And ETFs To Reflect Top Sales Growth

The Q2 earnings season is now about to end with 83.1% of the S&P 500 companies having reported already. The overall picture was not quite bright as growth for both earnings and revenues was negative in the quarter. Earnings fell 2.4% year over year while weakness in revenues was more acute with a 4.1% annual rate of decline (as per the Zacks Earning Trends issued on August, 2015). Companies found it hard to even match the already conservative top-line estimates. When everything points toward utter sluggishness, investors must be looking for specific stocks or sectors that somehow managed to outperform, snapping the downing trend. Though the entire season is all about earnings, how about looking at sales more precisely? After all, sales are harder to influence in an income statement than earnings. A company can end up scoring decent earnings by adopting cost-cutting or refinancing its credit facility which in turn lowers interest expenses. But investors should note that these activities do not represent the companies’ prime purpose – sales generation. So, it appears more analytical to assess through a company’s sales per share rather than earnings per share. This is truer given the fact that it is harder for a company to shape up revenue figures by some other measure. MarketWatch recently highlighted 10 S&P 500 companies that exhibited the speediest sales growth in the last reported quarter. To do so, the author calculated sales per share of the latest quarter and then measured its rate of growth from the sales per share in the year-ago quarter. While this approach surely presents investors a set of stocks to keep a close eye on, they can also consider the ETF or basket approach for risk minimization purpose. For that, we highlight ETFs considerably invested in those stocks. Housing D.R. Horton (NYSE: DHI ) , one of the biggest and well-known homebuilders in the nation, topped the list provided by MarketWatch having recorded 37% growth in sales per share. This Zacks Rank #2 (Buy) stock has Growth and Momentum Style Score of ‘A’. On the other hand, Lennar Corporation (NYSE: LEN ) a Zacks Rank #1 (Strong Buy) firm in the Residential Construction space, recorded 30% sales per share growth in its most recent quarter and occupied the sixth spot. Both stocks have considerable exposure of at least 11% in the iShares U.S. Home Construction ETF (NYSEARCA: ITB ) . Another housing ETF SPDR Homebuilders ETF (NYSEARCA: XHB ) also invests over 3% in each stock. In any case, the housing sector shaped up well in recent months. The Key constituents’ sturdy sales performance makes these funds worth noting. Both funds have a Zacks ETF Rank #3 (Hold). Health Care Who does not know about the robust health of the health care stocks and funds? Merger and acquisition frenzy, encouraging industry fundamentals and promising new drugs sent the sector on cloud nine these days. Quite expectedly, stocks from health care sectors will hit the list of ‘fastest sales growth’. The Zacks Rank #1 Gilead Sciences (NASDAQ: GILD ) put up 36% sales growth. The stock, with Growth and Value Style Scores of ‘B’ has hefty shares in the Market Vectors Biotech ETF (NYSEARCA: BBH ) and the iShares Nasdaq Biotechnology ETF (NASDAQ: IBB ) with about 16% and 8%, respectively. Though biotech stocks and ETFs recently fell out of investors’ favor possibly on overvaluation concerns, the space should bounce back after the correction. BBH has a Zacks ETF Rank #1 while IBB carries a Zacks ETF Rank #2. Technology Though the tech sector was on a roller-coaster ride this earnings season and some major tech companies were badly beaten down post earnings, much of the downside was largely the result of lofty expectations. At least for the tech monster Apple (NASDAQ: AAPL ) , the scenario looked like this. The company had some issues with some of its key products and their sales momentum, but still saw sales per share growth of 36%. This Zacks Rank #2 (Buy) stock has compelling indicators of Growth and Value scores of ‘A’ and Momentum score of ‘B’. Investors can easily play this stock via the iShares Dow Jones US Technology ETF (NYSEARCA: IYW ) , the Technology Select Sector SPDR ETF (NYSEARCA: XLK ) and the Vanguard Information Technology ETF (NYSEARCA: VGT ) . All three are Buy rated. Link to the original post on Zacks.com
Canaries In The Investment Mine Have Stopped Serenading

In an effort to boost the U.S. economy, the central bank of the United States has used higher stock prices as a weapon of perceived wealth creation. Here’s the downside. When you implicitly and explicitly suggest that rates will remain lower for longer, people begin to count on risky assets being safer than they are. With all four of the classic canaries unable to serenade, the historical probability of a sharp correction for the broader U.S. market increases significantly. Eleven months ago, I talked about four classic canaries in the investment mines: (1) commodities, (2) high yield bonds, (3) small-cap stocks, (4) emerging market stocks. I explained that when all four of those canaries stop singing, riskier ETFs tend to break down. Indeed, in September of 2014, commodities were tanking, high-yield bonds were plunging, small-cap stocks were faltering and emerging market stocks were plummeting. The canaries were losing their voices. Not surprisingly, the broader U.S. markets eventually followed suit in rather dramatic fashion. In fact, everyone’s favorite large-cap benchmark (S&P 500) had nearly pulled back 10% from a record high. Then came the 16th of October. Stocks had coughed up yet another 1% through mid-day. With the broad-market benchmark pushing the 10% correction level, the president of the St. Louis Fed, James Bullard, suggested that his colleagues at the U.S. Federal Reserve could always rethink the use of additional bond buying with an extension of quantitative easing (QE). And at that time, Bullard talked about worldwide economic uncertainty being a reason for continuing “QE3.” Here’s what happened next: Today, the “Bullard Bounce” still reverberates off the walls and ceilings of the New York Stock Exchange. Why? Investors believe the Fed is willing to do whatever it takes to preserve higher stock prices. Keep in mind, in an effort to boost the U.S. economy, the central bank of the United States has used higher stock prices as a weapon of perceived wealth creation. When you pressure investors to take on risks that they would not normally have taken by pushing interest rates to ‘rarely-before-seen’ lows – and when you entice consumers to finance gratification through credit rather than through savings – asset prices rise precipitously. Higher home prices and higher stock prices make people feel wealthier. Here’s the downside. When you implicitly and explicitly suggest that rates will remain lower for longer, people begin to count on risky assets being safer than they are; similarly, the size of debts can become some so large that those who trusted the policy makers lose the ability to service the debt (let alone pay it back) when borrowing costs go up. Now let us tie together last year’s four classic canaries with the subsequent Bullard bounce and today’s financial markets. The PowerShares DB Commodity Index Tracking ETF (NYSEARCA: DBC ) has accelerated its decline since July and currently seeks depths that haven’t been seen since the heart of the Great Recession. That’s one canary that cannot sing. Meanwhile, high yield bonds via the SPDR Barclays Capital High Yield Bond ETF (NYSEARCA: JNK ) is accelerating its decline that began in June. Canary #2 has a bone its throat. Circumstances are not much better for small-cap stocks and emerging market stocks. The iShares Russell 2000 ETF (NYSEARCA: IWM ) sports a P/E of 20.6 according to Morningstar. It has fallen 6.3% from its late June pinnacle and sits slightly below its long-term 200-day moving average. In another words, Canary Numero 3 is having difficulty vocalizing. The Vanguard FTSE Emerging Markets ETF (NYSEARCA: VWO ) may provide value-du-jour with is P/E of 14, yet China’s recent currency devaluation and Russia’s oil price losses make it difficult for investors to see a forest for the trees. After all, VWO is sitting near 52-week lows and has been in a steep downtrend since May. (The fourth of the four canaries isn’t singing.) With all four of the classic canaries unable to serenade, the historical probability of a sharp correction for the broader U.S. market increases significantly. What’s more, just like the September-October pullback of 2014, market internals have been deteriorating at a noteworthy pace, whether one is looking at waning breadth of bullish stock participation or widening credit spreads between investment grade and higher yielding corporates/junk corporates. It follows that a sell-off not unlike the one that occurred in September-October of 2014 is extremely likely to transpire here in 2015. However, there are several differences this time around. For one thing, revenues have declined for two consecutive quarters, making valuations even more questionable than in 2014. In a similar vein, earnings have gone flat. Historically, stocks tend to fade when corporations are less capable of producing top-line and bottom-line results (as opposed to merely beating the analyst estimates). What’s more, this time around, there’s less certainty of the Federal Reserve defending stocks at the 10% correction level. Granted, Bullard employed a “do whatever it takes” strategy to send stocks skyrocketing last year by bringing up global economic uncertainty. It would be extremely easy for the Fed to use an excuse that economic weakness in Europe, Asia, Australia, Latin America – pretty much everywhere – requires that they tighten at a sloth’s pace. For example, they raise rates at one-eight of a point rather than one-quarter, or they execute a one-n-done quarter-point for 3-6 months. That would likely encourage risk assets to get back on track. Nevertheless, until there is clarity on Fed policy, all of the signs point to “risk-off” outperforming “risk-on.” Downside risks remain elevated until the Federal Reserve shines light on its game plan going forward. Even if the path for tightening is described as ultra-slow and measured, investors will need to weigh just how much the higher costs of borrowing might adversely impact the cost of debt servicing for corporations; that is, we may see further erosion of profitability from an earnings picture that is already flat. People, companies as well as countries tend to forget that debt is still debt. If the overall cost of servicing debt is lowered through rate games, and the debts are increased because families/corporations/nations are taking the worm on the fish hook, it does not mean that the hook itself won’t cause severe damage or death. Again, non-financial corporations are more leveraged at 37% than they were in 2007 at 34%. Higher borrowing costs from the U.S. Federal Reserve? That’s going to be more than an inconvenient challenge. Disclosure: Gary Gordon, MS, CFP is the president of Pacific Park Financial, Inc., a Registered Investment Adviser with the SEC. Gary Gordon, Pacific Park Financial, Inc, and/or its clients may hold positions in the ETFs, mutual funds, and/or any investment asset mentioned above. The commentary does not constitute individualized investment advice. The opinions offered herein are not personalized recommendations to buy, sell or hold securities. At times, issuers of exchange-traded products compensate Pacific Park Financial, Inc. or its subsidiaries for advertising at the ETF Expert web site. ETF Expert content is created independently of any advertising relationships.

Low P/E Stock Of The Day No. 15: The AES Corporation

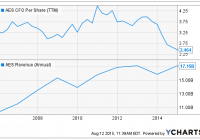
Summary Shares are currently trading at a P/E of 9.7x. Business are very stable due to contracts and low competition. However, the company has a poor record of asset allocation. In this series, I will select a low P/E stock to analyze. I define low P/E as anywhere from 5x to 10x, as any lower and we may be looking at special situations. Read the last edition here ! The AES Corporation (NYSE: AES ) is a diversified utility company whose operation spans across the globe. It has facilities in the U.S., Andes, Brazil, MCAC (Mexico, Central America, and Caribbean), Europe, and Asia. The company generates income from two lines of business, power generation and electricity distribution, this allows the company to capture profits across the value chain. Despite the company’s comprehensive offering, the stock meandered for years, and is currently trading at a TTM P/E of 9.7x. For an established and stable business, this is no doubt a low multiple. So is there a good justification? Stable Businesses The company’s power generation business currently sources from a variety of fuel types. Around 35% of the company’s plants are fueled by gas, 30% by coal, 29% by renewables, and 5% by oil, diesel, or petroleum coke. Evidently, the majority of the electricity is generated from environmentally friendly resources (natural gas and renewables), this is important as the governments around the world are imposing increasingly stringent environmental regulations. The power generation segment also operates on contracts. Although they are not decades long, the company’s average contract term is around 7 years, so they do provide stability in the medium term. The utility business primarily sells electricity directly to consumers (the power generation segment sells to corporate customers or other utility companies). This means that demand is not correlated to the general well-being of the economy, as consumers will use electricity no matter what. In addition, the company’s utility subsidiaries are often the sole distributors in their respective areas. This means that there is very little direct competition and it is unlikely that new entrants would want to compete with an established business that has already invested an enormous amount of capital on infrastructure. This provides a sustainable competitive advantage for the utility business. What I Don’t Like Despite revenue growth, the company has not been able to maintain the same level of profitability. This means that the management has not been keen on picking the right assets to invest in. In the graph above we can visualize the impact (or lack thereof) of growth. Over 10 years, revenue has risen 67% from $10.25 billion in 2005 to $17.15 billion in 2014. However, operating cash flow per share did not grow at all. This means that growth has not delivered any value to shareholders. In the chart below, we can see that the company has spent significant cash on various investments, which corresponds to the revenue growth. Without a corresponding rise in operating cash flow, I believe that the management is incapable of conducting proper asset allocation. Despite having a stable business, this alone makes me believe that the current P/E ratio is justified. Unless we see a management shakeup, I do not think that The AES Corporation would be a good investment. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.