Tag Archives: investing ideas

ETFs For Your Core Domestic Stocks Portfolio: 3 Worthy Competitors
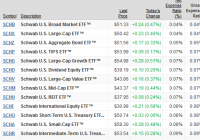
Summary Every ETF investor needs to consider what holdings will form the very core of their portfolio. For the portion relating to domestic stocks, in a previous article I featured Vanguard’s Total Stock Market ETF. In this article, I will examine two other worthy competitors, and analyze how they stack up against VTI. Every investor desirous of developing an ETF-based portfolio does well to start by selecting a few core holdings. In my view, such holdings should offer great diversification along with a rock-bottom cost structure. In a previous article for Seeking Alpha, I featured the Vanguard Total Stock Market ETF (NYSEARCA: VTI ). I concluded that one should seriously consider VTI as a core holding for the portion of your portfolio devoted to domestic stocks. However, there are several worthy competitors in the marketplace. And, they may be even more worthy if your brokerage offers commission-free trading in these ETFs; particularly if one of your goals is to invest regularly and in small increments. In this article, we will examine two such competitors; the Schwab U.S. Broad Market ETF (NYSEARCA: SCHB ) and the iShares Core S&P Total U.S. Stock Market ETF (NYSEARCA: ITOT ). We will compare their structure, expense ratio and other features against VTI, and see how they stack up. Schwab U.S. Broad Market ETF While the history of Charles Schwab (NYSE: SCHW ) traces back over 40 years, the firm is a fairly recent entrant to the ETF market, really getting into the area in a big way in 2009. However, once it committed, it quickly became a formidable competitor. The firm now sports no less than 13 ETFs featuring an expense ratio of .10% or less, as shown here: Heading the list is SCHB, with a market-leading .04% expense ratio. SCHB is based on the Dow Jones Broad Stock Market Index , which tracks the 2,500 largest publicly traded U.S. companies for which pricing information is readily available. This index is a subset of the Dow Jones U.S. Total Stock Market Index, but excludes companies defined as micro-caps. This index has a median market cap of $1.9 billion. Currently, there are exactly 2,506 stocks in this index. If you look at the informational table I include later in this article, you will note that SCHB only contains 2,020 stocks. The answer to why this is the case actually offers a helpful insight into how ETFs, particularly those with incredibly low expense ratios, are able to function. Here is the explanation given in the SCHB prospectus : Because it may not be possible or practicable to purchase all of the stocks in the index, the Adviser seeks to track the total return of the index by using statistical sampling techniques. These techniques involve investing in a limited number of index securities which, when taken together, are expected to perform similarly to the index as a whole. Look at that phrase “possible or practicable .” In other words, they are explaining that the trading costs involved in attempting to purchase every security in the index would lead to a greater tracking error (or divergence from the index) than their actual practice of sampling the index. In many ways, SCHB mirrors VTI quite closely. As of the date I researched this article, it has a 1.85% distribution yield, against 1.88% for VTI. The weighting of the Top 10 holdings in each fund is also virtually identical. The fund is significantly smaller than VTI, with “only” $5.0 billion in Assets Under Management (AUM) as compared to $55.6 billion for VTI. You will see a small reflection of this in average spread (see definition below) of .03% vs. VTI’s industry-low .01%. This simply reflects the massive daily volume that trades in VTI due to its size. iShares Core S&P Total U.S. Stock Market ETF Our second competitor is from the iShares family of ETFs offered by BlackRock, Inc (NYSE: BLK ). BlackRock is another formidable competitor in the sphere of low-cost ETFs, with 19 ETFs featuring an expense ratio of .10% or less . Several of these are Bond ETFs with specific maturity dates so, for the sake of brevity, I show here the 5 ETFs with an expense ratio of .09% or less: (click to enlarge) ITOT is based on the S&P Composite 1500 Index . This index combines the legendary S&P 500, the S&P MidCap 400, and the S&P SmallCap 600 indexes, and covers some 90% of the total U.S. market capitalization. It covers companies with market capitalization of approximately $350 million or greater, with a median market cap of $3.3 billion. You may recall that SCHB’s median market cap is $1.9 billion, signifying that it contains a larger percentage of small-caps than does ITOT. NOTE: If you are interested in a nice visual representation of the scope of the various indexes, I found a wonderful graphic on the bogleheads website. ITOT has a 1.80% distribution yield, against 1.88% for VTI. The weighting of the Top 10 holdings is slightly more concentrated than VTI, at 15.12% vs. 14.00%. The fund is the smallest of our 3 competitors, with $2.4 billion in Assets Under Management (AUM). As a result, the average spread (see definition below) is .05% compared to .03% for SCHB and .01% for VTI. Key Comparative Information I have prepared the tables below as a quick visual comparative reference to help you evaluate the three ETFs side-by-side. First, some key high-level information: VTI, SCHB, and ITOT: Key Information VTI SCHB ITOT Assets Under Management (AUM) $55.6 Billion $5.0 Billion $2.4 Billion Index Tracked CRSP Total U.S. Market Index Dow Jones Broad Stock Market Index S&P Composite 1500 Index Number of Holdings 3,824 2,020 1,503 Weighting of Top-10 Holdings 14.00% 13.80% 15.12% Distribution Yield 1.88% 1.85% 1.80% Expense Ratio .05% .04% .07% Average Spread .01% .03% .05% Notes on terms that may be unclear: Distribution Yield refers to the ratio of distributions paid by the fund for the past 12 months divided by the Net Asset Value. Average Spread refers to the average price difference between the price buyers were willing to pay and sellers were willing to sell, averaged over the latest 45 days. Next, the sector breakdown: VTI, SCHB, and ITOT: Sector Breakdown VTI SCHB ITOT Financials 18.90% 17.90% 17.47% Technology 16.10% 18.70% 19.01% Health Care 14.00% 14.80% 14.92% Consumer Discretionary 13.80% 13.70% 13.01% Industrials 12.40% 10.50% 10.68% Consumer Staples 9.70% 8.40% 8.92% Energy 7.30% 6.80% 7.26% Utilities 3.00% 3.00% 3.04% Materials 2.80% 3.40% 3.44% Telecommunications 2.00% 2.00% 2.02% Other 0.00% 0.80% 0.23% TOTAL 100.0% 100.0% 100.0% Summary All three ETFs are worthy competitors. If you look at this YTD chart, you will see that VTI has a slight lead, and all three have outperformed the S&P 500. VTI data by YCharts If you look at this 5-year chart as a longer-term comparison, you will see that SCHB actually has a very slight lead over that time span, again with all three outperforming the S&P 500. VTI data by YCharts Setting aside the question of whether you can trade a particular ETF commission-free, here is my rating: VTI : In my mind, it was a very close battle between VTI and SCHB. Certainly, SCHB’s stunning .04% expense ratio is not to be ignored. Further, SCHB has slightly edged out VTI over the past 5 years. However, VTI’s slightly higher distribution ratio, huge size, extremely competitive .05% expense ratio, broader market coverage and recent outperformance nudge it to the #1 spot in my evaluation. SCHB : As I mention, this was a very close call. I think Schwab has done an incredible job putting together a world-class ETF for this category. I find it of no small note that SCHB has slightly edged out VTI over the past 5 years and its low expense ratio will doubtless make it extremely competitive as time moves forward. ITOT : Well, in a comparison of 3, one has to come out third. In this extremely tough head-to-head showdown, ITOT’s smaller size, .07% expense ratio and slight comparative underperformance weigh against it. On the other hand, its slight tilt toward large-caps might lower your risk in the event of a market downturn. I must say, however, that the question of which ETF you can trade commission-free may be the ultimate decider for you. Particularly will this come into play if regular, incremental, investments form a large part of your plan. Happy investing! Disclosure: I am/we are long VTI, ITOT. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article. Additional disclosure: I am not a registered investment advisor or broker/dealer. Readers are advised that the material contained herein should be used solely for informational purposes, and to consult with their personal tax or financial advisors as to its applicability to their circumstances. Investing involves risk, including the loss of principal.

HIX: Smaller Distributions And History Suggest A Long Life Ahead

The Western Asset High Income Fund II has been trimming its distributions for years. That’s a problem for income-hungry investors. But distribution cuts and a historically stable NAV suggest HIX will live to fight another day. If you are after a reliable stream of income that can you use to live, don’t buy the Western Asset High Income Fund II (NYSE: HIX ). If you are looking for a decent high-yield fund, however, take a look. Those two statements may seem at odds with each other, but they aren’t. Here’s why… A little more than generic At its core, HIX is a high-yield bond fund. As its name implies, Western Asset Management is calling the shots and, over the long haul, its done a solid job. For example, the fund’s trailing annualized 15-year total return through June based on net asset value, or NAV, is roughly 9.5%. That includes the reinvestment of distributions. Compare that to the Vanguard High Yield Corporate Fund’s (MUTF: VWEHX ) annualized 6.3% over that span and HIX looks like a solid high yield option. To be fair, HIX’s standard deviation over that span was 14 compared to Vanguard’s 8. So HIX achieved the higher return by taking on more risk. So for risk averse investors, a more conservative high-yield fund might be a better choice. But if you can stomach the risk, HIX’s performance has been good over the long term. Part of the reason for the added volatility is that HIX makes use of leverage to enhance returns. Recently leverage stood at around 25% of assets. This works great when rates are low because the fund can easily create a carry trade, borrowing for less than it earns and passing the difference on to shareholders. However, leverage also increases the impact of price movements. That’s a great thing in up markets because it enhances returns, but a bad thing in down markets because losses get exacerbated. The other issue to note at HIX on the risk front is that it has a “strategic” allocation to emerging market debt. It’s only around 8% or so of assets, but emerging market debt can be more volatile than other bonds. On the one hand it provides diversification, on the other it can be a drag when emerging markets are struggling. But, at less than 10% of assets recently, it won’t be the driving force at the fund right now. It’s just something to keep in mind, especially since management has the leeway to increase that exposure to as much as 35% of assets. So, on the whole, HIX is a solid long-term performer for those willing to take on a little more risk. That said, the last year has been pretty rough. For comparison, over the trailing 12 months through June, HIX is down 4.5% or so and Vanguard High Yield Corporate is up around 1.5%. Like so many high-yield funds, energy was a big issue in HIX’s poor showing. Leverage, of course, didn’t help either. The impact of this rough spell is worth noting, however. Between April of 2014 and April of 2015, the fund’s fiscal year ends in April, HIX’s net asset value fell from $9.47 a share to $8.57. More recently it’s stood at around $8.25. That’s clearly the wrong direction. But HIX has been here before. For example, in fiscal 2012 the fund’s NAV declined from $9.57 a share $8.86 only to almost completely recover in fiscal 2013. Based on the fund’s long-term performance, the current downdraft is something that it will likely eventually recover from. The income issue Which brings us to the income issue. The fund’s distribution has been shrinking steadily since 2010 when it was $0.09 a month. Today the distribution rounds to $0.07 a month. Not a huge decline on an absolute basis, but a notable one when looked at percentage wise. I would expect the downward trend to continue, so income focused investors looking to replace a paycheck might want to look elsewhere. But I don’t think the distribution cuts are inherently a bad thing. Rates are at historic lows, so older debt that’s matured (or sold) is replaced with the lower-yielding fare in the current market. Thus, the income the portfolio generates is naturally declining. The distribution cuts are simply a part of that. More importantly, the cuts show that management is willing to take the lumps that come along with larger market shifts to keep the portfolio from self liquidating over time. A lot of closed end funds try to delay cuts until there is no choice but to cut, which often leads to more drastic distribution declines. And if income isn’t your focus, the willingness to slowly trim distributions to protect capital is probably the more preferable option. It’s the income thing So, for investors, I think the biggest issue right now is the income question. If you want a steady distribution, HIX isn’t likely to provide it right now. If you are looking to buy a high-yield fund because you want some exposure to the asset class, however, HIX is worth a look. Management is dealing with a rough patch right now, but it’s done so before successfully and it is willing to trim distributions to ensure that it lives to fight another day. That said, the fund isn’t cheap to own, with an expense ratio of around 1.5%. That’s not outlandishly high, but it is clearly more than you’d pay for an exchange traded fund or an open-end mutual fund. Leverage costs are a part of that. But you’re not likely to find an around 11% yield from a high-yield ETF or open-end fund (noting, of course, that HIX’s distributions are likely to shrink further). And HIX is trading at a discount to NAV of around 8%, which is fairly steep for this fund. In fact, the average was a premium of around 1% over the trailing three years. So, for those looking to trade around premiums and discounts, HIX could be worth a deep dive right now. Just don’t expect the current distribution level to hold. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.

5 Portfolio Moves For The Second Half

After a relatively calm few months, market volatility is back. In recent weeks, stocks have swung between ups and downs, as investors have attempted to digest the latest news out of Greece , the recent bear market in China and the growing likelihood that the Federal Reserve (Fed) will hold off on raising rates until after its September meeting. Some of this shouldn’t come as a surprise. At BlackRock, we have long been saying that the second half was likely to be characterized by more volatility, given increasing investor attention on the Fed’s next move. We also have long viewed China’s market as expensive. However, not everything has played to script, like some of the twists in Greece’s debt crisis and the possible delay of a Fed rate hike. That said, the big-picture economic themes we discussed in the beginning of the year still appear to be in place: slow but steady growth, low inflation and low rates. Even recent events in Greece and China aren’t likely to have a longer-term impact on the global economy or markets. Against this economic backdrop, we’re sticking with our basic market views. So, to help prepare your portfolio for the second half, investors can consider these five portfolio moves, as I write in the Mid-Year Update to The BlackRock List: What to Know and What to Do in 2015 . Favor stocks over bonds Stocks in general still look more attractively valued than bonds, but certain stock segments offer more value than others. We like international stocks over U.S. ones (more on that in the next bullet point). Meanwhile, within the U.S., we’re cautious on segments that will likely be most affected when interest rates go up, such as utilities. Greater value can be found in sectors positioned to benefit from economic growth, such as technology and financials. Consider more international equity exposure With the U.S. in the sixth year of a bull market, better value exists overseas, particularly in Europe and Japan. While it’s true that Europe is no longer cheap and faces political challenges, contagion from the situation in Greece is unlikely, and we still expect European equities to notch decent performance relative to pricier U.S. stocks. Europe and Japan should also continue to benefit from market-friendly central bank easing, while the U.S. is poised to raise rates soon. Within bonds, favor credit over duration. While bonds remain expensive, it’s important to have some exposure to fixed income. Given that rate volatility will likely remain elevated in coming months, investors may want to look to the high yield sector, which is typically less sensitive to rate movements than other fixed income sectors. We also like tax-exempt municipal bonds, which currently offer attractive yields. Look for tactical opportunities within fixed income Income seekers must keep in mind that rates around most of the world will remain low for some time despite any Fed action, so flexibility and selectivity are critical in fixed income asset allocation. Consider alternatives, but remain cautious on commodities Finally, in a slow-growth world where many traditional assets look pricey, you may want to consider casting a wider net toward alternative investments in an effort to optimize your portfolio’s results. Nontraditional asset classes such as infrastructure or real estate may be worth considering. Commodities, on the other hand, are likely to remain challenged, particularly if real rates continue to rise. The bottom line: As volatility continues, resist the temptation to abandon the markets. A better strategy for long-term investors would typically be to stay the course, assuming your portfolio is aligned properly. Source: BlackRock Original Post