Tag Archives: function

Cybersecurity: The One ETF You Need To Know For 2015

The Sony hack and latest credit card breaches show demand for the market. The ETF’s top ten holdings are relative small companies with eight being worth less than $2 billion. The ETF is the only pure play in the sector and should see strong demand as the go to product for the market. In November, a new ETF hit the market that for the first time offered investors a way to get a basket of stocks in one of the hottest sectors. PureFunds launched the ISE Cyber Security ETF (NYSEARCA: HACK ), which remains the first and only true cybersecurity ETF for investors. With all of the talk about the Sony (NYSE: SNE ) hacking and what it means for companies, this fund is likely to come out a winner for many years as trends shift towards securing the world’s data. According to this interview , the inspiration for the fund was twofold. The company wanted to showcase the potential of the cyber security industry and also saw the lack of an investment vehicle in the sector. When asked about the non-direct competing ETFs that are in the technology sector, the company pointed something very interesting out. The larger PowerShares QQQ Trust ETF (NASDAQ: QQQ ) and Technology Select Sector SPDR ETF (NYSEARCA: XLK ) have less than 5% overlap with ISE Cyber Security. Here is a look at the top ten holdings as of December 20th: Imperva (NYSE: IMPV ): 8.4% Vasco Data (NASDAQ: VDSI ): 8.3% Infoblox (NYSE: BLOX ): 5.9% Palo Alto Networks (NYSE: PANW ): 5.8% Qualys (NASDAQ: QLYS ): 5.8% IntraLinks (NYSE: IL ): 5.1% Proofpoint (NASDAQ: PFPT ): 5.1% Radware (NASDAQ: RDWR ): 4.8% Fortinet (NASDAQ: FTNT ): 4.7% Barracuda Networks (NYSE: CUDA ): 4.7% In total, the fund has 26 holdings. Most of the top ten holdings aren’t immediately recognizable. In fact, two of the bigger names in cyber security, Symantec (NASDAQ: SYMC ) and FireEye (NASDAQ: FEYE ), make up 4.5% and 3.4% of the ETF respectively. It is worth noting that the average market capitalization of the top ten holdings is $2.55 billion. This figure comes with two of the funds trading less than $1 billion and eight of the top ten holdings having market capitalizations under $2 billion (Fortinet $5.1 billion, Palo Alto Networks $10.1 billion). I think this represents a huge opportunity as these companies can grow fast in this market and offer sizable returns. Cybersecurity is a huge market and is continuing to grow. The Sony hack that left the paper using pen and paper has shown how vulnerable companies are and also what the cleanup process can look like. The FBI also said that 90% of companies are vulnerable and could have been attacked just like Sony was. Sony recently hired Mandiant Forensics, a unit of FireEye to help with the cleanup. Mandiant is an incident response firm that helps victims of breaches by cleaning up and restoring. Mandiant has helped with some of the biggest security breaches, including the infamous 2013 Target (NYSE: TGT ) hack. FireEye makes up 3.4% of the ETF, but shows exactly what kind of growth the industry is seeing. Staples (NASDAQ: SPLS ) recently estimated that 1.16 million customers may have been impacted by a credit card hack at its stores. This follows up a two-year period that has seen Home Depot (NYSE: HD ), Target, Kmart, Dairy Queen, and JPMorgan (NYSE: JPM ) in the news for security breaches. As the publicity spreads on these issues and also the claims filed by victims, companies are forced to upgrade security and pay the companies in this portfolio. Investing in a cybersecurity ETF means you win as companies protect themselves. More hacks may make the investments worth more, but investors should rest assured that these companies don’t need hacks to survive, but rather companies to use their prevention software and intelligence to combat potential attacks. One situation investors and companies should be watching is the Regin Trojan that Symantec brought to the public’s attention recently. The top tier espionage tool is being used against governments, infrastructure, businesses, researchers, and individuals. Since 2008, Regin has been using a “degree of technical competence rarely seen.” These are scary times for cybersecurity as data continues to seem unsafe and readily accessible by those who want to find it. The ETF has an expense ratio of 0.75%. The fund has $66 million in assets currently, but I expect that to grow as more information and publicity comes out for this one of a kind ETF. Average volume is 153,000 shares a day. As we head into 2015, I have to recommend investors take a good hard look at this ETF. Despite trading at its highest point since its short inception, I believe the fund has much more to offer. This is a red hot sector that is going to see billions of dollars incoming from large and small companies alike. The company has a good basket of stocks and with lower market capitalization stocks up top, may grow faster than investors are expecting.
Stock Picking Grades For Small Cap Value Style Fund Managers

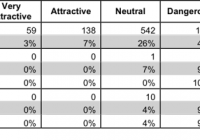
Summary In this report, we focus on how much Small Cap Value style fund managers allocate to the best stocks compared to how many good stocks are available in the style. Many ETFs and mutual fund managers do a poor job identifying quality stocks for their funds. These funds are not worth owning at any cost. The emphasis that traditional research places on low costs is a positive for investors, but low fees alone do not drive performance. Only good holdings can. This report shows how well Small Cap Value ETFs and mutual fund managers pick stocks. We juxtapose our Portfolio Management Rating on funds, which grades managers based on the quality of the stocks they choose, with the number of good stocks available in the style. This analysis shows whether or not ETF providers and mutual fund managers deserve their fees. For example, if a fund has a poor Portfolio Management Rating in a style where there are lots of good stocks, that fund does not deserve the fees it charges, and investors are much better off putting money in a passively-managed fund or investing directly in the style’s good stocks. On the other hand, if a fund has a good Portfolio Management Rating in a style where there are lots of bad stocks, then investors should put money in that fund, assuming the fund’s costs are competitive . Figure 1 compares the number of good stocks in the Small Cap Value style to the number of good funds. 197 out of the 2131 stocks (over 10% of the market value) in Small Cap Value ETFs and mutual funds get an Attractive-or-better rating. Zero out 15 Small Cap Value ETFs allocate enough to quality stocks to earn an Attractive-or-better Portfolio Management Rating. Mutual fund managers have not fared any better. Zero out of 273 Small Cap Value mutual funds allocate enough of their assets to quality stocks to earn an Attractive-or better Portfolio Management Rating. ETF providers and mutual fund managers need to do a better job to justify their fees. With no high quality funds available, 100% of investor assets in Small Cap Value ETFs are invested in ETFs with Dangerous Portfolio Management Ratings. Investors have almost no choice in this style with only one ETF even receiving better than a Dangerous Portfolio Management Rating. The picture is no better for mutual fund investors as 96% of investor assets are allocated to mutual funds with Dangerous-or-worse Portfolio Management Ratings. Figure 1: Small Cap Value Style: Comparing Quality of Stock Picking to Quality of Stocks Available (click to enlarge) Sources: New Constructs, LLC and company filings The First Trust Mid Cap Value AlphaDEX ETF (NYSEARCA: FNK ) has the highest Portfolio Management Rating of all Small Cap Value ETFs and earns my Neutral Portfolio Management Rating. The Prudential Small-Cap Value Fund (MUTF: PZVAX ) has the highest Portfolio Management Rating of all Small Cap Value mutual funds and earns my Neutral Portfolio Management Rating. The iShares Russell 2000 Value ETF (NYSEARCA: IWN ) has the lowest Portfolio Management Rating of all Small Cap Value ETFs and earns my Dangerous Portfolio Management Rating. The Aston/River Road Independent Value Fund (MUTF: ARVIX ) has the lowest Portfolio Management Rating of all Small Cap Value mutual funds and earns my Very Dangerous Portfolio Management Rating. Schweitzer-Mauduit International (NYSE: SWM ) is one of my favorite stocks held by Small Cap Value ETFs and mutual funds and earns my Attractive rating. Over the past ten years, Schweitzer has grown after-tax profit ( NOPAT ) by 13% compounded annually. Schweitzer also currently earns a top-quintile return on invested capital ( ROIC ) of 16%. Despite this outstanding profit growth, Schweitzer remains undervalued. At its current price of ~$44/share, SWM has a price to economic book value ( PEBV ) ratio of 1.1. This ratio implies that the market expects Schweitzer to grow NOPAT by only 10% from its current levels over the remainder of its corporate life. This expectation is rather low given the double-digit NOPAT growth achieved for the past decade. Unit Corporation (NYSE: UNT ) is one of my least favorite stocks held by Small Cap Value ETFs and mutual funds and earns my Very Dangerous rating. Over the past eight years, Unit’s NOPAT has declined by 1% compounded annually. The company currently earns a bottom-quintile ROIC of 5%, down from 19% in 2005. Unit has generated positive economic earnings in just one of the last 16 years covered by our model. Despite its lack of profit growth, UNT is rather overvalued. To justify its current price of ~$46, UNT must grow NOPAT by 9% compounded annually for the next 11 years. Such a high profit growth expectation seems overly optimistic given this company’s track record of declining profits. Kyle Guske II contributed to this report. Disclosure: David Trainer and Kyle Guske II receive no compensation to write about any specific stock, style, or theme.

Deutsche Liquid Alts Outlook: Overweight Long/Short Equity

While global equities lost ground in the third quarter of 2014, liquid alternatives consolidated their gains from the first half of the year. Discretionary macro and trend-following strategies were among the top performers, according to a briefing paper published by Deutsche Asset & Wealth Management (Deutsche), as diverging central bank policies provided opportunities for alternative strategists in the fixed-income and currency markets. In the paper, Deutsche offers a brief review of each of the following alternative strategies and current recommendations for portfolio positioning of each strategy: Long/short equity Market neutral equity Discretionary macro CTAs Credit strategies Event-driven Distressed What follows is a summary of Deutsche’s analysis of each alternative strategy. Long/Short Equity The choppiness of the broad stock market in Q3 – “risk-off” in July; “risk-on” in August; and mixed in September – put the focus on stock picking, the long/short equity specialty, rather than trend following or asset allocation. U.S. stock pickers in particular found “the operating environment more supportive than in European markets,” according to Deutsche. Market Neutral Market-neutral equity strategies underperformed in the second quarter but bounced back in the third, with the HFRX Equity Market Neutral Index posting its second-largest gain in more than three years in August. According to Deutsche, “gains occurred across factor-based models as well as fundamental and trading strategies.” As the broad bull market in stocks led to a flight of assets from market-neutral strategies, it became easier for market-neutral strategists, less constrained by size, to find better opportunities. What’s more, the flow of funds out of market-neutral has led to the survival of the fittest managers, improving their prospects for Q4 and 2015. Discretionary Macro Deutsche says the third quarter of 2014 was a “defining period” for discretionary macro strategies, with the class advancing in each of the quarter’s three calendar months. Positive performance was delivered by substantial bets on the dollar vs. the euro, as well as directional positioning in long bonds, and relative-value equity trades. Returns over the quarter were broadly based across asset classes. Commodity Trading Advisors CTAs posted gains in the third quarter, despite the continued decline in most commodities markets. The HFRX Systematic Diversified CTA Index added 1.55% in August, thanks to currency trends, rising U.S. bond prices, and further advances in the U.S. stock market. Credit Strategies Credit-strategy managers that were net-short high-yield bonds or had balanced books in the third quarter were rewarded, according to Deutsche. The bearish turn for high yield was caused by the “valuations in this sector moving ahead of fundamentals.” Relative-value credit strategies benefitted from corporations’ continued and elevated levels of refinancing. Event-Driven Kiboshed tax-inversion mergers weighted on event-driven strategies in the third quarter, as Congress passed laws discouraging the tax-reduction strategy that had been a boon to M&A activity. Two unrelated deals also fell through in early August: Sprint’s proposed takeover of T-Mobile, and 21 st Century Fox’s proposed acquisition of Time Warner. Distressed Investors in distressed assets had “nowhere to go” in the third quarter, according to Deutsche. The HFRX Distressed Index gave back gains over the period “as spreads backed up across many segments of the market.” Conclusion Deutsche concludes its briefing with a list of nine expectations, as well as allocations to strategies ranging from “overweight” to “underweight” for each alternative class. Long/short equity, market-neutral equity, and event-driven are given “overweight” ratings; Discretionary macro and credit strategies are given “overweight/neutral” ratings; CTAs are given a “neutral/underweight” rating; and Distressed strategies are assigned a pure “underweight” rating. Overall, Deutsche’s 12-month forecast for alternative strategies is “neutral/positive” with a projected 9.1% return. For more information, download a pdf copy of the report .