Tag Archives: function

10.6% Yielding ETW Offers Both Income And A Capital Appreciation Opportunity
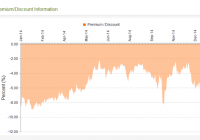
Summary ETW is a global option-income fund that uses a covered call strategy to deliver a 10.6% yield. High-volume selling of ETW has dropped its discount to a level not seen in the last 18 months. Buying ETW today locks in a higher yield and also provides the opportunity for capital appreciation if the discount reverts back to its historical average. Introduction Eaton Vance Tax Managed Global Buy Write Opportunities Fund (NYSE: ETW ) is an option-income close-ended fund [CEF] from Eaton Vance (NYSE: EV ). Thi s fund seeks t o achieve “current income with capital appreciation through investment in global common stock and through utilizing a covered call and options strategy.” ETW currently sports a -10.3% discount and a 10.6% market yield. This yield is generated by maintaining a long exposure to common stocks, while writing call options against the underlying indices. ETW is a global fund which benchmarks itself against a composite of 33% S&P 500, 22% NASDAQ 100, 34% FTSE E100 and 11% Nikkei 225. According to data supplied by Eaton Vance , ETW writes index call options on 94% of its portfolio, with an average of 15 days to expiration, and at 1.6% out of the money. Therefore, ETW can be considered to be a relatively defensive option-income fund. The covered call strategy generates a high level of current income, but caps the upside potential of the fund. This is because the maximum upside of a call option is equal to the strike price of the option plus the premium received. Hence, equity option-income funds are expected to lag the market index in a rising market. On the other hand, option-income funds will likely outperform in sideways or declining markets, which, given the tremendous performance of the U.S. stock market over the past few years, could very well be in store for us in 2015. Additionally, the 10.6% yield is highly attractive to investors seeking decent income from their equity holdings. In a previous article in June 2014, we noted that ETW’s discount of -3.3% was much higher than its 52-week average of -7.7%, while the -8.45% discount of Eaton Vance Tax-Managed Global Diversified Equity Income Fund (NYSE: EXG ) discount was similar to its 52-week average of -8.33%. Given the similar investment mandates of the two funds, the article recommended to sell ETW and buy EXG to take advantage of mean reversion in CEFs. Six weeks later , the discount for ETW had widened from -3.31% to -3.93% while the discount for EXG had narrowed from -8.45% to -5.60%. Hence, this pairs trade was up more than 2.6% in 6 weeks (~23% annualized). Taking advantage of mean reversion in CEFs is a potential strategy o obtain outsized profits. In a July 2014 paper entitled Exploiting Closed-End Fund Discounts: The Market May Be Much More Inefficient Than You Thought , authors Patro, Piccotti and Wu provide significant evidence of mean reversion in closed-end fund premiums. This article identifies an opportunity to buy ETW at a greater discount than its 1-year average. Widening discount The graph below is from CEFConnect and shows the premium/discount value of ETW over the past year. (click to enlarge) The table below shows the current, average 1-year, 3-year and 5-year discount values of ETW (source: CEFConnect). Time Discount 1-year -5.32% 3-year -9.43% 5-year -4.18% Current -10.33% We can see from the data above that ETW’s discount is lower its average discount over all three time periods. According to CEFAnalyzer , the 1Y Z-score for ETW is -1.71, indicating that the current discount of ETW is significantly below its 1Y average discount (adjusted for standard deviation). The 2Y and 4Y Z-scores are -0.48 and 0.37, respectively. What was the reason for this relatively large discount? One culprit may have been the high-volume selling of the fund on the final few trading days of last year. Over 956K shares changed hands in the last four days of 2014 (avg. daily volume = 400K), with the final day’s volume of 1.6M exceeding the volume of any other trading day in 2014. Over the course of those four days, ETW dropped 6.1%, compared to 1.1% for the U.S. stock market (NYSEARCA: SPY ) and 1.4% for the global stock market (NASDAQ: ACWI ). (click to enlarge) However, remember that the market price of a close-ended fund has no relationship to its net asset value. Therefore, the decline in share price of ETW caused by the high-volume selling of the fund over the past couple of days is the equivalent of sweaters going on sale after the holiday: you get the exact same product but at a lower price. The graph below was generated using data from Yahoo . We can see that the yield currently offered by ETW is higher than at any other time point in 2014. Based on the above analysis, I purchased ETW today at a price of $11.23 Buying thesis Lock in a high current yield of 10.6% while being exposed to some upside of the global stock market. Outperform the underlying index in a flat or declining market. Capital appreciation if the current discount of -10.33% narrows back to its average. Risks The discount may widen further. In late 2011, the discount widened to over 15%. The fund will underperform in a strong bull market. Loss of capital in a declining market (albeit with some downside protection due to the call premiums received).
GAL Is An ETF Built From Other ETFs, Let’s Peer Inside

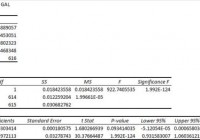
Summary I’m taking a look at GAL as a candidate for inclusion in my ETF portfolio. The description of GAL in the prospectus is a little weird, but I can provide a simpler one. The correlation to SPY is remarkably low for an ETF that holds 24% of the portfolio in shares of SPY. The ETF looks more appealing to investors that are constrained by commissions on trading ETFs. For investors that can build their own portfolio commission free, it is less appealing. I’m not assessing any tax impacts. Investors should check their own situation for tax exposure. Investors should be seeking to improve their risk adjusted returns. I’m a big fan of using ETFs to achieve the risk adjusted returns relative to the portfolios that a normal investor can generate for themselves after trading costs. I’m working on building a new portfolio and I’m going to be analyzing several of the ETFs that I am considering for my personal portfolio. One of the funds that I’m considering is the SPDR SSgA Global Allocation ETF (NYSEARCA: GAL ). I’ll be performing a substantial portion of my analysis along the lines of modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. What does GAL do? GAL is a relatively weird ETF compared to most of the ETFs I have covered. Lacking a better option, I’m going to begin by quoting the prospectus: Under normal circumstances, the Fund invests substantially all of its assets in the SSgA Global Allocation Portfolio (the “Portfolio”), a separate series of the SSgA Master Trust with an identical investment objective as the Fund. As a result, the Fund invests indirectly through the Portfolio. As an analyst, I’m used to digging through complicated statements, but I’m no familiar with the incentives for this structure. I expect most readers won’t know what to make of that either, so I’m providing an alternate description based on my understanding of the ETF. In my estimation, GAL is an ETF that purchases shares in several other ETFs. That should be simple enough to understand, and it’ll make perfect sense when we get to the section on holdings. The category for GAL is “World Allocation.” Does GAL provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use the SPDR S&P 500 Trust ETF (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. Therefore, I start my diversification analysis by seeing how it works with SPY. I start with an ANOVA table: (click to enlarge) The correlation is way better than I would expect. The correlation in this regression is 75%. I want to see low correlations on my international investments. Extremely low levels of correlation are wonderful for establishing a more stable portfolio. I consider anything under 50% to be extremely low. However, for equity securities an extremely low correlation is frequently only found when there are substantial issues with trading volumes that may distort the statistics. Standard deviation of daily returns (dividend adjusted, measured since July 2012) The standard deviation is incredible. For GAL it is .5495%. For SPY, it is 0.7063% for the same period. SPY usually beats other ETFs in this regard, so a lower volatility level is very impressive. Because the ETF has fairly low correlation for equity investments and a low standard deviation of returns, it should do fairly well under modern portfolio theory. Liquidity looks fine Average trading volume isn’t very high, a bit over 55,000, but that also isn’t low enough to be a major concern for me. This is extremely important to the analysis of GAL because the combination of low standard deviation and low correlation immediately set off red flags to watch for low levels of liquidity that might distort the statistics. Mixing it with SPY I also run comparisons on the standard deviation of daily returns for the portfolio assuming that the portfolio is combined with the S&P 500. For research, I assume daily rebalancing because it dramatically simplifies the math. With a 50/50 weighting in a portfolio holding only SPY and GAL, the standard deviation of daily returns across the entire portfolio is 0.5921%. With 80% in SPY and 20% in GAL, the standard deviation of the portfolio would have been .6539%. If an investor wanted to use GAL as a supplement to their portfolio, the standard deviation across the portfolio with 95% in SPY and 5% in GAL would have been .6925%. Why I use standard deviation of daily returns I don’t believe historical returns have predictive power for future returns, but I do believe historical values for standard deviations of returns relative to other ETFs have some predictive power on future risks and correlations. Yield & Taxes The distribution yield is 2.65%. This ETF could be worth considering for retiring investors. I like to see strong yields for retiring portfolios because I don’t want to touch the principal. In my opinion, anything over 2% is high enough to warrant some consideration. Overall, a 2% yield on a portfolio wouldn’t be great for covering retirement costs, but I wouldn’t fill the portfolio with only high yield investments. By investing in ETFs I’m removing some of the human emotions, such as panic. Higher yields imply lower growth rates (without reinvestment) over the long term, but that is an acceptable trade off in my opinion. I’m not a CPA or CFP, so I’m not assessing any tax impacts. Expense Ratio The ETF is posting a .35% expense ratio. I want diversification, I want stability, and I don’t want to pay for them. The expense ratio on this fund is higher than I want to pay for equity securities, but not high enough to make me eliminate it from consideration. I view expense ratios as a very important part of the long term return picture because I want to hold the ETF for a time period measured in decades. Market to NAV The ETF is at a .27% premium to NAV currently. Premiums or discounts to NAV can change very quickly so investors should check prior to putting in an order. The ETF is large enough and liquid enough that I would expect the ETF to stay fairly close to NAV. Generally, I don’t trust deviations from NAV and I will have a strong resistance to paying a premium to NAV to enter into a position. Largest Holdings The diversification looks terrible if you are only looking at the percentage of the fund in each investment. However, since the investments are other ETFs, the actual diversification is phenomenal. This level of diversification is the reason the fund has such a low level of volatility. A chart of the holdings by market value is available below: (click to enlarge) Conclusion I’m currently screening a large volume of ETFs for my own portfolio. The portfolio I’m building is through Schwab, so I’m able to trade GAL with no commissions. I have a strong preference for researching ETFs that are free to trade in my account, so most of my research will be on ETFs that fall under the “ETF OneSource” program. I’m having a difficult time deciding what to think on GAL. It’s the first ETF filled with ETFs that I’ve analyzed. I’m curious about the expense ratio. Before investing in GAL, I would want to know if the .35% expense ratio was strictly the amount that went to the managers of GAL, or if was including all fees charged at all levels of the portfolio. As investors, we already have to pay management of the company and the expense ratio of one ETF; I don’t want to pay the expense ratios twice. However, the correlation to SPY is remarkably low for an ETF that is already holding SPY as nearly a quarter of the portfolio. In my opinion, GAL looks like a better option for investors that are paying commissions on every trade. For those investors, a position in GAL could be combined with a position in SPY (or a similar ETF). If the investor was facing commissions on trades that encouraged them to hold a smaller number of ETFs directly, this could be a viable way of constructing the portfolio. For investors that are have access to a large volume of commission free ETFs, the appeal of GAL is much weaker. Despite the complications on the expenses, I may run more statistics on GAL in a diversified portfolio. It might still be worth a 2% to 5% allocation. The efficient frontier on portfolio structures doesn’t take into account the amount of time required to build very tiny positions in obscure securities. I would be willing to pay some additional expense ratio for that exposure. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis. The analyst holds a diversified portfolio including mutual funds or index funds which may include a small long exposure to the stock.

QDEU Offers Diversification To SPY, But The Holdings Are Concentrated

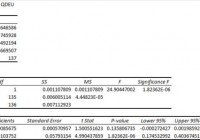
Summary I’m taking a look at QDEU as a candidate for inclusion in my ETF portfolio. The expense ratio relative to the diversification is unappealing. The extremely low correlation with other major funds (like SPY) is great, but could be related to the small sample size. The trading volume is low, but much higher than other international ETFs by the same source. I’m not assessing any tax impacts. Investors should check their own situation for tax exposure. Investors should be seeking to improve their risk adjusted returns. I’m a big fan of using ETFs to achieve the risk adjusted returns relative to the portfolios that a normal investor can generate for themselves after trading costs. I’m working on building a new portfolio and I’m going to be analyzing several of the ETFs that I am considering for my personal portfolio. One of the funds that I’m considering is the SPDR® MSCI Germany Quality Mix ETF (NYSEARCA: QDEU ). I’ll be performing a substantial portion of my analysis along the lines of modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. What does QDEU do? QDEU attempts to track the total return of the MSCI Germany Quality Mix Index. Normally at least 80% of the assets are invested in funds included in this index, but there appears to be some leeway under unusual market conditions. QDEU falls under the category of “Miscellaneous Region”. Does QDEU provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use the SPDR S&P 500 Trust ETF (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. Therefore, I start my diversification analysis by seeing how it works with SPY. I start with an ANOVA table: (click to enlarge) The correlation is only 39%, which is great for modern portfolio theory. Extremely low levels of correlation are wonderful for establishing a more stable portfolio. I consider anything under 50% to be extremely low. Standard deviation of daily returns (dividend adjusted, measured since June 2014) The standard deviation is fairly high. For QDEU it is .9872%. For SPY, it is 0.7232% for the same period. SPY usually beats other ETFs in this regard, but SPY doesn’t usually beat them by this much. If the correlation fails to predict future levels of correlation, then this volatility could become an issue. Major risks The ETF has moderately low volume, but it is substantially higher than many of the SPDR® MSCI ETFs I have considered. The average volume has been running around 10,000 shares. This is still a low volume, but not as low as some of the ETFs I have covered. However, when I checked the daily return values I saw a problem. For having almost 10,000 shares per day trading hands, on average, the number of days in which the share price did not move by a cent was a problem. It appears that over the last few months this problem has started to get better. However, it still happened quite a few times in December. The days where no shares are being traded may cause the computed correlation and standard deviation to be inaccurate. Mixing it with SPY I also run comparisons on the standard deviation of daily returns for the portfolio assuming that the portfolio is combined with the S&P 500. For research, I assume daily rebalancing because it dramatically simplifies the math. With a 50/50 weighting in a portfolio holding only SPY and QDEU, the standard deviation of daily returns across the entire portfolio is 0.7178%. With 80% in SPY and 20% in QDEU, the standard deviation of the portfolio would have been .6811%. If an investor wanted to use QDEU as a supplement to their portfolio, the standard deviation across the portfolio with 95% in SPY and 5% in QDEU would have been .7080%. Why I use standard deviation of daily returns I don’t believe historical returns have predictive power for future returns, but I do believe historical values for standard deviations of returns relative to other ETFs have some predictive power on future risks and correlations. Yield & Taxes The SEC yield is 2.06%. That appears to be a respectable yield. At a 2% yield, this ETF could be worth considering for retiring investors, but only if they do not need to be concerned about liquidity. I’m not a CPA or CFP, so I’m not assessing any tax impacts. Expense Ratio The ETF is posting .30% for an expense ratio. I want diversification, I want stability, and I don’t want to pay for them. The expense ratio on this fund is higher than I want to pay for equity securities, but not high enough to make me eliminate it from consideration. Market to NAV The ETF is at a .54% premium to NAV currently. Premiums or discounts to NAV can change very quickly so investors should check prior to putting in an order. I don’t want to pay a premium over .2%, so I would only consider entering through a limit order that required a slightly lower price. Largest Holdings The diversification within the ETF is bad. The top 10 securities represent 48.61% of the portfolio’s value. That’s pretty terrible for an ETF. I’m not pleased with the diversification. (click to enlarge) Conclusion I’m currently screening a large volume of ETFs for my own portfolio. The portfolio I’m building is through Schwab, so I’m able to trade QDEU with no commissions. I have a strong preference for researching ETFs that are free to trade in my account, so most of my research will be on ETFs that fall under the “ETF OneSource” program. The low correlation looks good and the liquidity, despite being low, isn’t low enough to risk scaring me off. The weak diversification combined with the moderate to high expense ratio leaves me feeling that as an investor I deserve more. I’ll consider QDEU, but I may also need to look into their expense ratio and see what they are doing to earn it. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis. The analyst holds a diversified portfolio including mutual funds or index funds which may include a small long exposure to the stock.