Tag Archives: management

PKW Shouldn’t Be Able To Outperform SPY Reliably, But It Did
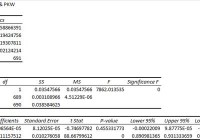
Summary I’m taking a look at PKW as a candidate for inclusion in my ETF portfolio. The risk level is reasonable and the correlation is high. The performance is surprisingly good. The liquidity is solid, so I expect the statistics to be reliable. Despite the higher expense ratio, the ETF has stacked up very well to SPY over the last several years. Investors should be seeking to improve their risk adjusted returns. I’m a big fan of using ETFs to achieve the risk adjusted returns relative to the portfolios that a normal investor can generate for themselves after trading costs. I’m working on building a new portfolio and I’m going to be analyzing several of the ETFs that I am considering for my personal portfolio. One of the funds that I’m considering is the PowerShares Buyback Achievers Portfolio (NYSEARCA: PKW ). I’ll be performing a substantial portion of my analysis along the lines of modern portfolio theory, so my goal is to find ways to minimize costs while achieving diversification to reduce my risk level. What does PKW do? PKW attempts to track the total return (before fees and expenses) of NASDAQ Buyback Achievers® Index. At least 90% of the assets are invested in funds included in this index. PKW falls under the category of “Large Blend”. Does PKW provide diversification benefits to a portfolio? Each investor may hold a different portfolio, but I use (NYSEARCA: SPY ) as the basis for my analysis. I believe SPY, or another large cap U.S. fund with similar properties, represents the reasonable first step for many investors designing an ETF portfolio. Therefore, I start my diversification analysis by seeing how it works with SPY. I start with an ANOVA table: (click to enlarge) The correlation is just under 96%. That’s a very high level of correlation and relatively unattractive for investors hoping for diversification benefits. As an investor using modern portfolio theory, I would prefer to see lower levels of correlation. Of course, the low value correlation wouldn’t mean much if the values were being distorted by poor liquidity. The average volume of nearly 500,000 shares per day suggests that liquidity shouldn’t be a concern. That’s a good sign for investors wanting verification of the statistics or wanting to know that they can exit the position with less concern about it deviating from NAV. Standard deviation of daily returns (dividend adjusted, measured since November 2013) The standard deviation is fairly reasonable. For PKW, it is .787%. For SPY, it is 0.748% for the same period. The ETF is definitely showing a little more volatility than SPY when we compare returns on a daily basis. Mixing it with SPY I frequently run comparisons on the standard deviation of daily returns for the portfolio, assuming that the portfolio is combined with the S&P 500. However, for PKW, I don’t think that adds much value. The correlation being nearly 96% really destroys the benefits of diversification. Why I use standard deviation of daily returns I don’t believe historical returns have predictive power for future returns, but I do believe historical values for standard deviations of returns relative to other ETFs have some predictive power on future risks and correlations. Yield and Taxes The distribution yield is 1.06%. I like to see strong yields for retiring portfolios, because I don’t want to touch the principal. By investing in ETFs I’m removing some of the human emotions, such as panic. Higher yields imply lower growth rates (without reinvestment) over the long term, but that is an acceptable trade off in my opinion. This ETF doesn’t have a high yield, but I am far enough away from retirement to be willing to work with the weaker yields. Expense Ratio The ETF is posting an expense ratio of .68%. That’s high compared to most of the ETFs that are appealing to me, but the expense ratio may reflect the premium being charged for the trading methodology the ETF is using to determine the positions within the ETF. Market to NAV The ETF is at a .06% discount to NAV currently. Premiums or discounts to NAV can change very quickly, so investors should check prior to putting in an order. Generally speaking, that discount to NAV isn’t big enough to be a big deal. However, even a small discount to NAV is fairly attractive when we are talking about a high quality ETF. Largest Holdings The diversification in the holdings isn’t going to be a strong selling point. (click to enlarge) Conclusion PKW was one of the most difficult ETFs to make a decision about. The ETF posts a very high correlation to SPY and a high expense ratio. Some screeners don’t have a portfolio turnover ratio for the ETF, but the prospectus states that in the last fiscal year the turnover ratio was 92%. I expect that kind of turnover to require some costs, but I generally don’t want to pay higher turnover ratios because my use of ETFs involves relying on markets to be reasonably efficient. If the markets are thoroughly efficient, then creating a proprietary trading system to select which positions to enter and which ones to end should not result in any reliable excess returns. However, history is providing some support for the methodology PKW is using. I was suspicious about their outperformance of SPY in the test period, so I extended my sample to a five-year period and looked at the returns on a time line. The result is that PKW outperformed SPY meaningfully over that five-year period. Looking at the lines, it isn’t a single period where PKW outperformed either. The fund’s performance has been strong and steady, which makes it appear more repeatable. I wanted to eliminate the ETF for the high expense ratio and relative weakness in diversification, but I can’t do it. Maybe it is just chance that eventually an ETF had to deliver this kind of strong performance over an extended period, but I won’t toss out an ETF that makes a fairly impressive case for itself without digging deeper. Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it (other than from Seeking Alpha). The author has no business relationship with any company whose stock is mentioned in this article. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis. The analyst holds a diversified portfolio including mutual funds or index funds which may include a small long exposure to the stock.
Danger Zone: Berkshire Focus Fund

Summary A very dangerous fund in one of the most dangerous sectors. This fund holds multiple stocks that have a history of blowing up on investors. BFOCX charges investors far too much for these risky holdings. The Berkshire Focus Fund (MUTF: BFOCX ) is in the Danger Zone this week based on our investment research due to its poor holdings. Looking into this mutual fund’s holdings reveals a number of stocks with the potential to blow up, including some companies recently placed in the Danger Zone themselves. BFOCX has failed to perform this year, gaining only 1.6% year to date. Its poor holdings threaten to erase this small gain and quickly turn it negative. Holdings Always Determine Returns At the beginning of November, I highlighted why the tech sector was a bad investment . On average, the ETFs and mutual funds in the Tech sector provide subpar stock picking and charge you higher fees to do so. BFOCX focuses on investing in the Tech sector, and actually ranks worse than average when it comes to stock picking and annual costs. The Three Biggest Problems With This Fund BFOCX earns my Very Dangerous overall rating because it allocates 15% of its value to three stocks that I’ve recently highlighted as high risk. Workday (NYSE: WDAY ) accounts for 5.9% of BFOCX’s holdings, while Salesforce.com (NYSE: CRM ) and Netflix (NASDAQ: NFLX ) each make up 4.9% of BFOCX’s portfolio. NFLX, WDAY, and CRM are all recent inductees to the Danger Zone. All three of these companies have negative free cash flow , massive amounts of debt, and major profit growth expectations baked into their valuations. WDAY and CRM are two companies that fail to even earn an operating profit despite consistently increasing revenues. The large allocation to these three stocks alone would be reason enough to avoid BFOCX. Unfortunately, the rest of BFOCX’s holdings aren’t any better. Over 86% of the fund’s holdings are allocated to Dangerous-or-worse rated stocks. Not a single Attractive or Very Attractive stock makes it into BFOCX’s portfolio. Other Toxic Holdings BFOCX over-allocates to overvalued companies with low returns on invested capital ( ROIC ) and in some cases low or no after-tax profit ( NOPAT ). WDAY, NFLX, and CRM are just the beginning of its poor holdings. Palo Alto Networks (NYSE: PANW ) and Service Now (NYSE: NOW ) are two other companies with negative ROICs and other issues. Palo Alto Networks has not earned a positive ROIC since going public in 2012. Its NOPAT has declined since 2012 and reached -$44 million in 2014. It has over $700 million in total debt (over 7% of market cap), and has generated negative free cash flow each the past three years. Just like Workday and Salesforce, Palo Alto Networks is growing revenue while NOPAT declines. Making matters worse, PANW’s current valuation of ~$120/share implies that the company will achieve positive NOPAT margins and grow revenue by 25% compounded annually for 34 years. Seeing as how PANW has failed to achieve positive margins in the past two years or grow NOPAT at all, the market’s expectations appear overly optimistic. While this company may be a growth story, its valuation gives PANW a very unattractive risk/reward ratio. Toxic Costs The last issue with BFOCX is something I have long advocated as a crucial issue for fund investors. BFOCX charges investors above average total annual costs of 3.29%. Included in this is 1% in annualized transaction costs due to the extremely high turnover of the fund. In 2014, the average turnover was 460%. Poor holdings combined with high fees make BFOCX a portfolio-killer . Need For Diligence Wouldn’t you like to know where the money you’re investing is being allocated? In the case of BFOCX, the managers are allocating investors’ money to poor stocks. Many of them have high revenue growth but no profits. Growing revenue comes at a cost, and the companies highlighted above also have free cash flow issues, making their future look questionable. Don’t get burned when the cash runs dry and the companies can no longer grow at the pace that the market demands. This trap has already been sprung on investors in AMZN, NFLX, WDAY, and GLUU. Stay out of the trap and avoid BFOCX. Kyle Guske II contributed to this report. Disclosure: David Trainer and Kyle Guske II receive no compensation to write about any specific stock, sector, or theme. Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it. The author has no business relationship with any company whose stock is mentioned in this article.

How Cash Can Boost Long-Term Returns

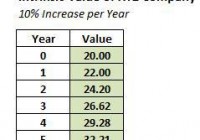
Summary Liquidity management is one of the most critical aspects of investment. Cash earns a 0% nominal return, but allows investors to take advantage of higher-return opportunities that may emerge. By holding more cash, one is betting that the purchasing power will increase at a future point. Moderation is key with holding cash; it’s rarely advisable to go to 100% cash or 0% cash. I’d recommend a cash position in the 20% – 40% range for most investors right now due to higher than average risks in the market. Buying stocks at depressed prices (i.e. with a large “margin of safety”) is the best way to generate superior returns over time. Cash, on the other hand, generates a 0% return. Absent a highly unlikely episode of hyper-deflation, you cannot become wealthy holding cash. In spite of this, I’d recommend holding 20% – 40% of your portfolio in cash right now. The reason for this is that there is value to liquidity, particularly in an inflated market environment. By holding cash, what you are actually doing is betting that the future value of your money in the market will be worth more than the present value. How can cash help you generate better returns? The key is to understand intrinsic value and the mathematics of investing. Intrinsic Value Price is what you pay for an asset. Intrinsic value is the fundamental worth of an asset. Therefore, an asset could be priced at $20,000, but have an intrinsic value of $30,000. In that instance, you are getting a bargain, because you are paying 33% less than the intrinsic value. In reality, it’s impossible to know the exact intrinsic value of a stock. None of us can see the future. Yet, we can come up with reasonable estimates of intrinsic value through a fundamental analysis of a company. That said, in order to explain why holding cash can be beneficial, we’ll first need to assume we can read the future. In this scenario, let’s say we know with absolute certainty that the intrinsic value of XYZ Company’s stock is $20. Now, we’re going to be able to live in five different alternate realities. In the first scenario, XYZ Company’s stock is selling at the depressed price of $5. In the second scenario, the stock sells at a still somewhat depressed price of $10. The third scenario will allow us to purchase the stock for $20; which is precisely the intrinsic value. In the fourth scenario the stock will sell at an inflated price of $25, and in the fifth scenario, it will sell at an even more inflated price of $30. Now, we’ll say that in each of our five alternate realities, we will purchase the stock and hold it for five years. We also know for a fact that the intrinsic value will grow 10% per year. You can see how the intrinsic value grows in the chart below. With that, let’s take a look at what happens. The Power of Compounding Now that we’ve created the set-up, you can see the return figures for all five scenarios below for a five-year holding period. It immediately becomes clear how dramatic the difference is between purchasing XYZ’s stock at a depressed price versus an inflated price. The “inflated price” only yields a 1.4% annual return, while the “depressed price” yields an astronomical 45.1% annual return! To put this further in perspective, if you started with $10,000 and generated a 45.1% annual return for the indefinite future, you would have $100,000 in a little over 6 years. On the other hand, if you generated a 1.4% for the foreseeable future, it would take you 166 years for you to turn that $10,000 into $100,000. That’s not a misprint! That’s the power of compounding. This is also the reason why an investor that generates a 17% annual return over 10 years is significantly better than one generating a 15% annual return. It may seem like a very small difference, but over a long-term timeframe, it really adds up. An investor making 15% annually on a $10,000 initial investment for 25 years would have $329,000 at the end of that timeframe. An investor generating a 17% annual return, on the other hand, would have $507,000; roughly 54% more. Why Cash is Valuable Given this math, it starts to become clearer why holding cash can sometimes led to higher long-term returns. Let’s say that XYZ’s stock was selling at the inflated price of $30, but you could see the future, and knew it could fall back down to $15 in 3 years. For simplicity’s sake, we’ll still assume that you plan to sell off at the end of Year #5 at the intrinsic value of $32.21. What would be your best option? (1) Buying the stock immediately and earning the 1.4% return for 5 years, (2) Holding cash for 3 years and then buying in at the semi-depressed price of $15 The answer is that option #2 is much more profitable. After five years, you’ll only generate a total return of 7.2% in Scenario #1, but you’ll achieve a 114.7% return in Scenario #2, in spite of the fact that you made a 0% return the first three years. This example showcases why the relationship between price and value are so important. It also shows why value investing works so well. What may seem like small differences in price can drive very large differences in return. Hold Some Cash Given the inflated market environment we are currently seeing, I believe it’s prudent to hold 20% – 40% of one’s portfolio right now. It’s true that you’ll likely underperform in the short-term (e.g. 1-3 years) as a result of this strategy. However, in the long-term, it makes more sense to take the 0% return now (on a part of your portfolio), and then use the liquidity to strike later when the returns become much more attractive. Of course, this should not dissuade you from taking advantage of bargains as you see them become available. And while I believe the broad market is overpriced, on a micro level, there will always be bargains out there. Yet, even if you can find a lot of bargains, I’d still recommend holding a good clip of cash, because even better bargains could become available the next time we find ourselves in a recession or a falling market environment. How much cash you hold in your portfolio depends upon your preferences and personal situation. If you’re in a situation where you can’t afford to lose much right now (i.e. you might need your cash for other purposes), I would recommend playing things fairly conservatively and holding a very large cash position. Even if you’re not worried about pulling out cash, I do think a minimum 10% cash position is prudent; and frankly, I wouldn’t dip below 20%. Conclusions Holding cash and generating a 0% return may seem like a poor option on the face of it, but once you understand the math behind returns, it makes a lot sense. By holding cash now, you’re hoping that you can generate higher returns in a future environment with lower prices. It’s never wise to go 100% cash, because at that point, you’re merely speculating. In an environment where stock prices seem inflated and there are few bargains out there, it makes sense to hold an elevated cash position in the range of 20% – 40% of your portfolio. On the other hand, in a depressed stock environment (such as the one we saw in late 2008 and early 2009), you should try to be as fully invested as possible, holding no more than 5% cash. Right now, I view us as being in an inflated environment and holding a 20% – 40% cash position is a prudent strategy. Your returns will lag in the short-term, but if there’s a market correction, you’ll more than make up for it in the long-term. This article appears in the February 2015 edition of Jake Huneycutt’s Contrarian Value Newsletter Disclosure: The author has no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) The author wrote this article themselves, and it expresses their own opinions. The author is not receiving compensation for it. The author has no business relationship with any company whose stock is mentioned in this article.