Tag Archives: management

Facts, Opinions, And Risk Management

Editor’s note: Originally published at tsi-blog.com on August 14, 2015. Commentators on the financial markets often make statements like “it’s a bull market” and “the trend is up” as if these were indisputable facts, but such statements are always opinions. A statement of fact could reasonably be phrased along the lines of “the market was in an upward trend between date X and date Y,” because if a sequence of rising lows and rising highs occurred between two dates then the trend was, by definition, up during that period. However, it is impossible to know the direction of a market’s current price trend with absolute certainty, let alone the direction of its future price trend. The reason is that even if a market has just made a new high/low, there will be some chance that this will turn out to be the ultimate high/low. For example, it’s a fact that gold was in a bear market in US$ terms from its peak in September of 2011 through to 24th July 2015 (when it hit a 4-year low of $1072), but it is a matter of opinion as to whether gold is now in a bear market. The bear market could obviously still be in progress, but there is also a possibility that it ended on 24th July 2015. At the time of writing, nobody knows for sure. Some market participants and commentators will draw a line on a chart and then make a statement such as “I will consider the trend to be up (or down) unless the market proves otherwise by moving below (or above) my line”. Fine, but there’s a big difference between claiming to know the direction of the price trend and working under the assumption that the trend is in a particular direction unless/until proven otherwise by some predetermined event. The valley of shattered financial dreams is littered with traders who were determined to stay ‘long’ or ‘short’ because they thought they KNEW the direction of the price trend. The impossibility of knowing whether a bull/bear market or an up/down trend is going to continue, or even whether the market is currently in bull or bear mode, makes risk management essential. Someone who knew the future would never have to bother with risk management; they could, instead, risk everything on a particular outcome because for them it wouldn’t be a risk at all. But ordinary mortals always face a degree of uncertainty when making investment decisions and, as a result, always need to face the reality that these decisions could prove to be wrong. Be wary, then, of advisors who claim that there is only one possible direction for the future price of an investment. But while unwillingness to acknowledge the possibility of being wrong is a defect in the approach of some investors, other investors suffer from the opposite problem in that they have a hard time maintaining a bullish or bearish view unless that view is continually being validated by the price action. That is, they are incapable of remaining confident in any opinion that doesn’t happen to conform to the current opinion of the manic-depressive mob. As a result, they routinely get ‘sucked in’ following large price rises and ‘blown out’ following large price declines, as opposed to taking advantage of the mob’s proclivity to be wrong. Therefore, as investors, the challenge we all face is to strike a balance between staying the course in rough weather and preparing ourselves for the possibility that there could be unseen rocks up ahead.
Making Sense Of China’s Currency Devaluation

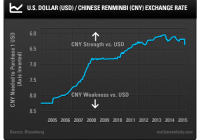
Alan Gula, CFA Earlier this week, two massive explosions rocked the Chinese port city of Tianjin. It’s said that the larger explosion was equivalent to over 20 tons of TNT being detonated. The blasts were so large that seismic activity was registered around 100 miles away. The exact cause of the explosions is unknown, but other shocks emanating from China have clearer triggers. On August 11, 2015, China devalued its currency, the renminbi (yuan), by 1.9%. It was the currency’s biggest one-day drop since 1994. It didn’t stop there, either. At one point the following day, the yuan had cumulatively lost as much as 3.9% of its value against the dollar. Policymakers in China seem to be following through on their promise to allow the market to play a bigger role in determining the exchange rate. “A fixed exchange rate looks stable, but it hides accumulated problems,” noted Yi Gang, Vice Governor of China’s central bank. China doesn’t have a fixed peg, but it does heavily manage the yuan’s level relative to the U.S. dollar. The chart below helps us put the devaluation into perspective. The y-axis has been inverted so that a rising line shows the yuan’s strength. As you can see, China allowed the yuan to significantly appreciate against the dollar from 2005 up until the credit crisis. The fixed peg was reinstituted from mid-2008 until mid-2010. Then, the yuan began a slower appreciation, which culminated in early 2014. So, the yuan’s relatively small recent devaluation has only given back a small portion of its longer-term appreciation. That said, we shouldn’t downplay what’s happening right now. The U.S. dollar bull market has really forced China’s hand. The dollar has been very strong over the past year against virtually all global currencies. Therefore, the yuan has been dragged higher. With a strong currency, China has lost some of its export competitiveness. China has also been burning through foreign exchange reserves to keep the yuan at a level above where it would naturally be. Given that China’s economy is slowing, its exports are flagging, and its speculative bubbles are collapsing, the move wasn’t completely unexpected. Plus, an increasingly market-driven exchange rate will pave the way for the yuan to enter the Special Drawing Rights (SDR) basket. Nonetheless, the market seemed to be surprised by the devaluation. Global equity markets dipped and the U.S. 10-year yield declined all the way to 2.05%. China’s move has sparked fears that a new wave of deflation will wash over the world. A weaker yuan will also help boost China’s exports at the expense of other nations. Koichi Hamada, an adviser to Japan’s Prime Minister, went so far as to say that Japan can offset the yuan devaluation with monetary easing. Indeed, it’s clear to see why there’s a risk of escalating competitive devaluations or “currency wars.” For individual investors, it’s important to keep everything in perspective. Just a little while ago, Greece and Europe were roiling the markets. Now, it’s China’s turn. Soon, there will be something else. If you’re getting spooked by these news-driven stock market plunges, only to buy higher after a fierce rally, you’re doing it wrong. Many traders and investors are simply getting whipsawed by the volatility. Meanwhile, the S&P 500 has effectively gone nowhere since the Fed’s latest quantitative easing (QE3) program ended. This is why everyone should hold globally diversified portfolios of stocks, preferred stocks, bonds, and real assets. There are going to be more (and much larger) disturbances down the road, and their timing is uncertain. By being properly diversified and intelligently taking on risk, you’ll protect yourself from the market shocks and volatility storms coming our way. Original Post

Biotech Boom Over? 3 Health Care ETFs To Invest In Instead

The hot and the soaring biotechnology corner of the broad U.S. health care market endured a steep correction last week. In any case the space has long been guilty of overvaluation, with even the Fed chair Yellen pointing to it last year. But investors seemed unaffected as the largest biotech ETF, iShares Nasdaq Biotechnology (NASDAQ: IBB ), added over 22% this year and gained about 50% in the last one-year time frame. However, the bubble had to burst sometime and last week we heard a loud popping noise. IBB was off about 4% and also saw about $522 million in asset outflow last week, per etf.com . Other biotech ETFs also witnessed a sharp sell-off with BioShares Biotechnology Clinical Trials Fund (NASDAQ: BBC ) shedding about 7.5%, Medical Breakthroughs ETF (NYSEARCA: SBIO ) losing 6.2% and SPDR S&P Biotech ETF (NYSEARCA: XBI ) retreating 6%. Though this does not push the biotech space in an outright bear territory, as the area is full of possibilities, investors can take a look at some health care ETFs that bypassed last week’s biotech sell-off. After all, the sector has no dearth of drivers. The merger and acquisition frenzy, encouraging industry fundamentals, promising new drugs, growing demand in emerging markets, ever-increasing health care spending and Obama care play major roles to make it a lucrative bet for the long term. These health care ETFs are all Buy-rated and were in positive territory last week overruling the biotech correction; and they could be on watch in the short term, at least until the penchant for biotech investing returns. Investors should note that apart from the trio, the entire health care space was under pressure last week. PowerShares S&P SmallCap Health Care Portfolio (NASDAQ: PSCH ) This ETF delivered spectacular performance in the broad health care world, returning nearly 24% so far this year and was up 1.14% over the last five trading sessions (as of August 10, 2015). The fund offers concentrated exposure to small-cap health care securities. It holds 73 securities in its basket, with each security holding less than 3.93% share. From an industry perspective, about one-third of the portfolio is allotted toward health care equipment and supplies, followed by health care providers and services (28.3%) and pharmaceuticals (15.7%). The ETF has amassed $253 million in asset and trades in lower volume of about 25,000 shares per day, while charging a relatively low fee of 29 bps a year. The fund has a Zacks ETF Rank #1 (Strong Buy) with a High risk outlook. SPDR S&P Health Care Services ETF (NYSEARCA: XHS ) This product uses the equal weight methodology by tracking the S&P Health Care Services Select Industry Index. Holding 59 stocks in its basket, each security accounts for less than 2.3% of total assets. This is often an overlooked fund with AUM of $205 million and average daily volume of about 20,000 shares. From an industry look, health care services accounts for over one-third of the portfolio while health care facilities, managed health care and health care distributors have considerable allocation. The product charges 35 bps in annual fees. XHS gained about 1% in the last week and returned 18.3% in the year-to-date time frame. It also has a Zacks ETF Rank #1 with a Medium risk outlook. iShares U.S. Healthcare Providers ETF (NYSEARCA: IHF ) This ETF follows the Dow Jones U.S. Select Healthcare Providers Index with exposure to companies that provide health insurance, diagnostics and specialized treatment. In total, the fund holds 51 securities in its basket with major allocations going to United Health and Express Scripts at 12.4% and 7.8%, respectively. Other firms do not hold more than 6.3% of IHF. The fund has been able to manage more than $1 billion in its asset base while volume is moderate at about 84,000 shares per day on average. It charges 43 bps in annual fees and expenses. The Zacks ETF Rank #1 fund added 0.3% in the last week, while it is up over 18% so far this year. Original Post