Author Archives: Scalper1

SPDR Barclays Capital High Yield Bond ETF: Great Yields And An Intelligent Portfolio
Summary The SPDR Barclays Capital High Yield Bond ETF is a junk bond fund that offers a fairly strong yield, around 6%. One concern is that 14% of the debt is not rated. The exposure to debt that is not rated may be an acceptable trade-off for the strong yields as long as the portfolio managers are doing their own due diligence. The maturities look fairly reasonable and holdings are not highly concentrated, so the overall portfolio construction looks solid. Investors should be using more than junk bonds in their investment portfolio. Correlation to the S&P 500 is a problem for junk bond ETFs. The SPDR Barclays Capital High Yield Bond ETF (NYSEARCA: JNK ) is a pretty good bond fund for exposure to securities ranging from BB to “Not Rated,” though nothing in the portfolio is actually rated anything less than B. The credit ratings won’t be stellar on a junk bond fund and the fund sure doesn’t try to hide it. Their ticker symbol of JNK is simply a play on “junk.” Every buy should know going in that they are buying credit sensitive debt securities. Credit Quality The allocation here seems is perfectly reasonable with the exception that a large amount of not rated bonds is slightly concerning: (click to enlarge) While I would like to have ratings on all or almost all of the debt being held, I can see how having debt that is not rated may be an advantage in producing higher yields if the portfolio managers are willing to do the due diligence to determine what the most likely rating would be if it were rated. In my opinion, this is an acceptable trade-off when most funds have weak yields and JNK is yielding around 6%. In a normal interest rate environment investors may expect materially higher yields, but in the weak yield environment we are all living through, this is one of the higher yielding debt options. Holdings I prepared the following chart showing the largest debt holdings of JNK. (click to enlarge) No problems are jumping out at me. Nothing was over .6% of the portfolio and within the top 10 I don’t see any duplication of the same issuers so I have no reason to expect a concentration of credit risk with individual issuers. Since about 14% of the portfolio was non-rated, it felt more important to double check for any large holdings that might be attributed to one non-rated company. Maturities I grabbed another chart to show the maturity ranges across the portfolio: (click to enlarge) The maturity profile for the SPDR Barclays Capital High Yield Bond ETF looks good for a junk bond fund. However, I must admit that the tiny allocations to the very long-term debt are interesting. Yes, there are generally lower than the category averages but I assume that the category averages may be influenced by a few funds classified into the category that have different investing strategies. Simply put, this is a little strange because it feels like the managers by operating outside of their area of expertise (evaluating short-term credit sensitive debt). On the other hand, these longer securities may simply be bargains they came across while doing their regular work. With it being such a small percentage of the portfolio, I don’t think it is worth worrying about. On the whole, JNK gets a solid rating on providing some diversification across the maturities without becoming too dispersed. There is not one “right” answer about how to structure the maturities, but I like the arrangement shown here. Risk The biggest risk factor from a portfolio standpoint that came up for me was a strong correlation (over 70%) in monthly returns with the S&P 500. Since one purpose of the bond portion of the portfolio is to provide diversification, it is a strike against junk bond funds that they tend to move with the market. That is a problem that should be impacting most junk bonds though, not a risk unique to JNK. When comparing JNK to other junk bond funds, this should not be held against it. Expense Ratio The expense ratio isn’t awful at .40%, however, I still want to keep looking for options where the ratio is lower. Given the relatively low yields on bonds currently and the need to buy junk bonds to get a solid yield, it really hurts to give up a significant portion of the assets to the expense ratio each year. Conclusion If an investor is looking at the role of the bond fund in their portfolio, it would be wise to consider having multiple bond funds if the first one is going to be investing in junk bonds. This kind of fund can offer some diversification benefits to investors, but it would be most productive in a portfolio that combines it with a few other bond funds with different duration exposures and higher credit ratings to enhance the diversification benefits that bonds bring to the investor’s portfolio. When it comes simply to selecting which junk bond fund an investor should use, JNK seems like a decent choice. I’ve still got quite a few funds to consider, but I’m not seeing any major failings here so far. I’m looking for a similar ETF with a very low expense ratio to really stand out as a junk bond fund champion. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article. Additional disclosure: Information in this article represents the opinion of the analyst. All statements are represented as opinions, rather than facts, and should not be construed as advice to buy or sell a security. Ratings of “outperform” and “underperform” reflect the analyst’s estimation of a divergence between the market value for a security and the price that would be appropriate given the potential for risks and returns relative to other securities. The analyst does not know your particular objectives for returns or constraints upon investing. All investors are encouraged to do their own research before making any investment decision. Information is regularly obtained from Yahoo Finance, Google Finance, and SEC Database. If Yahoo, Google, or the SEC database contained faulty or old information it could be incorporated into my analysis.
Using Attribution Analysis To Gain Perspective On Actively Managed Funds

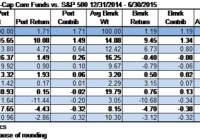
Much has been written about the mass exodus of investors from large-cap actively managed funds over the last several years. For 2014 alone, despite a relatively strong one-year return from the group (+10.72%), investors redeemed some $34.5 billion from actively managed large-cap funds, while they padded the coffers of passively managed funds (+$17.4 billion). Nonetheless, the actively managed large-cap funds group is still the largest group in the equity universe, with $1.6 trillion under management, while its passively managed brethren (excluding S&P 500 Index funds) have a little over $335 billion under management. Although on average passively managed funds have recently outpaced their actively managed counterparts, there are certain times when actively managed funds do indeed outperform. When bull markets start to lose steam and stock picking comes back into vogue or when markets are in a funk, research has shown that actively managed funds are often poised to post better returns than their passively managed counterparts. Year to date through June 30, 2015, in the current sideways market actively managed large-cap funds (+1.95%) have outperformed passively managed (pure index) large-cap funds (+1.33%). Since the performance of active and passive strategies runs in cycles, it’s important to set expectations for clients. To help explain performance trends of actively managed funds vis-à-vis their benchmarks, it’s useful to dive deeper into portfolio practice. For the remainder of this segment we’ll focus on Lipper’s Large-Cap Core Funds (LCCE) classification using attribution-analysis tools. Attribution analysis gives us a way to assign performance qualities to the manager’s portfolio allocation choices (that is, under- or over-allocation to a particular industry, which is referred to as the allocation effect) and to the manager’s stock selection decisions (the selection effect) compared to the composition of the benchmark’s holdings. For 2014, ignoring the impact of expenses on returns, the average actively managed LCCE fund (+13.13%) underperformed the S&P 500 daily reinvested composite (+13.65%) by 52 basis points (bps). In our initial deep dive we note that the average actively managed LCCE fund lagged the benchmark by 2 bps because of allocation effect, while stock selection led to underperformance of 50 bps. In particular, an over-allocation to poorly performing stocks in the finance sector (e.g., Genworth Financial (NYSE: GNW ), Standard Charter ( OTCPK:SCBFF ), and Ocwen Financial (NYSE: OCN )) weighed heavily on active LCCE funds compared with the benchmark, with an economic sector selection effect of minus 51 bps. On the flipside a slight overweighting in consumer discretionary stocks with superior stock returns within the subgroup compared to the benchmark helped the average actively managed LCCE funds’ return, adding 29 bps to the total effect (allocation effect and selection effect combined). However, so far in 2015-and again ignoring expenses-the average actively managed LCCE fund (+1.71%) has outpaced its benchmark (+1.19%) by 52 bps (+28 bps allocation effect and +23 bps selection effect). The average actively managed LCCE fund was slightly over-allocated to healthcare stocks compared to the S&P 500 Index’s allocation, boosting the comparative return 5 bps, while the average portfolio manager’s stock-picking abilities in this sideways market added some 9 bps to the overall return. (click to enlarge) Source: Lipper, a Thomson Reuters company In the analysis above fund expenses are not included in order to provide a true apples-to-apples comparison. This analysis is based on portfolio construction, comparing allocation and stock picking impacts before the consideration of expenses, which are generally easy to assess. Once the trend of the group is found, it is an easy mathematical exercise to slot in expenses. This type of review helps us isolate the pros and cons of various fund groups or individual funds. Attribution analysis can be used as well to highlight funds with superior and inferior performance within a classification, and it can provide a clear explanation of why those findings occurred. As an example, we have identified one of the best performing funds in the LCCE classification over the one-year period ended June 30, 2015, and have run it through attribution analysis to find out how it achieved its outperformance. While this is not a substitution for risk-adjusted return analysis, it provides one more piece of the puzzle, helping us offer detailed explanations to our clients. The following is provided as an example only and is not intended to be a recommendation of any sort. PNC Large Cap Core Fund (MUTF: PLEAX ) posted a one-year return before expenses of 12.66%, while its benchmark-the S&P 500-returned 7.36%. According to attribution analysis, the fund had an allocation effect of 1.28% and a selection effect of 4.02%. While the PNC fund was slightly under-allocated to the information technology sector, providing an allocation effect of minus 0 bps, the portfolio manager’s stock selection within the sector was the primary factor of outperformance, providing a selection effect of 2.51%, with significantly higher weightings to Skyworks Solutions (NASDAQ: SWKS ) and NXP Semiconductors (NASDAQ: NXPI ) being big contributors for the period. Equally, a lower allocation to the underperforming energy sector during the year compared to the benchmark helped the fund mitigate losses to its portfolio, adding 75 bps to the allocation effect. Another, perhaps more recognizable, example is American Funds Investment Company of America (MUTF: AIVSX ) . The fund posts a one-year return of 4.71%, while its benchmark chalks up a 7.36% return. Attribution analysis shows the fund had a negative allocation effect of 1.03% and a negative selection effect of 1.62%. While the fund’s heavier weighting in Merck & Company (NYSE: MRK ) placed a 49-bp drag on the portfolio, it was under-allocated to the healthcare sector compared to its benchmark, tagging on an additional 94 bps of drag from that sector alone. In the passive versus actively managed portfolio debate there are times when one approach is better than the other. Knowing that time can be difficult, so steering clients to both actively and passively managed products can often be the right decision. Providing examples of when certain sectors are out of favor, when markets are flat, or when the manager is truly providing alpha can be shown using attribution analysis, which supports the inclusion of actively managed products. While passive proponents often give the nod to actively managed funds in the less efficient fund groups (emerging markets, small-caps, and municipals), as shown above attribution analysis and good research can help ferret out some hidden gems, even in well-covered, widely held classifications. Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.