Author Archives: Scalper1

Scrutinizing International REIT ETFs
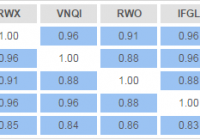
Correlations with S&P 500 have declined to around 0.70 in the last year. International REIT ETFs appear to be more correlated to S&P 500 than their counterparts investing solely in the U.S. Largest international REIT ETFs share almost identical risk profile. In a separate article last week I took a look at how U.S. real estate investment trust (“REIT”) ETFs affect the overall portfolio risk and tried to assess the extent of the diversification benefit they offer. This time I would like to extend the analysis to international REIT ETFs and scrutinize them from the risk perspective. For the purpose of this article the focus will be on the four largest and most established global REIT ETFs: the SPDR Dow Jones International Real Estate ETF (NYSEARCA: RWX ), the Vanguard Global ex-U.S. Real Estate ETF (NASDAQ: VNQI ), the SPDR DJ Wilshire Global Real Estate ETF (NYSEARCA: RWO ), and the iShares International Developed Real Estate ETF (NASDAQ: IFGL ). All of these funds manage at least $950m of assets and have been around for a while, giving us enough historical data for meaningful analysis (the most junior one is VNQI launched in November 2010). To begin with, I inspect the correlation matrix of these ETFs including the SPDR S&P 500 Trust ETF (NYSEARCA: SPY ) as a proxy for the broader equity market. The calculations were carried out on InvestSpy using almost 5 years of historical data (truncated to VNQI’s inception date): The table above shows that global REIT ETFs are fairly highly correlated between each other with coefficients ranging from 0.88 to 0.96. Not surprisingly, the least correlated with others is RWO, which is the only one offering exposure to the U.S. market with a substantial 58% country weighting. Perhaps more unexpected observation is that international REIT ETFs have higher correlations with SPY than their U.S. counterparts. As outlined in my previous article , global REIT ETFs had correlation coefficients with SPY below 0.80 over the same period. To verify if the findings above hold true in a more recent period, I checked correlation coefficients for the last 12 months: RWX, VNQI and IFGL remained highly correlated between each other (coefficients of 0.94-0.97), however RWO drifted away significantly, highlighting diverging performances of international and U.S. REITs. Furthermore, correlations with S&P 500 weakened across the board in the last year although the effect was yet again not as pronounced as in local U.S. REITs. The fact that international REITs are more correlated with S&P 500 than REITs investing in the U.S. only looks a bit like a mystery as intuitively one would expected exactly the opposite to be true. I can only speculate about potential drivers of this effect. The first thought that springs to my mind is that currency movement could be accountable for this. Indeed, simplistic factor analysis reveals that a basket of currency ETFs could have explained about 40% of movement in RWX. However, this is a fairly average number for an internationally diversified fund and thus does not imply anything unusual. Alternative explanations could be more of fundamental nature: e.g. U.S. investors understand the local real estate market better and see it more like a standalone asset class, whilst international real estate is put in the same bucket with stocks. Correlations aside, the table below depicts further risk metrics of the global REIT ETFs utilizing last 12 months data: (click to enlarge) Annualized volatility, beta and maximum drawdown readings are comparable for RWX, VNQI and IFGL. Meanwhile, RWO realized considerably lower beta and annualized volatility, once again presenting itself as a middle option between international and U.S. REIT ETFs. Summing up, international REIT ETFs appear to be more correlated to S&P 500 than their counterparts investing solely in the U.S. Somewhat surprisingly, this means that global REIT ETFs offer lower diversification benefit to a U.S. investor. Furthermore, three of the largest international REIT ETFs (RWX, VNQI and IFGL) share almost identical risk profile, thus an investor needs to look more closely at other ETF features such as expense ratio and bid-ask spread. RWO sits somewhere in the middle between international and local REITs and may be a good choice for someone who wants a bit of worlds. Last but not least, correlations do change over time and a smart investor will monitor them periodically to achieve the intended outcome. Disclosure: I am/we are long VNQI. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Are Investors Choosing The Right Indices And ETFs?

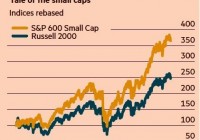
Summary ETFs are financial instruments that add an extra layer of risk that may not be suitable or ideal for all investors. Interestingly, since 2000, the S&P 600 has significantly outperformed it’s counterpart, the Russell 2000. Subconsciously, fund managers may be hurting their returns by stating they are “overweight” or “underweight” a stock, especially if using an easy to beat benchmark. Individual investors can gain an edge on professional fund managers by simply investing in indices and ETFs with a superior long-term track record. It’s conceivable that “brand names” will start to matter, as ETFs and Index Funds become more popular over the next decade. Introduction Warren Buffett has famously stated that Americans are better off investing in a simple index fund like the Vanguard S&P 500 ETF (NYSEARCA: VOO ). Investing in the S&P 500 exposes investors to American businesses and allows them to reap the benefits of an expanding and capitalistic economy. Branching away into different indices and ETFs introduces investors to varying degrees of risk and fall empty handed on the returns advertised. For example, an ETF that is composed of 30 securities is not only priced based on its underlying portfolio of securities, but also in accordance to the supply and demand of the ETF itself. This double jointed structure introduces several liquidity and volatility risks to investors in times of market turbulence and downturns. Furthermore, there are all sorts of differentiated structures that provide for excessive risk in hopes to achieve higher returns. Notably, all levered bull and bear ETFs. These structures introduce another layer of unknowns and risks for investors, with the speculative potential to increase returns. However, an investor is likely to achieve not only a lower risk profile, but higher returns by simply scrutinizing their portfolio with a careful eye– looking for an edge. The Russell 2000 vs The S&P 600 For the conservative investor, a seemingly simple question of investing in an ETF covering the Russell 2000 (like the iShares Russell 2000 ETF ( IWM)) or the S&P 600 (like the SPDR S&P 600 Small Cap ETF ( SLY)) can yield dramatically different results. As reported by the Financial Times on Monday August 17, 2015, the S&P 600 has outperformed its counterpart the Russell 2000 since year 2000–by a significant margin. Specifically, since the beginning of 2000, the S&P 600 would have turned a $100 investment into a little over $360 and a $100 investment in the Russel 2000 would have turned into approximately $250. Image Sourced from Finanical Times Hence, the framework on an underlying index can have a profound influence on an index’s performance, the related ETF’s performance, and an investor’s overall return. The S&P 600 may cover a slimmer portion of the small cap universe, but this may be for good reason. After all, an investor only needs to own 30 stocks to be amply diversified from systemic market risk. According to the Financial Times, the S&P 600 index requires companies to have a record of making profits before it is included in the index. Furthermore, it sets a far higher standard for liquidity (compared to Russell 2000). It’s no wonder then that small-cap investment firms use the Russell 2000 to track their performance against. It’s easier to beat! It’s amazing how two simple rules can create significant long-term value for clients and investors. As such, it appears reasonable to assume that an index’s brand and portfolio construction will have even more of an impact on investors’ decisions going forward. How robot advisors and, to an extent, human advisors, will account for these seemingly minute details remains to be seen. Regardless, a wise and enterprising investor will have an edge. A passive minded investor, with an enterprising spirit, would be able to increase their returns by sacrificing a small amount of time to discover discrepancies such as this-especially long-term investors who have 15+ year time horizons. Index Business Growing In Size and Power Building ETFs based on indexes has become a huge business, with hundreds of billions riding on the skirts of simple structures. The owners of these indexes, whether it’s MSCI (NYSE: MSCI ), FTSE Russell, or the S&P (NYSE: MHFI ) will continue to have more and more power and influence on the financial markets-along with their clients like Vanguard and Blackrock (NYSE: BLK ). Whether or not they use this power wisely is another question, one that I’m not overly optimistic about. Furthermore, transparency can be a double-edged sword. For instance, the Russell 2000 follows very transparent rules by alerting investors in advance which stocks will move in and out on the day each June when the index is reshuffled (making it easier to beat). The S&P 500 Index has discretion to include companies that have a history of recording a profit, maintaining a balance between sectors, and typically only includes new companies when a vacancy is created (often through a merger). Invariably this causes the stock to pop as it is added to the S&P 500 Index, creating agony among fund managers attempting to beat it. Psychology of the Index Behavior psychology (or anything to do with human behavior) continues to have a heavy influence on the performance of fund managers. It’s well-known that investors and fund managers must account for self-bias and over-confidence once they buy a particular security, otherwise their judgment may become impaired and make mistakes. Recently, there has been a change in the way fund managers and analysts talk about their portfolios. For instance, they often speak of being “overweight” or “underweight” a particular stock, rather than stating they “own” a stock. By stating that they are “overweight” or “underweight,” fund manager’s are subconsciously increasing the influence a benchmark index has on their portfolio allocation and investment returns. It’s well known that the majority of actively managed mutual funds fail to beat their benchmarks. Therefore, it stands to reason that individual investors should outperform fund manager’s who chose the Russell 2000 as their benchmark–by simply investing in the S&P 600! While past performances do not guarantee future returns, it’s hard to argue the long-term track-record of the S&P 600 compared to the Russell 2000 over the past 15 years. In essence, investors who look at a stock as a fractional ownership of an underlying business will have both a psychological and fundamental advantage over other investors during a long-term time horizon. Fund managers that state they “own” a stock are still subject to subconscious self-bias and overconfidence; however, it’s likely they would focus more of their time on the fundamentals of the business, rather than the makeup of a particular benchmark. A stock’s total return, after all, is proportional to the company’s long-term operating performance and returns on capital, not because of its weighting in a particular index. Conclusion Just like it’s never wise to ask your barber if you need a haircut, investors shouldn’t accept over-simplified financial products and investments, especially from Wall Street. A little bit of research and passion to find an edge can go a long way. Remember that in a group of 100 investors, only 49 can be better than average-despite everyone’s opinions that they are in the top 20%. Managing your time wisely and performing diligent research has the potential to add a percentage or two to your total returns over your lifetime. In addition, you will incur fewer trading and tax expenses due to mistakes and disappointments. Apply diligent research, patience, and a long-term time horizon to maximize the benefits you receive from the miracles of compound interest. Don’t let sloppy benchmark indices get in your way–invest in the best ones. Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. (More…) I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.

Sprint Momentum Builds On Back-To-School Promotions

Sprint (S) has gained marketing momentum, says Pacific Crest Securities, which forecasts that wireless industry promotional activity might pick up during the back-to-school shopping period. While some Wall Street analysts have recently said aggressive discounting appeared to be easing, perhaps until the Q4 holiday shopping season, others say Apple’s (AAPL) expected rollout of the iPhone 6S in mid-September could bring a new round of price cutting.